How international conflicts affect you
Behind all wars are economic interests and, as evident and painful as it is, today’s conflicts are no exception. Beyond religions or visceral hatred, there is always an economic context. In conversation with James Sène, president of 11Onze, we analyse the geopolitical context and its consequences.
For days, Israel’s war on Palestine has entered a phase of unprecedented virulence that is shaking the world. While the media and networks try to compete in portraying rawness and pain, the geopolitical ramifications of the conflict remain in the background. But US President Joe Biden made his economist view of the conflict very clear when he addressed the nation from the Oval Office to ask Congress for extraordinary funding.
The US president, beyond the epic rhetoric of America’s self-proclaimed role in the world, claimed that providing money to support Israel and Ukraine would be “an investment that will pay dividends for decades to come”. Talk of investment in the midst of a humanitarian crisis seems frivolous, and it is, but wars are business and business is good.
But what is at stake for the United States and the world economy in this conflict, and why does the world’s leading power, at a time of record indebtedness, decide to continue borrowing to “invest” in conflicts?
To analyse the international geopolitical situation and understand the economic consequences for all of us, Toni Mata talks to the president of 11Onze, James Sène.

Safeguard yourself against economic crises with the ultimate safe-haven asset: gold. If you want your savings to have value in the future, Gold Patrimony.
More and more economists are warning of an imminent financial collapse. But what lies behind this fear narrative? Beyond macroeconomic data, the real risk may be the human reaction: distrust, massive flight of assets, and the self-fulfilling prophecy. When the market believes everything is collapsing, that is often the moment it truly does.
We live in an economy driven as much by emotions as by data. Indicators matter, but confidence—or the lack of it—is the real engine. When a media-savvy economist announces an imminent crisis, they’re not just reporting; they’re shaping behaviour—of investors, consumers, and even governments. The economy, after all, is a living organism that reacts to the dominant narrative. If that narrative is fear, fear becomes monetary policy, a flight to safe havens like gold, and ultimately, economic reality. It’s the self-fulfilling prophecy at work.
This mechanism is even clearer in the digital era. Rumours of a “2026 collapse,” central banks hoarding gold, or fears of a dollar meltdown don’t just reflect data—they create it. Today’s markets are arenas of collective perception, where the economy plays out as much in charts as in social media headlines. In this landscape, narrative becomes an economic weapon capable of moving capital, reshaping expectations, and turning fear into market motion.
Fear as a strategy of power
Economic history shows that crises are not only the result of financial excesses but also of control strategies.
After 1929, panic allowed Wall Street to be restructured. After 2008, panic legitimized massive bank bailouts. And today, amid a global debt crisis, panic may justify new forms of financial control—such as state digital currencies (CBDCs) —which promise security but restrict individual freedoms.
Fear is not just an emotion; it’s a tool of economic governance. Central banks know this and use it to steer capital flows. When fear becomes monetary policy, financial democracy falls into recession.
The role of gold and lost confidence
It’s true that gold, as explained in many articles on La Plaça, is a historical safe haven. But the reason it’s breaking records today is not merely economic—it’s anthropological: it represents lost confidence in modern systems. Yet if massive gold buying is driven more by panic than by strategy, it may create a new bubble—a “confidence bubble.” The more people flee the system, the more unstable that system becomes.
That’s why, beyond hoarding gold out of fear for the future, we must also learn to manage panic. Invest with reason, diversify with knowledge, and understand that trust is an asset as valuable as gold itself.
Financial education as a vaccine
At 11Onze, we’ve often said that without financial education, we are vulnerable. Predictions of collapse work because many citizens don’t understand how economic cycles function.
Learning about finance is the best way to immunize ourselves against collective panic. The more we understand market mechanisms—how sovereign debt is created, how capital moves, how interest rates are set—the less power fear has to dictate our decisions. Perhaps the real collapse will not be economic but cognitive, when a society reacts before it understands.
Crises always come—but they also pass. What defines the maturity of a financial community is how it prepares, not how it panics. Panic breeds volatility; knowledge builds stability. And in that balance lies the key to preserving the economic freedom we all need.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.


In an increasingly unpredictable financial world, knowing what major investors are doing can make the difference between reacting late or anticipating the next move. Two little-known indicators —the DIX and the GEX— help us read this hidden flow. You don’t need to be a Wall Street analyst to understand them; you just need to observe the market with a trained eye.
When you look at a stock or an index price, you’re only seeing the tip of the iceberg. Beneath the surface lie thousands of institutional trades that never go through public exchanges. Large funds, banks, and insurers often operate in spaces called dark pools —literally “dark swimming pools”— where they can buy or sell massive volumes without the market noticing immediately.
These parallel spaces help avoid sharp price swings, but they also reveal the true institutional sentiment: that’s where the big players make their move before anyone else sees it.
To measure what’s happening there, the company SqueezeMetrics created the DIX, or Dark Index. This indicator shows whether institutions are buying or selling inside these opaque markets.
The DIX: the footprint of big money in the dark
Imagine you’re in a supermarket. In the public area, people are shopping as usual. But there’s a door in the back where loaded carts roll out —that’s the big buyers’ zone. The DIX tells us whether those carts are full or empty. In other words:
- A high DIX (above 45%) means net institutional buying. The big players are quietly accumulating shares —a signal of optimism, buying now what they believe will be worth more tomorrow.
- A low DIX (below 40%) means net selling. The big players are reducing exposure or taking profits, often before a correction.
This indicator doesn’t tell us when the market will move, but it does show who is moving —and in which direction. When institutional money flows in, markets usually rise in the following weeks. When it flows out, turbulence often follows.
The GEX: the temperature of volatility
If the DIX tells us what is happening, the GEX —Gamma Exposure— tells us how. Here we look at market makers, the intermediaries who provide liquidity to the options market, particularly around the S&P 500.
These professionals use a strategy called delta hedging to manage risk. Depending on the volume of call and put options, they adjust their positions. The GEX measures how much those adjustments might cushion or amplify market moves. Thus:
- A high GEX means stability —market makers are acting as shock absorbers, damping volatility.
- A low or negative GEX means tension —their adjustments amplify each move, making the market nervous, like a taut string that can snap on any news.
Put simply: the GEX is the emotional thermometer of the market. When it rises, there’s calm. When it drops, there’s fear.
Combining DIX and GEX: an institutional compass
No single indicator is perfect, but together they offer a much richer view. The DIX shows what institutional money —funds, insurers, banks, and pension managers— is doing, while the GEX shows how the market might react. For example, many professional managers read them together as a combined signal of sentiment and risk.
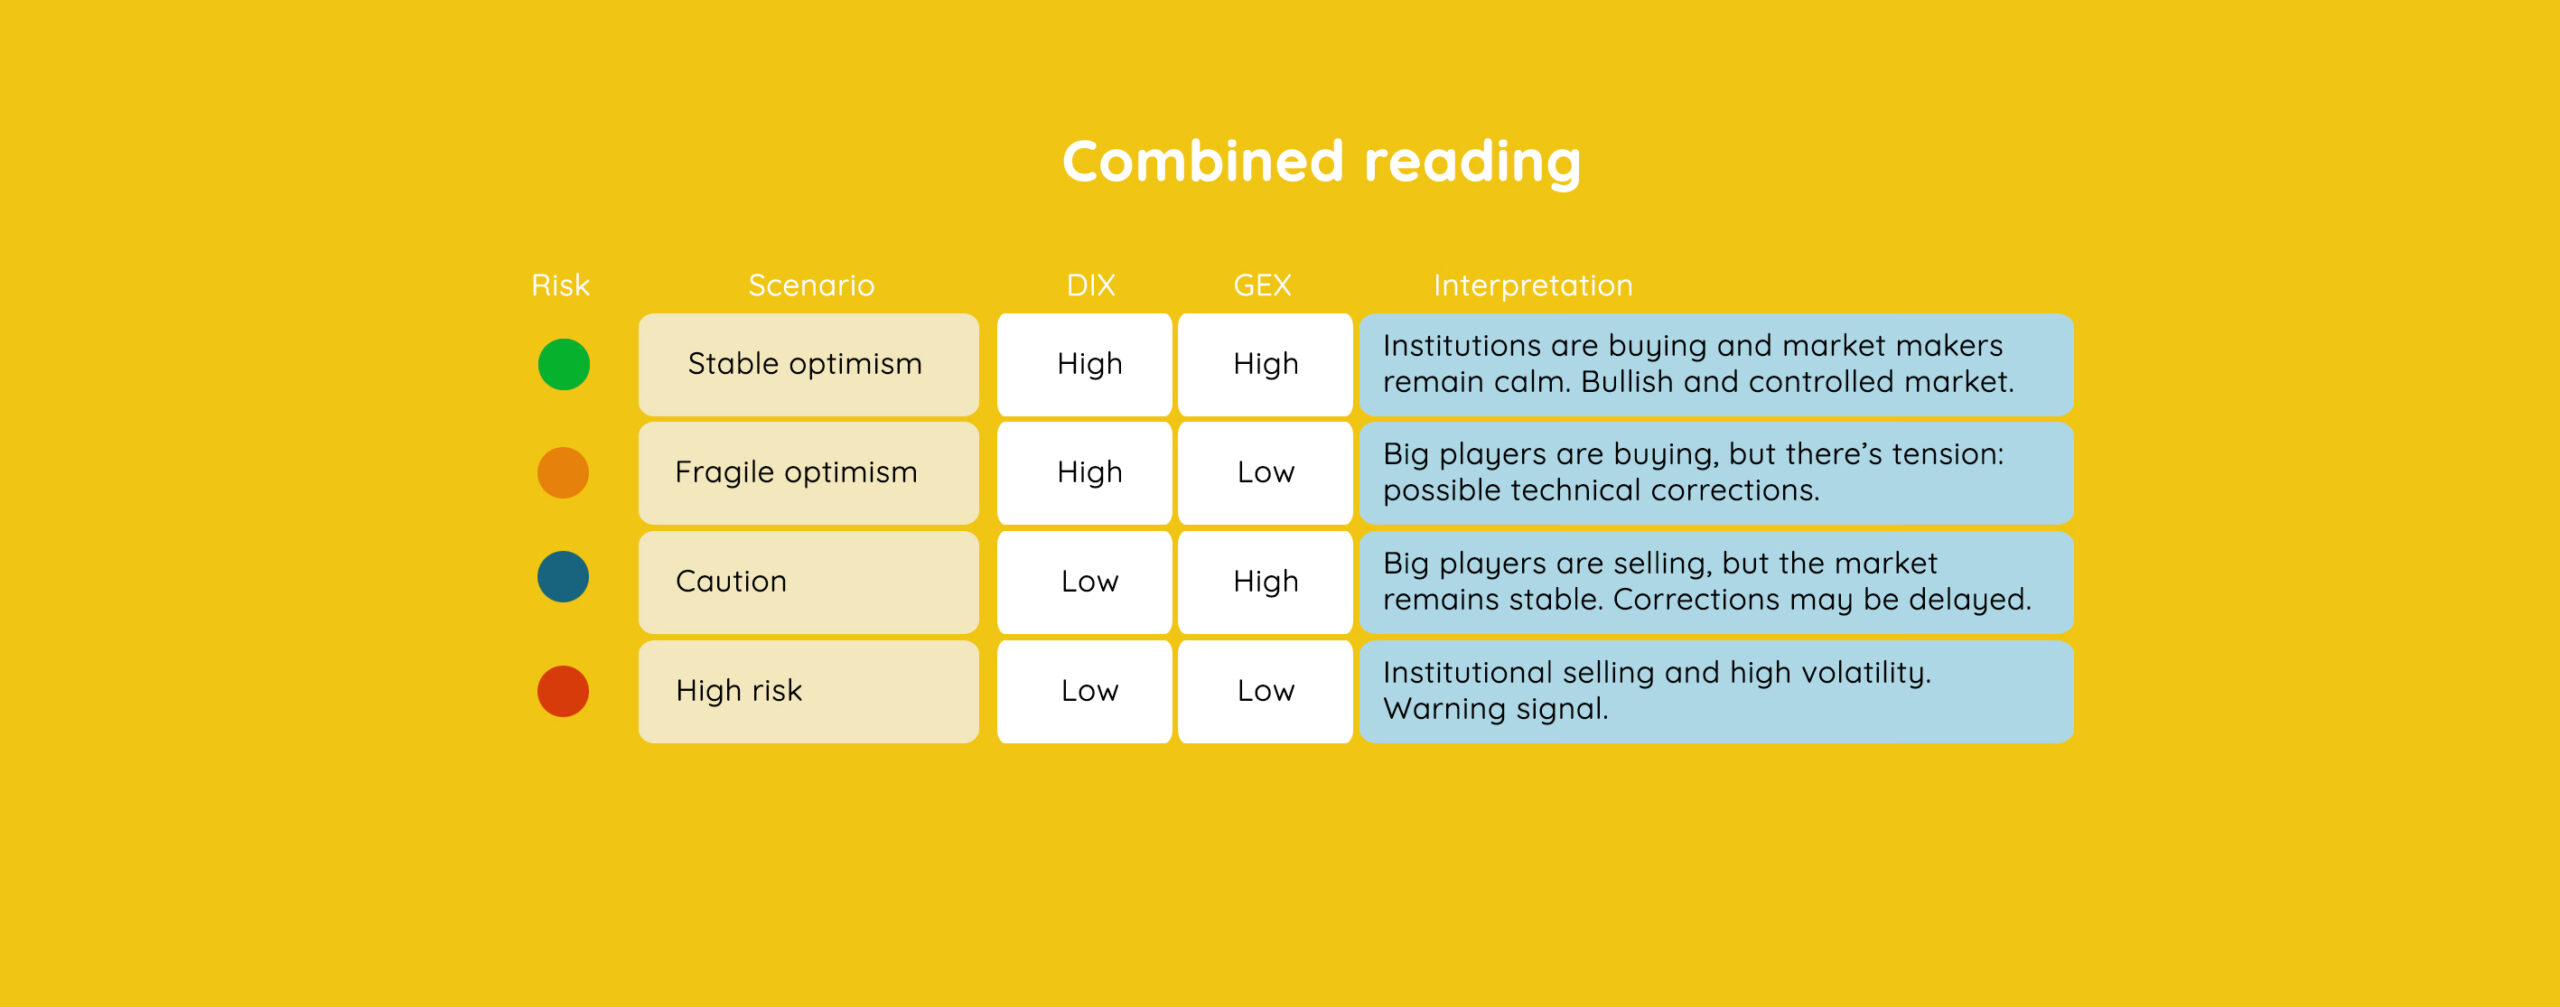
There is no need to guess the future, just interpret the present with context.
A real example: March 2020
During the first weeks of the pandemic, the DIX plunged while the GEX turned negative. Institutions were selling, market makers were amplifying the moves, and the result was one of the fastest market crashes in history.
By late March, the DIX started rising again as the GEX recovered —and the market began its spectacular rebound. This combination signaled the trend reversal days before most retail investors noticed. You might not have a research team or an algorithm tracking institutional flows, but understanding these indicators helps you read the market’s emotions more clearly.
Knowing when “smart money” flows in or out is like having a weather map: it doesn’t stop the storm, but it helps you decide whether to carry an umbrella.
The term refers to large professional investors —banks, hedge funds, insurers, or public institutions— with access to superior information, tools, and analytical capacity compared to retail investors. They’re often the first to detect economic cycle shifts or market turning points, and their capital flows can foreshadow what the rest of the market will do later.
Following the trail of smart money isn’t about imitation —it’s about interpreting the market’s true sentiment. If these institutions quietly accumulate positions, they’re probably expecting better times. If they’re reducing exposure, a storm may be coming. The goal isn’t to predict the future, but to read the signals left by those who move the most influential capital.
Moreover, DIX and GEX remind us of a fundamental lesson: markets move not just on data or news, but on collective behavior —of investors, institutions, and intermediaries. Understanding that behavior is key to investing with reason rather than emotion.
Seeing behind the market’s curtain
The financial world frequently looks like a chess match between giants. But even small players can watch the board and understand the moves. Indicators like DIX and GEX let us glimpse the hidden institutional dynamics —the forces that move prices but rarely make headlines.
They’re not magic tools or instant trading systems, but they help interpret trends and measure risk. Used wisely, they let us act with more logic and less emotion —and in finance, that’s a major advantage.
Markets don’t reward those who guess —they reward those who understand. DIX and GEX aren’t crystal balls, but they are windows that let us peek behind the curtain of big capital. Learning to read them is learning to read human behaviour in its purest form: fear, greed, and confidence.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
For decades, the automotive industry has been one of Europe’s great industrial strengths. But the model that turned Volkswagen, Mercedes-Benz, BMW, Renault and Stellantis into global benchmarks is under pressure.
Manufacturing on the continent is expensive, the technological transition requires multibillion-euro investments, and China has built an industry capable of producing electric vehicles at much lower costs. The consequences are already visible: workforce cuts, oversized factories and new cars that are increasingly difficult to afford. An industrial crisis that is inevitably also transforming the second-hand market.
The crisis facing Europe’s automotive industry is often presented as a consequence of the transition to electric vehicles, but the problem runs deeper. Europe is suffering from a combination of high costs, excess production capacity, technological dependencies and increasingly aggressive international competition.
The sector remains enormous: it accounts for approximately one trillion euros of European GDP and directly or indirectly employs around 13 million people. Precisely for this reason, the European Commission itself acknowledges that the industry is at a “critical inflection point” in the face of technological transformation and increasing global competition.
For decades, European manufacturers perfected the combustion engine until it became one of their great competitive advantages. Now they have to transform factories, train workers and invest billions in batteries, software, electronics and new platforms while continuing to support much of the old industrial structure. In a way, it is like having to rebuild the plane while it is still flying.
China is no longer competing on cheap labour alone
The problem is that Europe is undertaking this transformation at a time when its Chinese competitors have already achieved enormous scale in some of the technologies that will define the car of the future.
According to the International Energy Agency (IEA), the cost of manufacturing an electric vehicle in China is more than 30% lower than in advanced economies. Battery cells alone are, on average, more than 30% cheaper than in Europe. It is not merely a question of labour costs: production scale, automation, a highly integrated supply chain and access to components and critical minerals all play a role. The gap continues to widen. In 2025, battery packs were approximately 35% cheaper in China than in Europe.
At the same time, the global centre of gravity of the automotive industry has shifted. China already accounted for 35.4% of global passenger car production in 2024, while European Union production fell by 6.2%. This forces European brands to compete on price while financing a costly industrial transformation. A particularly difficult combination.
Job cuts are the symptom
When factories can produce far more cars than the market can absorb profitably, sooner or later an adjustment follows.
Volkswagen agreed to cut more than 35,000 jobs in Germany by 2030 and reduce the production capacity of its German plants by around 734,000 units. The company itself links these measures to the contraction of the European market and increasing competition.
The crisis also extends to suppliers. In 2025, Bosch announced an additional 13,000 job cuts, mainly in its German mobility division, after identifying an annual gap between costs and revenues of around €2.5 billion in this area. The company directly points to falling demand, overcapacity and the need to restore competitiveness.
Therefore, job cuts are not the origin of the problem, but rather the result of an industry that simultaneously needs to invest more and spend less.
What happened to the affordable car?
For consumers, this transformation has a much more tangible consequence: new cars have become enormously more expensive.
In Spain, the average price offered by dealerships rose from €30,513 in 2019 to €44,419 in 2025, an increase of 45.6%, more than twice the accumulated inflation over the same period. The increase is even more striking in traditionally affordable segments: prices for A-segment cars rose by 78.3%, while B-segment cars increased by 46.7%.
Not all of this increase is due to electrification. Vehicles now incorporate more technology and mandatory safety systems, production costs have increased, and the supply problems caused by the pandemic have also left their mark. But manufacturers have contributed to the phenomenon through a commercial decision: prioritising larger, better-equipped vehicles with higher margins.
In the European electric vehicle market, for example, C-segment SUVs and models in higher segments went from accounting for 28% of sales in 2020 to 64% in 2024.
The business logic is easy to understand. If a company sells fewer cars, it can try to compensate by making more money on each unit. The problem arises when this strategy turns the car, traditionally a mass-market product, into something increasingly inaccessible to the middle class.
The second-hand market absorbs the blow
When a new vehicle becomes too expensive, the need for mobility does not disappear. Buyers simply look for an alternative.
In 2025, 2.22 million second-hand passenger cars were sold in Spain, almost two for every new vehicle. And 57.3% of transactions involved cars more than ten years old. This figure exposes a contradiction that is difficult to ignore. Europe wants to accelerate the renewal of its vehicle fleet to reduce emissions, but high prices are pushing many families to keep their cars for longer or buy an older one. If replacing a vehicle is economically inaccessible, the transition slows down, no matter how ambitious the regulations may be.
However, an interesting shift has emerged during 2026. Growing competition from new brands, many of them Chinese, has forced manufacturers and dealerships to increase promotions. By July, the average discount on the list price of new cars had already exceeded 14%, while the average price had fallen to €43,477. It remains well above the 2019 level, but the trend has begun to change.
And this price war has reached the second-hand market. Nearly-new cars less than a year old had seen their average price fall by almost 10% in the first quarter of 2026 and, during the first half of the year, the correction was already affecting even cars more than ten years old. It is a clear example of the extent to which the arrival of new competitors can disrupt the entire value chain.
Europe needs to bring back the affordable car
The battle facing Europe’s automotive industry is not simply about manufacturing more electric cars. It is about managing to produce them at a price that allows them to be sold on a mass scale without destroying companies’ margins or the jobs that depend on them.
Europe still has powerful brands, engineering expertise, human capital, an extensive network of suppliers and decades of industrial experience. But history does not guarantee future competitiveness. If its manufacturers need €40,000 or €50,000 to offer a vehicle that a competitor can sell considerably more cheaply, the problem cannot be solved through tariffs or regulations alone.
Europe also needs to regain efficiency, scale and, above all, an idea that was fundamental to its automotive industry for decades: the affordable car. The paradox is that Europe wants to renew its vehicle fleet, electrify mobility and reduce emissions, but it will struggle to achieve this if a growing share of the population can only afford to drive a fifteen-year-old vehicle.
The big question, therefore, is not only whether Europe will be able to manufacture the car of the future. It is a much more fundamental one: whether European citizens will be able to afford it.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.
If you would like to learn more about this topic, we recommend:
 Economy
The transformation of the automotive industry
7 min readIn a new episode of La Plaça en Territori 17 we analyze...

In the same way that we take out loans and other financing mechanisms when the money we earn is not enough to cover our household expenses, it is common for a State to borrow money when its income is insufficient to meet its budgetary needs. We explain where this financing comes from and the consequences of high public debt.
Public debt or sovereign debt is the total money owed by all the public administrations of a State to private investors or other countries, while the negative balance that gives rise to the need for financing is known as the public deficit. It is a form of financing that allows a country to raise immediate revenue when tax revenues are not sufficient to cover its budgetary needs and to repay it gradually over time.
Although the figures may be surprising, sovereign debt in itself is neither good nor bad. Countries can require financing for public investment to stimulate economic growth, without suffering the consequences of raising taxes or issuing more of their own currency.
That said, borrowing to make an investment that will generate value for the economy is not the same as borrowing to cover uncontrolled spending. Likewise, there are countries that are able to afford high levels of debt because the financial markets have confidence in their ability to pay, thanks to the stability of their economies or their national currency.
Financing through public debt securities
Depending on the financing needs of each country, there are different models for issuing public debt securities. The repayment term of the loan, short, medium or long term, and the various ways of earning interest determine the main differences.
Treasury bills have the shortest repayment term of 3, 6, 12 and up to 18 months and therefore offer a lower interest rate than Government Bonds, with a term of between two and five years, which also distribute coupons to investors, which are collected on a regular basis.
Finally, governments can issue long-dated Government Bonds with maturities of up to 30 years, designed for long-term investors seeking a higher interest return. Precisely because these are assets with such a long maturity period where the interest rate does not depend so much on the monetary policy of the country’s central bank, but on structural factors of the economy, they are a good barometer of the degree of investor confidence in the future economic stability of a state.
Budget imbalances and runaway public indebtedness
Expansionary public investment policies in the wake of the economic stagnation caused by the health crisis have pushed the sovereign debt of many countries to historic highs. Economists and international organisations are concerned about the high level of global public debt, which may end up being unsustainable for developing economies.
In other words, debt is a necessary instrument for growth, as long as it is sustainable, but the reality is that public debt figures in the world have risen considerably in recent years, approaching those of global GDP, and are therefore far from this sustainability. Spain’s public debt continues to set historical records, the latest being last August when it reached a figure of 1.49 trillion euros after rising by 4.44 billion.
Data published by the Bank of Spain on Friday 21 October in its latest economic report showed that in the last 12 months the debt has increased by a further 72,029 million euros. Eurostat also said that eurozone debt in the second quarter also reached a record high of 12.1 trillion euros. How do you pay for all this?
Some analysts say that public debt is never really paid off, i.e. it is never reduced in absolute terms because it is always being rolled over. Even when a state goes bankrupt, as happened with Greece in 2008, the conditions are renegotiated and new debt is issued. In practice, however, we are all paying for it, unequally. As happened in Greece, those who have the least pay the most, those who keep cash in their pockets or current accounts, see their money lose more and more of its value.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
The United States has accumulated one of the largest mountains of debt in the world, but this is not, in itself, the figure that worries economists the most. The real problem is that it increasingly has to allocate more money to paying the interest on that debt, which reduces the room available to finance other public policies.
When a growing share of the budget is used simply to keep accumulated debt alive, the risk no longer depends only on how much is owed, but on the cost of continuing to finance it. And this is where a debt crisis stops being an abstract hypothesis and becomes a risk that affects the entire global economy.
To understand the problem, there is no need to master complex economic concepts. Imagine a family that spends more than it earns every year and covers the difference by borrowing money. For a while, the situation may be manageable, especially if interest rates are low. But each new loan is added to the previous ones and, over the years, the family not only has to keep financing its deficit, but also has to pay the interest on the accumulated debt.
Allowing for all the differences, this is the dynamic putting pressure on US public finances. According to projections by the Congressional Budget Office, the United States government will spend around $7.4 trillion in 2026, while revenues will stand at around $5.6 trillion. This leaves a deficit of close to $1.9 trillion.
It is important to distinguish the deficit from the debt. The deficit is the gap generated during a specific year. Debt is the accumulation of previous deficits. Put graphically, the deficit is the water that keeps flowing into the bathtub; the debt is all the water that has already accumulated in it.
A debt larger than the economy
The scale of this accumulation is already considerable. The CBO estimates that federal debt held by the public will reach approximately 101% of US GDP in 2026 and could rise to 120% in 2036 if there are no significant changes in fiscal policy.
This percentage is important because it allows debt to be compared with the country’s economic capacity to sustain it. Owing a lot is not necessarily a problem if the economy grows enough and creditors continue to trust the country’s ability to repay. That is why exceeding 100% of GDP does not automatically mean being on the verge of bankruptcy.
What it does mean is greater vulnerability to interest rates. The larger the debt, the greater the impact of any increase in the cost of financing it. And this is precisely where the US situation has become more complicated in recent years.
When interest payments start to weigh
For much of the past few decades, the United States was able to live with rising debt because borrowing was relatively cheap. Interest rates were low, and this made it possible to refinance large volumes of debt without the bill soaring.
The situation is now different. The CBO expects the federal government to allocate more than $1 trillion to net interest payments in 2026, a figure that could exceed $2.1 trillion a year by 2036.
This spending has an important characteristic: it does not finance hospitals, roads, education or research. It simply remunerates the creditors who lent money to the government. The greater the weight of interest payments within the budget, the less room there is to allocate resources to other priorities.
In addition, a large share of the debt periodically reaches maturity and has to be refinanced. If those bonds were issued at a time of very low interest rates and now have to be replaced by new securities offering a higher return, the financial cost increases automatically.
When debt feeds more debt
From this point onward, a dynamic that is difficult to break can emerge. If the government maintains high deficits, it needs to issue more debt. This new debt generates new interest payments, which increase spending and can widen the deficit even further.
Therefore, the problem is not only that the United States owes a lot of money, but that the very cost of the debt can contribute to making it grow.
The CBO estimates that net interest payments will rise from 3.3% of GDP in 2026 to 4.6% in 2036. In this scenario, a growing share of public revenues will simply be used to pay the cost of previous budgetary decisions.
This is where the difference lies between having a lot of debt and starting to have a debt problem. A powerful economy can sustain high levels of indebtedness for a long time, but if debt persistently grows faster than the economy, the situation becomes increasingly demanding.
A crisis does not need to begin with a default
When we think of a debt crisis, we often imagine a government announcing that it cannot pay. But in the case of the United States, a crisis could begin much earlier.
The first sign could simply be investors demanding higher returns in order to keep buying Treasury bonds. If they perceive that the fiscal path is becoming increasingly unsustainable, they may demand higher interest rates in exchange for continuing to lend money.
An apparently small difference in interest rates can have a huge impact when applied to tens of trillions of dollars. And this effect would not be limited to US public finances.
Treasury Bonds are a central benchmark for the international financial system. If their yields rise, mortgages, business loans and the debt of other governments can also become more expensive. That is why a crisis of confidence in US debt would have global repercussions.
The extraordinary privilege of the dollar
The United States, however, has an advantage that almost no other country has: it borrows in its own currency, and that currency is also the world’s main reserve currency.
This greatly reduces the risk of a conventional bankruptcy. The Treasury issues debt in dollars and the Federal Reserve has the capacity to provide liquidity to the system. It is an extraordinary privilege that gives Washington far more room for manoeuvre than almost any other economy would have.
But that room is not unlimited. If monetary creation were used excessively to facilitate debt financing, the consequences could emerge through another channel: higher inflation, a depreciation of the dollar or a gradual loss of investor confidence.
Put another way, being able to create the currency in which the debt is paid reduces the risk of default, but it does not eliminate the economic cost of excessive indebtedness.
Everything depends on confidence
In the end, the key word is this: confidence. There is no exact figure beyond which a state automatically enters a crisis. What determines debt sustainability is investors’ confidence in the government’s ability to keep paying without having to resort to extreme measures.
For decades, the United States has enjoyed a privileged position thanks to the size of its economy, the depth of its financial markets and the international role of the dollar. This combination explains why the world remains willing to finance Washington despite its recurring deficits.
But that confidence is not infinite. The important question, therefore, is not whether the United States will go bankrupt tomorrow. The question is how long it can maintain a trajectory in which debt grows faster than the economy and interest payments absorb an increasingly large share of the budget.
A US problem with global consequences
As long as investors remain willing to buy US debt at an affordable cost, the system can continue to function. But if that cost rises on a sustained basis, the problem stops being a simple accounting figure and becomes a real constraint on the economy.
A US debt crisis, therefore, would not necessarily begin on the day Washington stopped paying. It could begin much earlier, at the moment when the world demanded an increasingly high price to continue lending it money.
And when the borrower is the country that issues the world’s main reserve currency and sits at the centre of the international financial system, the bill is unlikely to remain only at home.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.

A diferència de les divises fiat, el Bitcoin és una moneda digital descentralitzada que no està sotmesa al control d’un govern o banc central. El seu valor no està definit per una entitat, sinó que es deriva de la confiança del consumidor. Però en què es fonamenta aquesta confiança?
Tot i les diferències, les criptomonedes com el Bitcoin comparteixen algunes similituds amb les monedes fiduciàries tradicionals a les quals tots estem acostumats. Per tant, és important entendre què dona valor als diners fiat abans d’analitzar per què hi ha un gran nombre de persones que veuen al bitcoin com un dipòsit de valor.
Lluny queda un sistema monetari segons el qual el valor de les divises està sostingut per la seva convertibilitat a l’or. D’ençà que el president Richard Nixon va reunir el seu equip a Camp David per anunciar que suspenia la convertibilitat del dòlar amb l’or. El dòlar va passar de ser una moneda que basava el seu valor en l’existència d’una contrapartida en or, a ser una moneda fiduciària, diners fiat, amb un valor que deriva de la relació entre l’oferta i la demanda i l’estabilitat del govern emissor.
Així doncs, els governs i els bancs centrals poden crear diners per ampliar la seva oferta monetària i estimular la despesa a través de mecanismes econòmics sense preocupar-se de tenir suficients reserves d’or, almenys això és la teoria. Per tant, tot i que aquestes monedes fiduciàries no estan sostingudes per actius tangibles, el seu valor és causat per la confiança col·lectiva en les divises. Com a contrapartida, les polítiques monetàries dels governs i banc centrals, així com l’evolució de l’economia poden fer fluctuar aquesta confiança i el valor de la moneda.
Descentralització, seguretat i oferta limitada
L’ecosistema monetari del Bitcoin està totalment descentralitzat, és a dir, cap autoritat central regula la base monetària, eliminant la necessitat d’intermediaris i atorgant als usuaris més control sobre les seves transaccions financeres. En eliminar les autoritats centrals, es democratitza la creació de moneda, donant més poder i llibertat a la comunitat d’usuaris.
La creació de Bitcoins segueix unes regles detallades en un protocol molt estricte que es basa en la tecnologia blockchain. Aquesta tecnologia de cadena de blocs utilitza algoritmes criptogràfics i la fa més segures que les monedes físiques i altament immune a crisis. A més, si l’usuari vol fer una transferència o un pagament, té total llibertat, ni el banc, ni VISA, ni Mastercard l’han d’autoritzar. Aquestes característiques i el fet milers de comerciants ja accepten Bitcoin com a pagament per béns i serveis, li han donat un valor d’utilitat.
Per altra banda, des de la seva introducció, es va establir un límit màxim de 21 milions de monedes que es poden minar, la qual cosa introduïa un element d’escassetat intrínsec que també contribueix a donar-li valor, quan tenim en compte la relació entre preu i escassetat. És per això que molta gent considera el Bitcoin com a reserva de valor, tot i la seva volatilitat. La regulació global dels criptoactius i la competència amb altres monedes digitals marcaran el futur del Bitcoin, però en última instància, serà la confiança de la gent el que assegurarà, o no, la seva existència.
11Onze Recomana Bitvavo, les criptomonedes de manera fàcil, segura i a baix preu.
With climate change, natural disasters are becoming more frequent. And it is not always your insurance that is responsible for compensating you when any of your insured property suffers damage.
Climate change is causing increasingly extreme weather events. Long periods of drought and record high temperatures sometimes give way to heavy rain or hailstorms. One example is the hailstorm that hit regions such as Baix Empordà, Gironès and Pla de l’Estany at the end of August. The hailstones, some of which more than ten centimetres in diameter, even caused the death of a 20-month-old girl.
Beyond the impossibility of compensating for such personal misfortunes, insurance policies may cover some material damage linked to natural disasters, but they do not necessarily cover all of it. Moreover, the characteristics of the incident will determine whether we have to be compensated directly by our company or by the Insurance Compensation Consortium. This entity covers extraordinary risks in the event of certain natural catastrophes. However, only and exclusively in the event that the affected property is insured.
Damage to vehicles and homes caused by hail or hailstone, very typical at the end of summer, is not covered by this “extraordinary risk” coverage. Therefore, it is our own company that should compensate us according to the coverage contracted. If our car insurance includes windows, we can claim for windows damaged by hail. But dents in the sheet metal will only be compensated if we have comprehensive insurance.
As for damage to crop fields and livestock or livestock farms, these are not covered by the Consortium either. There is a state system to cover them, the Agroseguro, which gives the right to economic compensation if we have insured any of these areas against a specific meteorological phenomenon and are damaged by it.
What does the Insurance Compensation Consortium cover?
This entity is responsible, among others, for damages to our insured goods caused by extraordinary floods, earthquakes, tidal waves, volcanic eruptions, atypical cyclonic storms and the fall of sidereal bodies or aerolites.
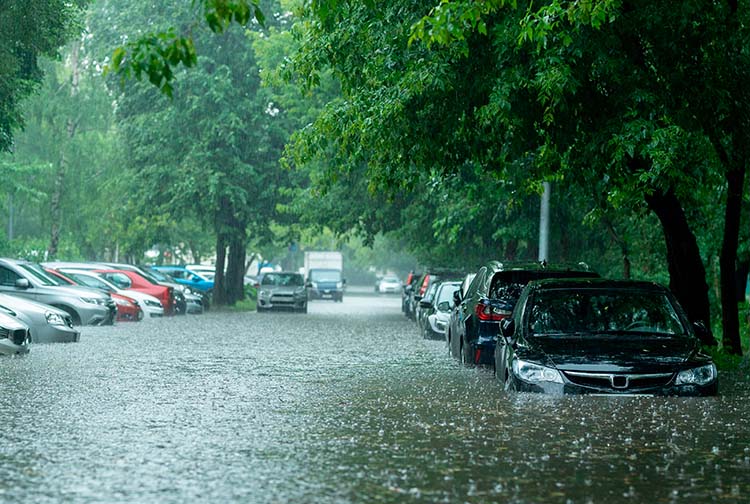
Of the above natural catastrophes, floods cause the most damage in Catalonia. And, for the purposes of coverage, they are considered as “the flooding of land caused by rain or thawing; by water from lakes with a natural outlet, from estuaries or rivers, or from natural watercourses on the surface when they overflow their normal channels”, according to the Consortium itself. It also includes the impact of the sea on the coast, even if there is no flooding.
It should be taken into account that this concept of flooding does not include rain falling directly on the insured risk, or that collected by its roof or rooftop, its drainage network or its patios, nor flooding caused by the bursting of dams, canals, sewers, collectors and other artificial underground channels unless the bursting has occurred as a direct consequence of the extraordinary event covered by the Consortium.
In the case of an atypical cyclonic storm, tornadoes and extraordinary winds, characterised by gusts of more than 120 Km/h, are included, among others.
The insured person is fully entitled to compensation, even if the public authorities do not issue an official declaration of “catastrophe” or “catastrophe zone”. However, in order for this body to cover damage caused by earthquakes, tidal waves, volcanic eruptions and falling sidereal bodies or aerolites, it must be certified by the National Geographic Institute or the competent public body in the matter.
When does the Consortium not cover the damage?
According to the Regulation of the Insurance of Extraordinary Risks, we will not be entitled to compensation from the Insurance Compensation Consortium despite having insured the damaged property in some circumstances.
One of the cases is when the insurance contracted is for the transport of goods, construction and assembly, civil liability, health, legal defence or travel assistance. The same exclusion applies to policies covering agricultural production that can be insured through the Combined Agrarian Insurance system.
As for the type of damage, for example, those caused by alterations in the supply of any kind of energy are not covered. Neither is the loss of profits as a consequence of damage suffered by other goods or by other natural or legal persons other than the insured person covered.
How the Consortium is financed
The Insurance Compensation Consortium, which depends on the Ministry of Economic Affairs and Digital Transformation, is financed by a percentage of each vehicle and home insurance policy that is taken out.
It is important to bear in mind that this type of compensation has nothing to do with the aid that may be offered by public administrations in the event of declaring a specific area of the territory a “catastrophic zone” due to some extreme meteorological effect.
If you want to discover fair insurance for your home and for society, check 11Onze Segurs.
If you liked this article, we recommend you read:
El deute públic en el món s’ha disparat en els últims anys i les seves xifres ja són similars a les del PIB global. Tot i que pot ser un recurs molt útil per estimular l’economia en moments d’estancament o per millorar la competitivitat d’un país, els actuals nivells de deute generen molta inquietud per com pot llastrar el creixement.
En macroeconomia, el deute públic no es considera necessàriament una cosa dolenta. De fet, pot ser molt positiva. Tot i que costi digerir aquesta afirmació contraintuïtiva, la veritat és que els Estats l’han utilitzat des de fa segles per finançar-se sense que, en la majoria dels casos, hagi conduït a la ruïna dels països.
Què determina llavors la seva incidència positiva o negativa en l’evolució de l’economia? Per què el que hauria de ser un recurs pot convertir-se en una llosa? Hi ha tres factors clau: com s’utilitzen aquests diners, el context competitiu global i el volum de deute.
Oli per al motor econòmic
L’economia és un complex engranatge que periòdicament passa per alts i baixos, en cicles que es van encadenant. Quan aquest engranatge s’encalla, el deute públic pot servir com a lubrificant per a millorar el seu funcionament. D’aquí ve que els Estats tendeixin a aplicar polítiques d’inversió pública expansives quan l’economia s’estanca i hagin d’aprofitar els cicles de creixement econòmic, en els quals augmenten els seus ingressos gràcies a la major recaptació, per a equilibrar els seus comptes.
El deute públic té conseqüències tant en el present com en el futur. L’objectiu més immediat és facilitar recursos per a evitar el col·lapse econòmic. Si en un context de crisi una empresa normalment rendible veu reduïdes les seves vendes i entra en números vermells, podria arribar a tancar. Com a conseqüència, augmentaria l’atur i el que fins llavors eren ingressos per a l’Estat gràcies als impostos sobre les seves vendes passarien a ser despeses en forma de prestacions per desocupació. Al seu torn, els menors ingressos dels treballadors reduirien la seva capacitat adquisitiva, amb la qual cosa cada vegada més empreses es veurien en una situació precària per la reducció de la demanda.
Per això el deute públic s’utilitza en un primer nivell per a frenar la sagnia en situacions excepcionals a través d’ajudes i estímuls fiscals que evitin la destrucció de teixit productiu. Això explica, per exemple, que ara es plantegi una rebaixa en la quota d’autònoms per evitar el tancament de moltes microempreses. I fins i tot el subsidi per desocupació i altres despeses corrents es podrien considerar instruments per evitar que la demanda s’enfonsi en un context d’estancament o recessió.
Si l’endeutament conjuntural fa possible que el sistema prengui aire i torni a ser competitiu sense els estímuls públics, l’economia podria sortir reforçada. Però si aquest endeutament tan sols serveix per mantenir viu el teixit productiu de manera artificial, estaríem davant una economia zombi, incapaç de sobreviure sense els estímuls públics, així que el deute podria fer-se crònic. D’aquí la importància de com s’utilitza el deute públic i d’acompanyar aquesta inversió de les necessàries reformes estructurals.
Competitivitat, la paraula màgica
Més enllà de parar el cop en una crisi, el deute públic també pot servir per augmentar el potencial de creixement d’una economia. La inversió pública en infraestructures, educació, sanitat o polítiques actives d’ocupació pot enfortir les bases per al futur desenvolupament.
Tot i que en un primer moment poden incrementar-se el dèficit i el deute, com a contrapartida tindrem una economia més forta. I això suposarà una major capacitat per fer front al pagament d’interessos i l’amortització del deute gràcies a la major recaptació.
Un exemple de bona praxi bastant acceptat és la inversió que va suposar la American Recovery and Reinvestment Act després de la crisi financera de 2007-2008. Els més de tres quarts de bilió de dòlars de despesa aprovats pel Congrés nord-americà van permetre modernitzar les infraestructures i xarxes tecnològiques als Estats Units. A més, la reforma sanitària i del sistema de desocupació va millorar la cohesió social. Tot això ha contribuït al fet que l’economia nord-americana es trobi avui dia en una situació una mica menys compromesa que l’europea.
De tota manera, des de fa bastants anys els països desenvolupats s’enfronten a una inquietant pèrdua de competitivitat, la qual cosa complica el seu creixement econòmic i limita la seva capacitat per equilibrar els seus nivells de deute.
Els riscos d’un deute excessiu
És necessari tenir present que, encara que el deute no sigui dolent en si mateix, suposa un compromís de devolució amb interessos en el futur. I això pot arribar a restringir el marge financer i pressupostari de l’Estat si no es produeix un augment d’ingressos que el compensi. A més, l’emissió de deute públic pot atreure capital que d’una altra manera es destinaria al finançament del sector privat.
Tot i que el límit de deute públic que estableix el Tractat de Maastricht per als Estats és del 60 % del seu PIB, el conjunt de països de la zona euro ja porta un any per sobre del 100 %, segons dades d’Eurostat. La situació fora d’Europa no és millor, ja que el Fons Monetari Internacional estima que, a finals de 2021, el deute públic global representava el 100 % del PIB mundial. I la situació podria empitjorar si la crisi s’accentua.
Espanya ja porta més d’una dècada per sobre de la recomanació del 60%. De fet, el Fons Monetari Internacional va fer una sèrie d’advertències a Espanya al març pel risc que el deute s’estanqui en cotes superiors al 115 % del PIB. Però, en vista de l’evolució actual, serà difícil que aquesta ràtio es redueixi en el futur pròxim. I més si tenim en compte l’estructura demogràfica, que en els pròxims anys dispararà la despesa en pensions.
La majoria d’economistes adverteixen contra aquest excés de deute públic. És significatiu que una revisió de 40 estudis publicats durant la dècada passada indiqui que 36 d’ells conclouen que el deute té una influència negativa en el creixement econòmic.
11Onze és la fintech comunitària de Catalunya. Obre un compte descarregant la super app El Canut per Android o iOS. Uneix-te a la revolució!
When we hear an economist talking about taxes, inflation, wages or housing, we tend to think that their conclusions are purely technical. But reality is different. Behind every economic proposal lies a particular way of understanding how society works. Economics is a social science. And, like all social sciences, it is made up of different schools of thought that interpret reality from different perspectives.
For more than three hundred years, these schools have attempted to answer the same questions: what creates wealth, what role the State should play, why crises occur, and how they should be addressed.
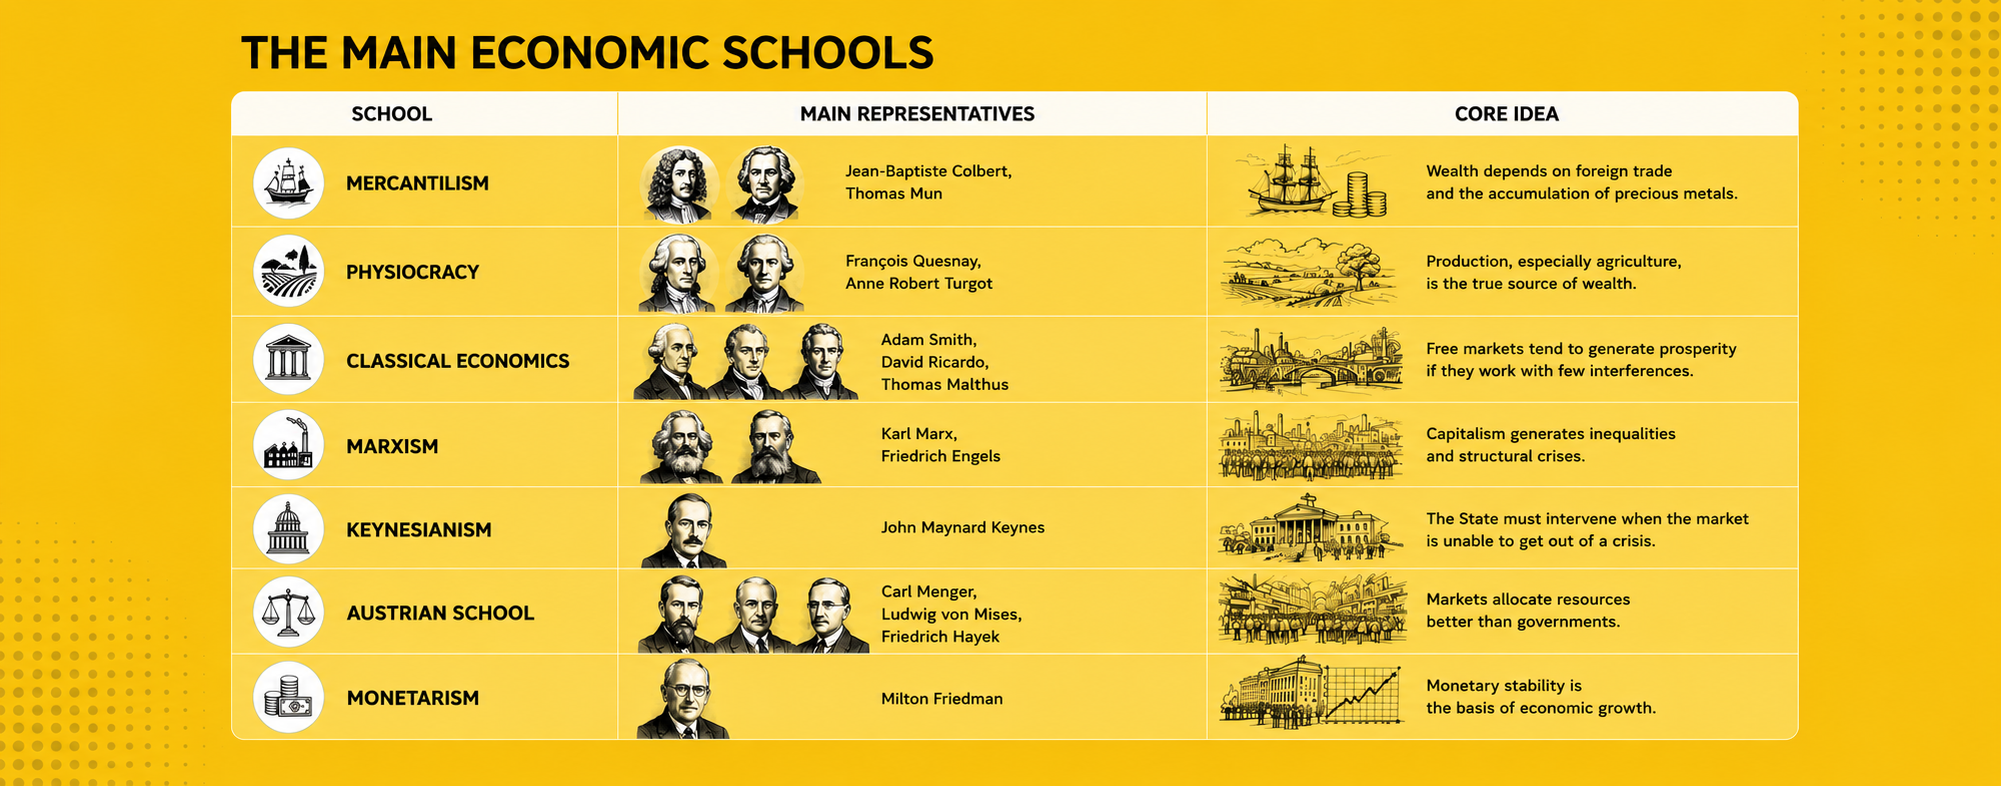
Each school is a product of its time. Mercantilism emerged when the European monarchies competed for world trade; Adam Smith wrote during the Industrial Revolution; Karl Marx observed the harsh conditions of nineteenth-century workers; John Maynard Keynes sought to explain the Great Depression; Friedrich Hayek and Milton Friedman reacted to the inflation of the 1970s. What is most remarkable is that none of these schools has disappeared. All of them continue to influence, to a greater or lesser extent, the economic policies of governments, central banks and international institutions.
The major schools of economic thought at a glance
Schools also have a history
Each economic school emerged in an attempt to respond to the major challenges of its time.
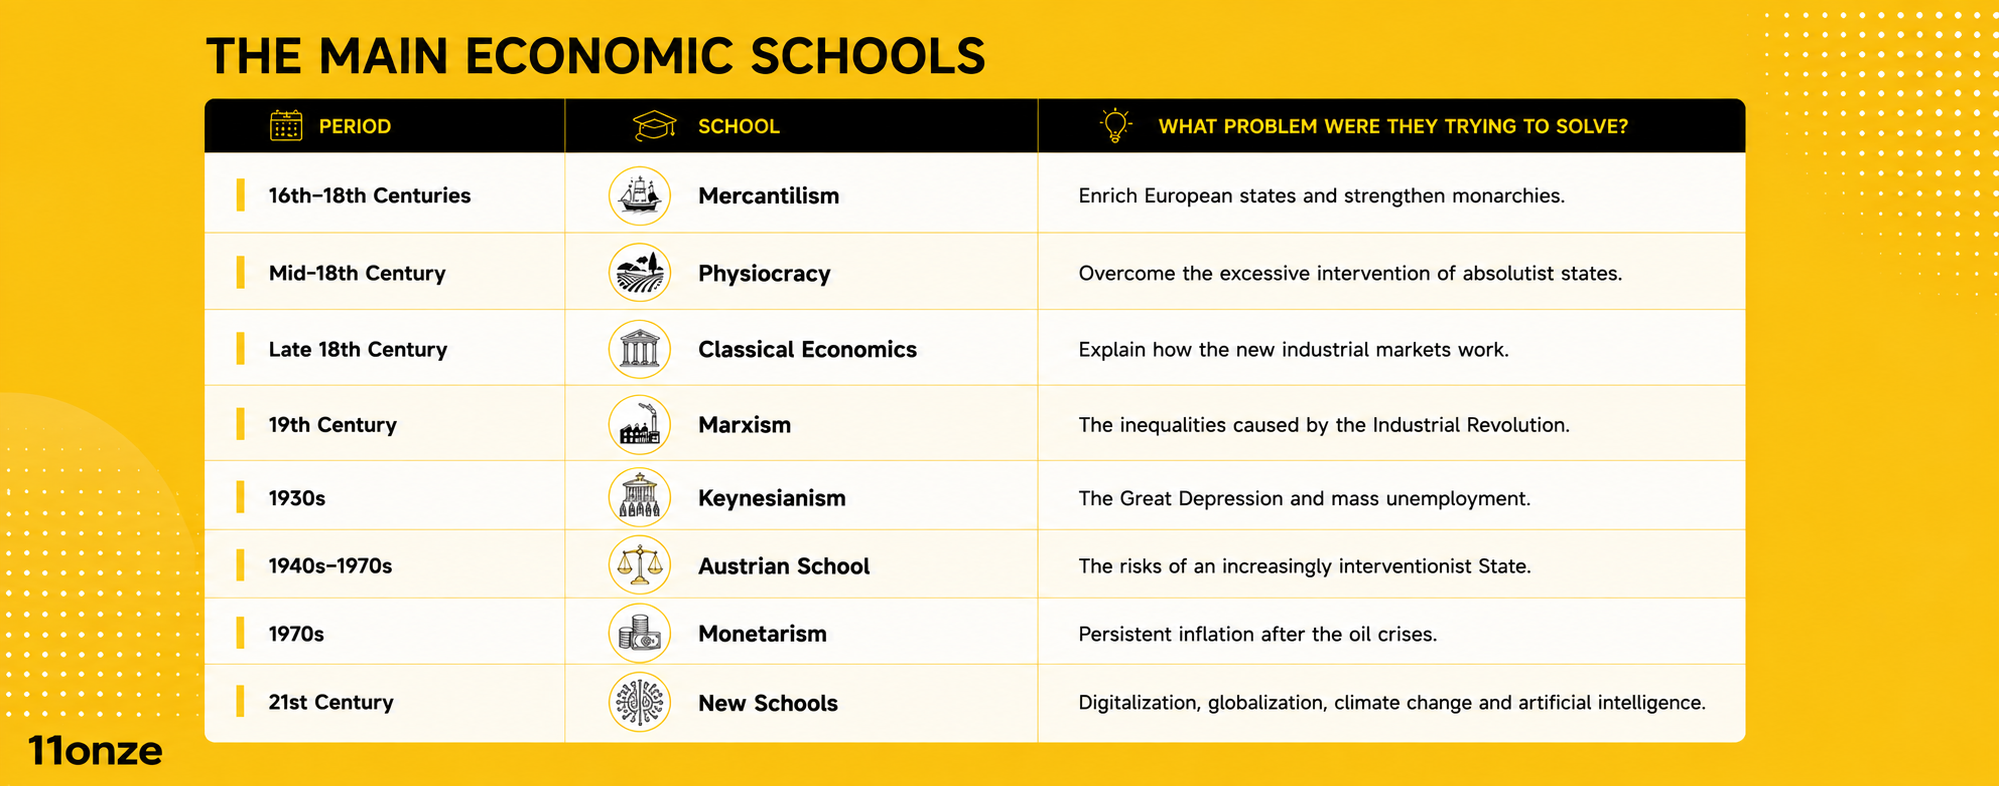
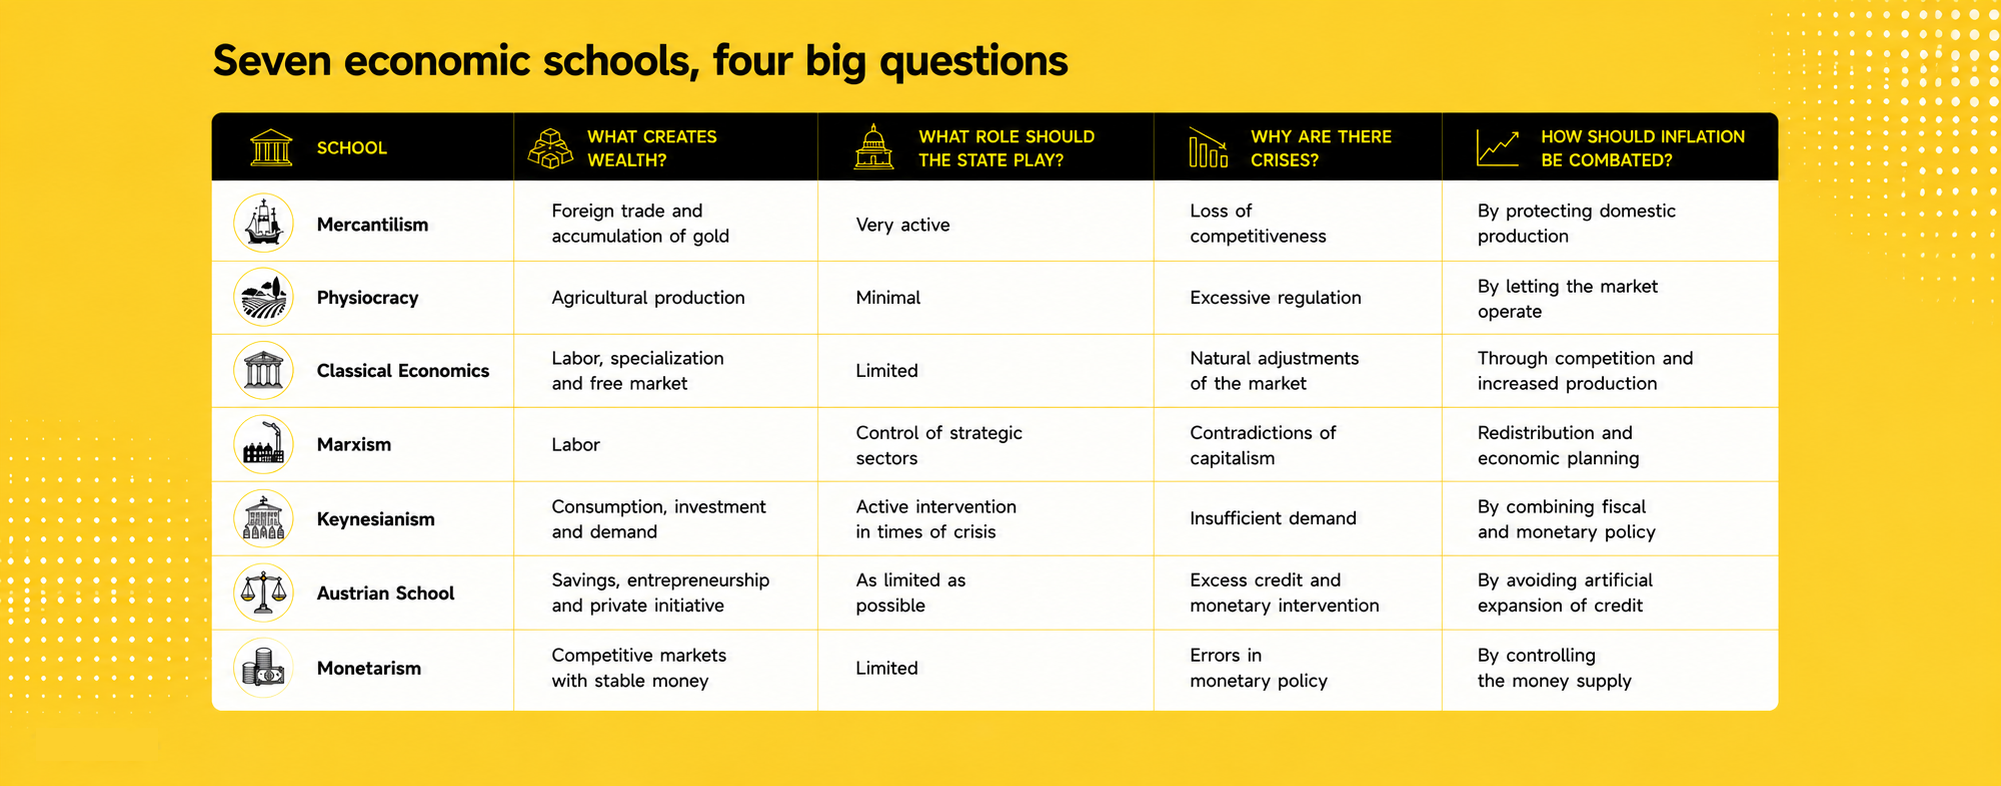
This summary highlights one essential idea: the schools of economic thought do not disagree only about the solutions. They often disagree about what the real problem actually is.
What creates wealth?
This is the first great question that has divided economists for centuries.
Mercantilists believed that prosperity depended on accumulating gold and maintaining a positive trade balance.
The Physiocrats overturned this idea by arguing that wealth originated from production.
Adam Smith expanded this concept: prosperity is the result of labour, specialisation, innovation and the freedom to exchange.
Karl Marx also placed labour at the centre, but argued that the capitalist system allows part of the value created by workers to be appropriated by the owners of capital.
Keynes shifted the focus towards demand. An economy may produce a great deal, but if households and businesses stop consuming, factories come to a halt.
For Austrian and Monetarist economists, sustainable growth requires saving, productive investment, entrepreneurial initiative and a stable currency.
What role should the state play?
This is where the best-known differences emerge.
Mercantilists advocated strong governments that directed trade.
Classical economists preferred to limit the State to basic functions such as justice, security and infrastructure.
Marx envisioned an economy in which the principal means of production were collectively owned.
Keynes believed that, during recessions, the State should stimulate demand and prevent economic activity from collapsing.
By contrast, Hayek warned that excessive intervention could reduce economic freedom and generate new inefficiencies.
Milton Friedman shared this caution, although he accepted a limited role for the State in ensuring stable rules and a consistent monetary policy.
Why do crises occur?
The same recession can generate completely different diagnoses.
For Marx, crises are part of the very functioning of capitalism.
For Keynes, they are the result of a decline in consumption and investment.
Austrian economists attribute them to excessive credit expansion and artificially low interest rates.
Monetarists emphasise mistakes in monetary policy.
Classical economists tend to interpret them as adjustment processes that markets eventually correct.
How should inflation be fought?
Few issues generate as much controversy as this one.
Keynesians accept that moderate inflation may be acceptable if it prevents a deep recession.
Milton Friedman argued that “inflation is always and everywhere a monetary phenomenon,” that is, the consequence of an excessive amount of money in circulation.
The Austrian School shares much of this diagnosis, but places the main responsibility on the artificial expansion of credit driven by central banks.
Classical economists trust that competition and market adjustments will eventually moderate prices.
Marxists, by contrast, tend to interpret inflation within the framework of distributional conflicts between wages, profits and economic power.
The new schools: Economics continues to evolve
The classical schools remain essential for understanding economics, but the new challenges of the twenty-first century have given rise to schools of thought that incorporate factors which previously played only a secondary role.
Behavioural economics: we do not always make rational decisions
For decades, it was assumed that people made rational decisions. Daniel Kahneman and Richard Thaler demonstrated that cognitive biases, emotions and habits influence many economic decisions.
This discipline has influenced the design of savings plans, pension systems, taxation and public policies based on the so-called nudges—small incentives that guide behaviour without imposing it.
Institutional economics: Institutions matter
Why do some countries prosper while others remain stagnant despite possessing abundant natural resources?
Economists such as Douglass North, Daron Acemoglu and James Robinson argue that the answer lies in the quality of institutions. Legal certainty, the protection of property rights, judicial independence and the fight against corruption are factors that are just as important as capital and labour.
Modern monetary theory (MMT): A new debate on public debt
Modern Monetary Theory argues that a State which issues its own currency has far greater room for manoeuvre than has traditionally been assumed. According to this school, the main constraint on public spending is not the budget deficit, but inflation.
Its supporters argue that this approach makes it possible to deal more effectively with major public investments or economic crises. Its critics warn that it could encourage the excessive creation of money and fuel inflationary pressures.
The debate remains open and is one of the most active in contemporary economics.
An ongoing conversation
Economics is not a collection of infallible recipes. It is a conversation that has lasted for more than three centuries and continues to evolve with every social, technological and political transformation.
No school has succeeded in explaining the whole of reality, but each has provided tools for understanding part of the world. For this reason, when we hear an economist defending a particular fiscal, monetary or social policy, it is worth asking not only what they are proposing, but also from which school of thought they are speaking.
Understanding these traditions does not guarantee that we will always find the correct answer, but it does allow us to interpret, with greater judgement, the debates that shape our savings, our investments and the future of the economy.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.