How much money should you keep in the bank?
Amb l’actual inflació, els diners al banc no fan més que perdre valor dia rere dia. Però sempre és necessari mantenir una mica de liquiditat per si sorgeix algun imprevist. Per això els experts recomanen tenir un “matalàs” d’efectiu en els teus comptes d’estalvi que cobreixi com a mínim tres mesos de despeses.
La vida està plagada d’imprevistos. També en el pla econòmic. A vegades són positius, com un augment de sou, però a vegades hem d’afrontar sorpreses desagradables que fan mossa en la nostra butxaca. Pot ser des d’una despesa puntual extraordinària, com quan hem de reposar un electrodomèstic vell de casa, fins una cosa més seriosa, com patir una malaltia incapacitant o quedar-nos sense treball.
Per fer front a aquestes eventualitats, és necessari disposar d’un fons d’emergència. L’antic costum de guardar els diners en el matalàs o en qualsevol altre amagatall de la casa et permet disposar d’ells de manera immediata, però és poc recomanable pel risc de robatori i la nul·la rendibilitat.
És preferible recórrer a les entitats bancàries, tot i que has de tenir en compte el límit del Fons de Garantia de Dipòsits d’Entitats de Crèdit per a que els teus diners sempre estiguin protegits.
Assegura els teus estalvis
Com detalla el seu web, aquest organisme “té per objecte garantir els dipòsits en diners i en valors o altres instruments financers constituïts en les entitats de crèdit, amb el límit de 100.000 euros per als dipòsits en diners”.
Això desaconsella tenir més de 100.000 euros en comptes i dipòsits a termini d’una mateixa entitat, ja que el fons només cobrirà fins a 100.000 euros per titular en cas que el teu banc faci fallida.
Si, per exemple, tinguessis 120.000 euros en una entitat que ha fet fallida, encara que fora en diversos comptes o dipòsits, aquest organisme només et retornaria 100.000 i perdries els altres 20.000. D’aquí la conveniència de repartir els diners entre diverses entitats per a que els comptes i dipòsits no superin el límit garantit en cap d’elles.
De quant parlem?
Només en casos molt excepcionals el nostre fons d’emergència hauria d’assolir aquests 100.000 euros, especialment en un moment com aquest, en el qual l’elevada inflació fa que els diners dipositats al banc perdin valor mes rere mes. De totes maneres, l’import òptim dependrà en última instància de les nostres circumstàncies personals: bàsicament, quines són les nostres despeses previstes i amb quins ingressos podríem comptar en cas d’un esdeveniment negatiu.
Els experts solen recomanar que el coixí financer cobreixi com a mínim tres mesos de despeses. Cal tenir en compte que mantenir un saldo massa baix en el nostre compte ens pot fer entrar en números vermells amb facilitat, la qual cosa generaria despeses financeres pel descobert.
L’OCU, per exemple, indica que una quantitat prudent en els comptes corrents “pot ser l’equivalent a tres mesos del teu salari”. No recomana més perquè aquests comptes “no són el millor lloc per a mantenir els nostres estalvis, ja que pràcticament cap entitat les premia amb interessos”.
Quant al màxim, no sol recomanar-se més del necessari per a cobrir sis mesos de despeses. De fet, el portal ‘Finances per a tots’, una iniciativa del Banc d’Espanya, la Comissió Nacional del Mercat de Valors i el Ministeri d’Assumptes Econòmics i Transformació Digital, aconsella “acumular un fons equivalent a entre tres i sis mesos de despeses”. A partir d’aquí es tracta de buscar inversions que garanteixin una bona rendibilitat.
11Onze és la fintech comunitària de Catalunya. Obre un compte descarregant la super app El Canut per Android o iOS. Uneix-te a la revolució!
Although the major international economic organisations try to send a reassuring message about controlling inflation, the UK’s experience in the 1970s raises serious doubts. Gold appears to be an interesting option to protect against the depreciation of money amid a “bear market” cycle that could last longer.
For months now, inflation has been far exceeding the optimistic forecasts of the major international economic organisations. The harsh reality means that time and again these institutions are forced to recalculate their forecasts upwards.
They all coincide in sending out a reassuring message. The mantra is that this year’s out-of-control rates will tend to moderate in 2023 and that by 2024 a rate close to the desired 2 % will be restored. The interest rate hikes by the major central banks should make a decisive contribution to this.
The latest to make this point is the International Monetary Fund, which, in a report, predicts that wage restraint will prevent a dangerous inflationary spiral.
Learning from the past
However, some economists warn that there are parallels between the current situation and the stagflation experienced in the UK half a century ago. Since 1970, the British government had been doping the economy with expansionary budgets and lower interest rates. As a result, inflation soared to 9.1 % in 1973, similar to today’s rate.
As now, interest rates had started to rise. Between June and November 1973 they rose from 7.5 % to 13 %, which led to the bursting of the housing bubble and the ensuing banking crisis. Moreover, between May 1972 and January 1975, the main stock market index lost 74 % of its value. The economic slowdown did not prevent inflation from spiralling out of control: it reached 16% in 1974 and a whopping 24.2% in 1975.
The big concern is that history will repeat itself. The bad news is that the spread between the inflation rate and interest rates is now much wider than it was then, so the monetary policy correction could have a much more devastating effect on the economy. The overall contraction in bank credit will be severe and many firms will become insolvent.
At current inflation rates, interest rates and the cost of government debt would logically soar. And, predictably, central banks will do what they have always done in the past to deal with this type of crisis: print more banknotes, which will further reduce their real value.
Gold, a safe-haven asset
The rise in interest rates in the early 1970s was no obstacle to the appreciation of gold: it went from less than £18 per ounce when interest rates were 6% to more than £40 when they rose to 13% in November 1974. For, as the founder of J.P. Morgan said, “gold is really money, everything else is credit”.
Since the suspension of the Bretton Woods agreements in 1971, which meant abandoning the gold standard, the sum of banknotes and commercial bank credit has increased more than 30-fold, which is equivalent to its devaluation. In fact, middle-class single-earner households were common before 1970 and are now a utopia. Buying a house or even a car without going into debt has become a privilege only within the reach of a few rich people.
Gold, on the other hand, has taken the opposite path to that of the money supply and its value has increased 38-fold. In fact, since December 2015, gold has appreciated by more than 40% against the euro.
Endorsed by the biggest hedge fund
Hence, the recommendation by Bridgewater Associates, the world’s largest hedge fund, to buy physical gold is not surprising, despite the fact that many investors see the current depreciation of many other financial assets as a buying opportunity.
Rebecca Patterson, chief investment strategist at Bridgewater, says the reason for going into gold is the need to protect against a “bear market” phase that is set to continue over time. Consequently, the logic of buying assets in the economic downturn, when prices are low, only to sell when the economy expands and rises again may not hold true this time around.
Moreover, both the Chinese and Indian economies are regaining their historical appetite for gold, which will contribute to gold prices in the short term.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
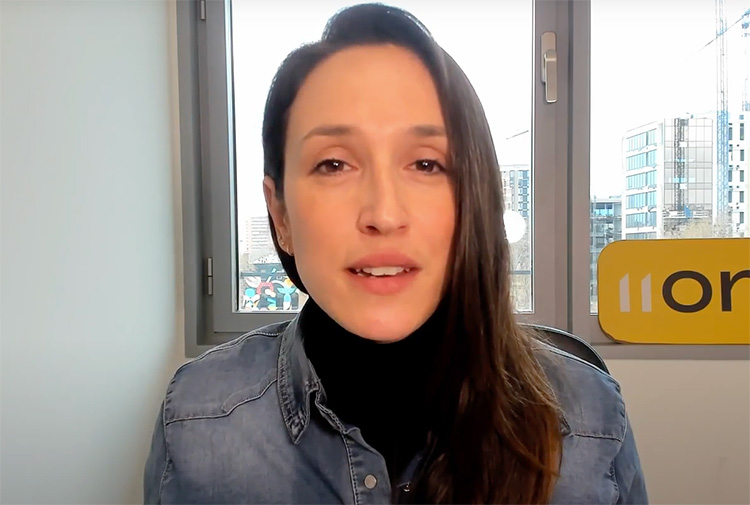
Podem canviar el món? Quina és la nostra capacitat real d’impacte sobre l’entorn que ens envolta? Lara de Castro, HR Business Partner d’11Onze, explica què és el consum conscient i com podem contribuir a la sostenibilitat del planeta amb les nostres decisions de compra quotidianes.
Sovint subestimem l’impacte que els nostres actes individuals tenen sobre l’entorn que ens envolta. Però totes les accions, per petites que siguin, contribueixen a modelar el món. Lara de Castro ho deixa clar al següent vídeo amb un exemple molt evident.
Com ella mateixa adverteix, hi ha moltes persones que pensen que un acte individual sovint “és massa feble” per a tenir un impacte significatiu en l’entorn, “però no és així”. Cada acció compta i té conseqüències que es poden acumular a les de la resta de la comunitat. La realitat és que “les nostres decisions més quotidianes són rellevants, per petites que siguin”. En aquest sentit, és molt evident el paper que juguen totes les decisions de compra si som consumidors conscients.
Consumidors conscients que poden canviar el món
Què és el consum conscient?
Els consumidors conscients són persones que escullen els productes i els serveis amb criteris que van “més enllà de la relació qualitat-preu”, ja que inclouen l’impacte ambiental i social com un element decisori en els seus hàbits de compra. Una conseqüència és l’aposta pel comerç de proximitat, que “és una manera de donar suport als productors locals i evitar l’impacte econòmic i ambiental del transport”, com explica Lara de Castro.
Un altre exemple de consum conscient el trobem en l’aigua. Si volem reduir la contaminació al planeta, podem substituir el consum d’aigua embotellada, “amb totes les conseqüències que sabem que té el plàstic”, per aigua de l’aixeta tractada amb filtres sostenibles.
Com indica Lara de Castro al final del vídeo, si tots som més conscients “en els petits detalls de la vida quotidiana” la realitat és que “sí que podem canviar el món”. La decisió és nostra.
Si vols descobrir com beure la millor aigua, estalviar diners i ajudar al planeta, entra a Imprescindibles 11Onze.
According to the World Gold Council (WGC), gold has broken 8 price records in September. In its latest report, it points to continuous increases derived from the geopolitical situation and, above all, from the movements of central banks.
It seemed that gold had risen abruptly in August due to the sudden fall of the stock markets. And, if anyone expected strong corrections in the price of physical gold, everything indicates that they will have to wait a long time. Gold continues to position itself as the safe haven par excellence in an environment of instability that continues and that has no prospects of changing in the short term.
All this has caused gold to close the month of September with a rise of 4.6%, reaching $2,630 per ounce. Gold has currently undergone a correction that has brought it to around 77 euros per gram, which in any case means an appreciation of more than 35% in one year. Some analysts attribute this slight correction to doubts about the Chinese economy and disappointment over the meager fiscal stimulus policy announced by its government.
The reason for the rise
In its latest report, the World Gold Council points to geopolitical tensions in the Middle East and the aggressive rate cuts by the Federal Reserve as the main reasons for the unstoppable rise in gold. It also points to a scenario of instability for stocks and bonds, which would attract investors to gold, knowing that it is an asset that appreciates in these situations.
The question, therefore, poses a moral dilemma: would a possible resolution of the current armed conflicts cause the fall of gold? Well, according to economist Gustavo Martínez, the answer is clear: no. Gold would continue to be at high prices due to the need of central banks to protect themselves against economic uncertainties due to the volume of debt. There is also another issue that is pushing gold, the fact that ETFs based on physical gold have become popular. The ease and speed of buying and selling ETFs facilitates and multiplies operations, but requires the accumulation of physical gold so as not to become a bubble without support.
Preciosos 11Onze
11Onze has been offering physical gold to its community since February 2022. From the beginning, it was pointed out that an environment of inflation, debt crisis and geopolitical risk would make gold a safe haven. We said then that it was necessary to protect savings, as central banks would do, by buying physical gold. Since then, gold has appreciated by more than 50%.
Your money is precious to you. And they are also precious to us.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.


Es consideren dipòsits de valor aquells actius, divises i mercaderies que no es devaluen amb el temps. L’or i altres metalls preciosos han estat històricament els dipòsits de valor per excel·lència, mentre que en les últimes dècades s’han fet evidents les grans deficiències de les monedes fiduciàries.
Com indica la Investopedia, “un dipòsit de valor és essencialment un actiu, mercaderia o divisa que pot guardar-se, recuperar-se i intercanviar-se en el futur sense que es deteriori el seu valor” quan l’intercanviem per productes o serveis: si avui equival a deu pomes, passat un temps haurem de poder intercanviar-lo per, com a mínim, deu pomes també.
L’or i altres metalls preciosos han estat considerats al llarg de la història els dipòsits de valor per antonomàsia perquè la seva vida útil és pràcticament il·limitada. I, si comprovem l’evolució del preu de l’or en les últimes dècades, veurem que una unça ha passat de cotitzar per sota dels 300 dòlars quan va entrar en circulació l’euro l’any 2002 a superar els 1.900 dòlars en l’actualitat.
En l’altre extrem, productes peribles com les pomes són pèssims dipòsits de valor perquè en pocs dies es descomponen i perden tot el seu valor. Tot i que determinats productes bàsics com els aliments poden pujar de preu temporalment en funció de la situació del mercat, el seu caràcter perible impedeix considerar-los dipòsits de valor.
Els diners moderns suspenen com a dipòsit de valor
Òbviament, l’euro i la resta de les monedes fiduciàries són dipòsits de valor molt deficients perquè no es revaloren al mateix ritme que els productes i serveis que permeten adquirir. Encara que les nostres monedes haurien de ser un dipòsit de valor raonablement estable, la inflació fa que el cafè que fa uns anys compràvem en un bar per un euro avui dia ens costi bastant més. Els nostres diners es deprecien dia rere dia.
Richard Nixon va posar fi al patró or l’any 1971, que fins llavors obligava als països del Fons Monetari Internacional (FMI) a mantenir un tipus de canvi fix respecte al dòlar i a la Reserva Federal dels Estats Units a recolzar la seva divisa amb or. Des de llavors, utilitzem monedes fiduciàries, és a dir, monedes que són de curs legal però que no estan recolzades per cap bé valuós. Tots els bancs centrals poden fabricar diners segons la seva conveniència i el seu únic aval és la confiança dels ciutadans.
Com és lògic, si la quantitat de diners en circulació augmenta a un ritme més elevat que els béns i serveis que es poden adquirir amb ells, el desequilibri entre l’oferta i la demanda fa que s’apugin els preus. Per tant, els nostres diners es devaluen.
Una moneda raonablement estable és essencial per a la salut de l’economia. Una unitat monetària que funciona malament com a dipòsit de valor desincentiva l’estalvi i dificulta el comerç. Els seus efectes nefastos són evidents si donem un cop d’ull als casos d’hiperinflació que han viscut alguns països al llarg de la història.
Els metalls preciosos com a valor refugi
Al llarg de més de dos mil·lennis, moltes economies han utilitzat l’or i altres metalls preciosos com a moneda de canvi per la seva durabilitat, relativa escassetat i fàcil transport. A més, en les últimes dècades l’or ha tingut un paper important com a valor refugi. La seva demanda ha tendit a disparar-se en moments d’incertesa econòmica, com demostren les dades de l’any passat, el de major demanda des de 2011. La llarga experiència amb l’or permet avalar la seva capacitat per exercir com a dipòsit de valor a llarg termini.
En general, altres actius com els béns immobles, les obres d’art, les antiguitats o alguns objectes de col·lecció també han demostrat que poden tenir aquest rol. Tot i que el seu valor pot caure en moments puntuals, tendeixen a revaloritzar-se a llarg termini gràcies a una demanda més o menys constant i una oferta molt limitada.
El seu gran inconvenient respecte a l’or és que es tracta d’actius molt poc líquids: és difícil vendre’ls de manera immediata si volem fer-ho per un preu raonable. A més, aquests mercats exigeixen un bon coneixement i es ressenten especialment en les crisis econòmiques, quan més es tendeix a recórrer als dipòsits de valor.
I els criptoactius?
Més difícil és valorar si els criptoactius arribaran a considerar-se algun dia com a dipòsits de valor, ja que són massa recents. És cert que el bitcoin es basa en el principi d’escassetat, una característica pròpia dels dipòsits de valor: cada any es genera un número limitat de bitcoins i existeix un topall predeterminat. No obstant això, com tants altres criptoactius, el seu gran inconvenient és que manca d’un valor intrínsec. Gairebé tot el seu valor és ara com ara subjectiu, la qual cosa és terreny adobat per a la volatilitat.
Això sí, en la mesura que el bitcoin sigui acceptat de manera massiva com a mitjà de pagament i s’empri en un nombre creixent de transaccions, el seu valor s’enfortirà i augmentaran les probabilitats que arribi a ser un dipòsit de valor a llarg termini, més enllà de volatilitats puntuals.
Si vols descobrir la millor opció per protegir els teus estalvis, entra a Preciosos 11Onze. T’ajudarem a comprar al millor preu el valor refugi per excel·lència: l’or físic.
With inflation continuing to rise, gold’s resilience throughout history as a store of safe-haven investment value cannot be underestimated. Even so, it is not the only precious metal in which we can invest our savings; silver, platinum or palladium can be good alternatives. But which metals offer the best returns?
The ability of precious metals to maintain much of their value during crisis periods, and to offer inflation protection based on their intrinsic value, makes them a must-buy if we want to diversify and make our savings more profitable. However, there are differences in the returns offered by different metals. In this analysis we do not make forecasts for the future, we simply focus on the evolution of the prices of these four assets: gold, silver, platinum, and palladium, over the last year and the last three years, so that we can easily see which have been the most profitable.
Performance over the last three years
The combined historical performance of the metals over the last three years is very positive, and attributable to the global pandemic, which caused a shortage of resources in the industry, rising inflation and unstable markets.
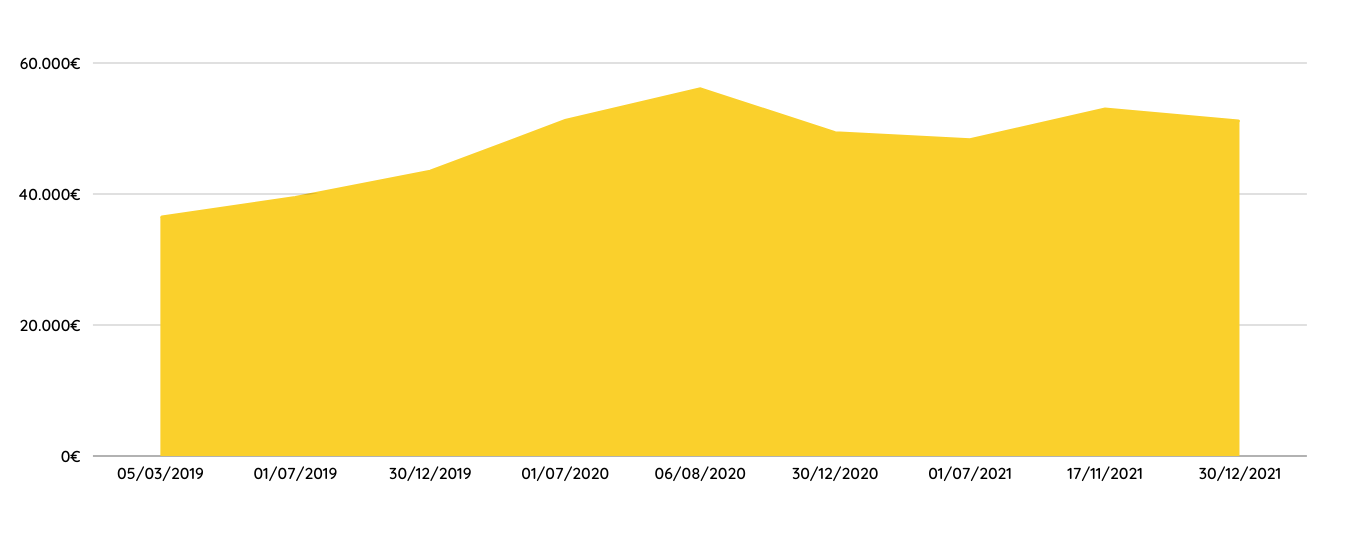
Gold and silver have experienced growth of over 40% in the face of the economic uncertainty caused by the pandemic, and are consolidating their position as safe-havens in the event of a crisis. Even so, it should be kept in mind that investors tend to increase their exposure to gold and silver when interest rates are low and inflation high in order to protect the value of their money, and in the absence of interest payments. A situation that can be reversed if inflation turns out to be transitory and interest rates rise.
The continued demand for platinum keeps its value on an upward trend with almost 27% appreciation, but palladium is growing at a spectacular rate of 75%, as it is a scarce metal in high demand by industry. Even taking into account its progression, it is not highly recommended for long-term investment due to its price volatility, and the fact that the trend towards electrification of the automobile industry means that the demand for catalysts is likely to decrease.
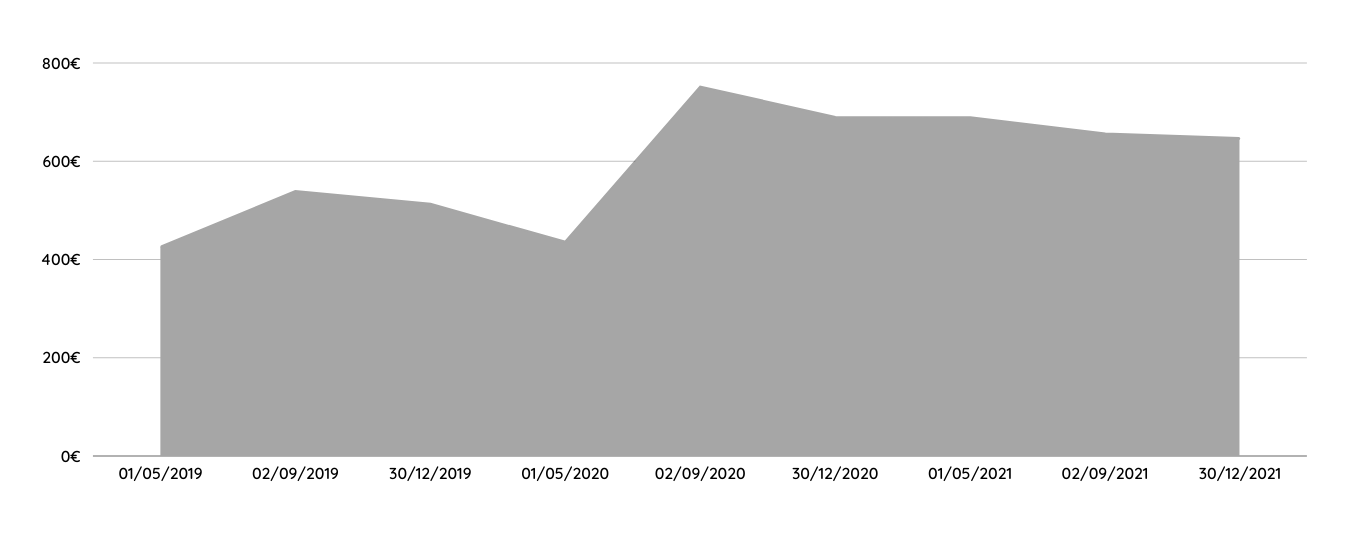
If we look at the following graph of the price evolution over the last three years, we see that gold has appreciated by more than 40% and silver by almost 47%. If we take into account that inflation in Spain in 2021 rose to 6.55%, we can affirm that people who bought gold and silver more than avoided the devaluation of savings suffered by people who had euros in their current accounts.
Evolution of the last year
During 2021, the fluctuation of the prices of precious metals has been different. All metals, except silver, recorded a positive, albeit moderate, price increase. Gold is the most stable of the metals, with price rises and falls always tending towards stability, but during the first quarter of the year, it suffered a loss in value. A fall in price linked to the economic stimulus of 1.9 billion dollars by the Biden administration, which would be repeated every time the US government announced a new package of measures to combat the pandemic, but still ending the year in positive territory.
Despite silver‘s upward trend at the start of 2021, it recorded a significant drop in price at year-end, contrary to predictions, because of declining industrial demand. While platinum and palladium prices also initially plummeted due to weak demand for autocatalysts, thanks to falling sales, platinum stabilised and ended the year in positive, and palladium ended the year on the unstoppable growth trend seen in previous years.
Whether we decide to invest in one metal or another, we must bear in mind that historical performance is not indicative of future performance and that any purchase involves a certain risk of loss of value. A risk that we assume whether we buy precious metals or not, because the value of the money we have in the bank depends directly on the decisions of the powers that be to print more currency (devaluing the currency in circulation) or not.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
La taxa anual equivalent o TAE és un índex en forma de percentatge anual que s’aplica a tots els tipus de préstecs. Representa el cost real i efectiu d’un préstec, ja que es tenen en compte tots els costos associats a la contractació. T’expliquem com es calcula.
Si vols comparar hipoteques o qualsevol mena de préstec és imprescindible saber què és la taxa anual equivalent o TAE. A l’Estat espanyol és obligatori que aquest indicador figuri a la publicitat i documentació dels productes financers que facin referència a un préstec. Això t’ajudarà a comparar el cost real de dos préstecs o més en un termini concret.
Els diversos préstecs que pots trobar al mercat de productes financers porten associats dos tipus d’interès, el TIN i la TAE, sobre els quals les entitats financeres tenen l’obligació legal d’informar els clients, prèviament a la contractació d’un crèdit. Encara que estan estretament relacionats, presenten importants diferències que cal conèixer per saber el cost efectiu d’un préstec.
Diferències entre el TIN i la TAE
El TIN o tipus d’interès nominal és un percentatge fix que el banc estableix per la prestació de diners i que representa la suma de l’euríbor més el diferencial aplicat. És a dir, es tracta de la quantitat que cal abonar a l’entitat financera a canvi del capital prestat. Aquest cost pot variar en funció de l’import del préstec, el termini d’amortització i el nostre perfil econòmic. Tanmateix, el TIN no inclou les despeses associades a la hipoteca i, a diferència de la TAE, el càlcul no ha de ser anual obligatòriament.
La TAE té en compte tots els costos associats a la contractació, per tant, inclou el TIN i qualsevol comissió relacionada amb el préstec, com ara la comissió d’obertura, les despeses d’operació que assumeix el consumidor i la freqüència de pagaments. Això no obstant, cal tenir present que a la TAE no s’inclou el cost d’alguns conceptes, com les despeses de notari o les primes de les assegurances i altres productes vinculats a l’operació.
Així mateix, és important recordar que en el cas de préstecs a tipus d’interès variable no és possible determinar-ne l’evolució futura, per tant, el càlcul de la TAE és orientatiu. En tot cas, es tracta de l’indicador més fiable a l’hora de determinar el cost real d’un préstec, més enllà de la tècnica comercial que hi ha al darrere del TIN anunciat a la capçalera de les ofertes i promocions presentades per les entitats financeres.
Com fer el càlcul de la TAE
L’interès de la TAE es calcula amb una fórmula matemàtica (TAE = (1 + TIN/f)f – 1) que té en compte quatre factors: la quantitat del préstec; el TIN; els terminis de pagament; i totes les despeses relacionades amb el préstec. Pots utilitzar alguna de les calculadores de TAE que pots trobar a internet, com aquesta de l’OCU, o introduir les dades en el simulador de préstec hipotecari o personal que ofereix la web del Banc d’Espanya.
Recorda que abans de fer qualsevol simulació, cal tenir aquestes dades per obtenir el percentatge més realista possible: capital inicial, TIN, despeses de constitució i periòdiques de la hipoteca, depeses de notaria, gestoria i del registre de la propietat. La periodicitat de la devolució, és a dir, si pagaràs quotes mensuals, trimestrals, etc. Així com el termini d’amortització de la hipoteca.
Si vols descobrir la millor opció per protegir els teus estalvis, entra a Preciosos 11Onze o dona un cop d’ull als productes que 11Onze Recomana en el nostre Marketplace.
Spain is the second country in the European Union where its population has the most money saved without remuneration. A large part of Spaniards’ savings is in current accounts and deposits that give very low returns that do not compensate for inflation. Are we investing too little and poorly?
Families have drawn on the almost 270,000 million euros saved during the worst phases of the pandemic to sustain spending in the face of the sharp price rises of the last two years. Even so, the gradual reopening of the economy and the rising cost of living have caused a large part of this accumulated savings pool to evaporate.
Even so, after the erosion suffered in 2022, the household savings rate has been recovering. It stood at 6.2% of their gross disposable income in the first quarter of the year, an increase of 83% compared with the same period a year ago. If seasonal and calendar effects are removed, it is equivalent to 14.2% of their disposable income, 1.2 points higher than in the previous quarter and the highest since the third quarter of 2021, according to the latest data published by the National Statistics Institute (INE).
In total, this is an increase to 14,119 million euros, while investment remained at 14,200 million euros, 1.3% less than the previous year. On the other hand, a financing requirement of 773 million euros was recorded, compared with an estimated financing requirement of 7,312 million euros for the same quarter of 2023.
Low-yielding financial instruments
Fixed-term deposits (38%), direct investment (32%), investment funds (15%) and Treasury bills and variable-term bonds, among others (11%), are the main options chosen by households seeking to make their savings profitable and protect themselves from the general increase in costs. The problem is that many of these options offer low returns that do not compensate for inflation.
Therefore, even though as a percentage of GDP, net financial assets represent 144.7%, a ratio 3.4 points higher than in the previous year, many people do not want or do not know how to generate wealth with their savings, which are being consumed by high inflation.
In Spain, there is almost a trillion euros in current accounts or cash, without remuneration and that even, in some cases, entails maintenance costs. Rodrigo Buenaventura, president of the National Securities Market Commission (CNMV), pointed out two months ago in an appearance at the Congress of Deputies, “Our citizens invest their savings in a way that can be manifestly improved”.
How to increase the return on savings
As a general rule, investments that offer high returns come with high risk, while low-risk investments offer more stable, but potentially lower, returns. However, at 11Onze we have shown that this does not always have to be the case.
Saving with 11Onze is always based on one maxim: they have to be safe propositions. That is why we have made a firm commitment to gold, because of its historic role as a store of value. We offer you gold bars in two formats: Gold Patrimony and Gold Seed. Bearing in mind that gold has doubled in value in the last five years and that its price rose by 15% in 2023, it has established itself as an excellent option for dealing with inflation.
Social justice does not have to be at odds with generating returns on your savings. Thanks to Litigation Funding, you can help others who have been abused by banks or the government while earning returns of between 9% and 11% on your money.
It is a product that has been structured exclusively for members of the 11Onze community, offering two ways to participate: an option that returns your capital and possible profits after one year, or another option in which your capital works for a few years and provides you with a monthly return in six months.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.


Since the beginning of 11Onze, we have been informing our community that gold is a great tool to protect savings and that its price would continue to rise. Time has proven us right. In the last five years, it has experienced a spectacular increase in value, doubling its price and reaffirming itself as the most valuable asset on the market.
The price of gold has consolidated above 2,150 euros per ounce after the third consecutive month of upward movement, despite the slight drop in price in mid-May. The strength of its price during the first five months of the year has been caused by strong demand from central banks in emerging economies due to geopolitical tensions and persistent inflation.
Since the beginning of the year, gold has risen 17%, following the upward trend of 2023 when, although it experienced some fluctuations during the year, it rose 15% on the back of the US banking crisis, geopolitical tensions, military conflicts and the US Federal Reserve’s monetary policy.
John Reade, chief market strategist for Europe and Asia at the World Gold Council, noted a month ago that gold prices have experienced a remarkable rally, doubling over the past five years since 2019. What’s more, Reade pointed out that the gold metal’s price performance has been largely independent of that of the US dollar, which is usually one of the biggest drivers of gold prices.
Gold Patrimony, an excellent product to protect your savings.
Developing economies lead the way
The WGC analyst explained that emerging markets, particularly India and China, already account for half of the global gold market share after experiencing an increase in production and trade in the precious metal. Furthermore, he expects the price of gold to rise substantially soon, citing continued buying by central banks as the main driver behind the upward trend.
‘We urge investors to incorporate gold into their financial and investment portfolios and to seek diversification. Gold not only diversifies, but also stabilises financial portfolios. Moreover, any reduction in US interest rates is likely to have a favourable impact on gold prices,’ Reade advised.
Other analysts, such as those at Bank of America, expect the rally to continue and believe that a price of 3,000 dollars per ounce is possible by the end of the year. Economic uncertainty, expansionary monetary policies, inflation, and currency devaluation continue to be as relevant today as they were a few months ago and could continue to drive the price of gold in the near future.
Preciosos 11Onze makes it easy to buy gold, at the best price and with total security. Give us a call and speak to one of our agents without any obligation to clarify any doubts you may have and protect yourself from economic crises with the ultimate safe-haven asset: gold. If you want your savings to keep or increase their value, Gold Patrimony.


Actualment, hi ha 238 mines d’or actives repartides en 36 països a tots els continents, excepte l’Antàrtida, sovint en zones remotes i empobrides. Un informe del World Gold Council mostra que l’explotació responsable de l’or contribueix en gran part al desenvolupament econòmic i social de moltes comunitats locals.
L’or ha estat un metall preciós únic, amb un gran valor emocional, cultural i financer al llarg de la història. A més, l’or té cada vegada més aplicacions tecnològiques, que el porten a ser present en telèfons mòbils, kits de proves mèdiques o coixins de seguretat per a vehicles.
Però els recursos aurífers també són una font essencial d’oportunitats en molts països en desenvolupament. Com indica un informe del World Gold Council, les explotacions d’or responsables generen nombrosos llocs de treball, faciliten la construcció d’infraestructures i contribueixen al desenvolupament de les comunitats locals, a més d’aportar abundants ingressos a través d’impostos i cànons.
Ocupació ben remunerada
L’anàlisi de les operacions de les 29 empreses membres del World Gold Council mostra que el 2023 van aportar un total de 57.520 milions d’euros a les economies dels seus països, donant suport a 212.000 llocs de feina directes i a 163.000 empreses. A més, cada lloc de treball en la indústria de l’or també genera unes altres sis ocupacions indirectes en la cadena de subministrament o gairebé deu més si s’inclouen les ocupacions derivades.
Els treballadors de la indústria de l’or estan ben remunerats, amb una mitjana sis vegades superior al salari mitjà nacional. I cal tenir en compte que gràcies als recents esforços de les empreses per formar i desenvolupar les competències locals, el 95% dels empleats procedeixen del país on està situada la mina. El percentatge d’expatriats s’ha reduït a la meitat en els últims vuit anys.
Desenvolupament de les comunitats locals
Les empreses del sector reconeixen els beneficis mutus d’integrar-se el més possible en l’economia local, recorrent a la població i a les cadenes de subministrament autòctones. Això dona suport a la seva “llicència per operar” i permet a la comunitat beneficiar-se del desenvolupament econòmic i social de la mina.
De fet, operar en un enclavament aïllat d’esquena a la comunitat local ja no és una opció viable per a cap empresa minera. Per tenir èxit, han de generar beneficis sostenibles per a la població local, especialment en els llocs més pobres i remots, on sovint hi ha poques vies alternatives per a l’activitat econòmica i el progrés de la comunitat.
Això ha suposat que l’any 2023 les empreses que integren el World Gold Council gastessin més de 620 milions d’euros en inversió comunitària, un increment de 77 milions respecte a l’any anterior. A més de cobrir les necessitats d’una mina d’or, és evident que les inversions en carreteres, subministrament d’aigua i electricitat suposen un benefici a llarg termini per a les empreses i comunitats de la zona.
A aquest import s’hi sumen gairebé 8.000 milions d’euros pagats en impostos i regalies, que reverteixen en la millora dels serveis públics, l’educació, la sanitat i les infraestructures dels països on es troben les mines. En molts països en desenvolupament, aquests tributs constitueixen una proporció notable de la base impositiva nacional i fan possible que es beneficiïn tant les zones mineres com les no mineres.
Una aportació considerable al PIB
En total, s’estima que l’aportació d’aquestes empreses al PIB dels 36 països on operen va ascendir a prop de 57.000 milions d’euros. Per cada euro de producció d’or, almenys 63 cèntims van acabar com a salaris, impostos o ingressos per als propietaris d’empreses locals.
Tot i que històricament les operacions mineres no sempre han conduït a millores en el desenvolupament humà i social de les comunitats locals, cada vegada més es tendeix a aplicar estrictes protocols mediambientals, de governança i socials com a condició per a operar. Per això, la indústria de l’or s’està convertint en un important motor econòmic i social per a molts països de tot el món.
Si vols descobrir la millor opció per protegir els teus estalvis, entra a Preciosos 11Onze. T’ajudarem a comprar al millor preu el valor refugi per excel·lència: l’or físic.