Rising prices and the cost of living
We close a year in which the general rise in prices has made it difficult for many families to make ends meet. How will the economy evolve in 2023? What can we do to adjust the family budget? We talk about it with Xavi Viñolas, Editor of 11Onze and Gemma Vallet, Director of 11Onze District, in a new episode of La Plaça, Territori 17’s radio show.
With a year-on-year inflation rate of 8.4%, 2022 has been disastrous for many families who have seen their purchasing power fall to unsustainable levels. Runaway price rises have pushed up the cost of living at a time when many households were just recovering from the shock of the pandemic. What lies ahead for 2023?
This year, we will see whether central banks can halt the rise in prices without neutering the recovery of economies. Financial analysts predict that inflation will fall to 5%, but as Viñolas points out, “in a context of uncertainty and high economic volatility, we have to take any economic forecast with a grain of salt, the same experts told us that current inflation would only last a few months”.
La Plaça – Territori 17: Cost of living
Proactivity in reducing expenses
Now, more than ever, it is necessary to have a piggy bank for possible unforeseen events. But, faced with an economic context that does not favour saving and where our money has lost a good part of its value, it is not easy to reduce our monthly expenses in order to save.
The editor of 11Onze suggests we be proactive and look at reducing some fixed expenses, which are not always difficult to cut. Services contracted on a permanent basis, such as home or car insurance, can be renegotiated, or we can simply switch to a provider that offers a policy without permanence and more suited to our needs, which can be much cheaper.
Likewise, suppliers of utilities, such as electricity, can give us some room for manoeuvre, changing the contracted power or switching from the free market to the regulated market. Modifying the contract or looking for more reasonable offers can mean considerable savings and help us to balance the budget at the end of the month.
If you want to discover fair insurance for your home and for society, check 11Onze Segurs.
2026 will not arrive with a sudden major crisis, nor with a new economic golden age. There will be no great collapse that blows everything apart, nor a comfortable return to the stability of the past. It will arrive with a much more uncomfortable feeling: the realization that the old order no longer works, but the new one is not yet defined. A kind of economic no man’s land in which the old rules have lost effectiveness and the new ones do not yet offer security.
Technology, markets, energy, and money will continue to set the global agenda, but under a different logic. It is no longer so much about growing faster as it is about resisting better. It is no longer so much about optimizing as about protecting oneself. And this shift in priorities will profoundly shape the behaviour of states, companies, and, above all, savers.
The end of comfortable globalization
For almost three decades, the global economy operated like a great machine of permanent optimization. Production took place where it was cheapest, financing came from almost free money, and consumption occurred as if limits did not exist. Globalization promised infinite efficiency, stability, and sustained growth. It seemed that the system corrected itself.
But that model, as we knew it, will not return. Not because international trade will disappear, but because the conditions that made it possible have been exhausted. 2026 will consolidate a radically different scenario: a fragmented world, divided into economic blocs that will prioritize security, control, and political alignment over pure efficiency. It will not be the end of global trade, but it will be the end of a naive globalization based on blind trust and excessive dependence on third parties.
The consequences have already begun to become visible throughout 2025. Shorter and less flexible supply chains. Relocated or regionalized production. Structurally higher costs and an increasingly reduced margin for error for companies and governments. The old “just in time” model gives way to a much more defensive logic: just in case.
All of this feeds an inflation that is less explosive than in 2022, but far more persistent and difficult to combat. An inflation that no longer responds only to isolated shocks, but to deep changes in the way the global economy functions. For this reason, the lesson is clear: the world that is coming will be less efficient… and inevitably more expensive.
Productivity for some, dependence for many
Technology will continue to be a key driver of the economy in 2026, but the optimistic narrative that has accompanied it for years is beginning to crack. Artificial intelligence, automation, and mass digitalization are no longer presented only as tools of progress, but as vectors of power. And power, when it accumulates, is rarely distributed equitably.
These technologies are not neutral. They redistribute productive capacity, but also control. Some companies will be able to multiply their efficiency with fewer workers, lower costs, and higher margins. Platforms, large corporations, and actors with access to data and technological capital will further expand their competitive advantage over the rest of the economic fabric.
At the same time, many states will see technology as an opportunity to strengthen oversight over key economic flows: personal data, payment systems, energy consumption, or financial behavior. Digitalization enables agility, yes, but also total traceability. And when everything is measurable, everything is potentially controllable.
The less visible side of this process is the labour market. Millions of professionals—especially in qualified but repetitive jobs—will see their relative value diluted. Not because work disappears, but because the balance of power changes between those who offer labor and those who control technology. The promise of a more productive economy does not necessarily imply higher wages or greater stability.
Technological progress, on its own, does not guarantee collective well-being or shared prosperity. It guarantees competitive advantage. And, as always, that advantage rests in the hands of those who control infrastructure, data, and algorithms. The big question of 2026 is no longer how far technology can go, but who will decide the rules of the game.
Clear winners, silent losers
2026 will not be the year when “everything goes up.” Equities will continue to offer opportunities, but in a much more unequal and demanding environment than that of the past decade. Markets will no longer move driven by a general tide of optimism, but by selective currents that will benefit only certain sectors and very specific companies.
Interest rates are no longer zero. Capital has regained a cost, and that profoundly changes the rules of the game. Highly indebted business models, companies that have grown on expectations, and projects that were only viable with cheap financing will be exposed. The time of buying growth without looking at the balance sheet is over.
As for indices, the market may hold. But beneath the surface there will be a lot of rotation, a lot of selection, and quite a few disappointments. Companies that have been untouchable for years may enter a phase of silent correction, while others—more solid, more efficient, or better positioned—will attract capital discreetly.
Investing will no longer be about following a trend or replicating an index uncritically. It will be about understanding risks, distinguishing quality from noise, and accepting that not all investments are made for all profiles. Volatility does not disappear, but it changes form. The market ceases to be an automatic refuge and returns to what it should always have been: a tool. And like any powerful tool, it demands judgment, discipline, and risk awareness.
Between necessity and contradiction
Sustainability will continue to occupy a central place in the economic discourse of 2026. Governments, companies, and financial institutions will present it as an unquestionable priority. But as the narrative advances, the clash with reality becomes increasingly evident. The green transition is necessary, but it is neither fast nor painless.
Transforming the energy system requires massive investments, scarce resources, and, above all, time. And while this process unfolds, energy is more expensive. Raw materials are more expensive. And pressure on families and companies increases, especially in a context of weak growth and strained purchasing power.
Many projects labelled as green are only viable thanks to public support: subsidies, tax incentives, or favourable regulation. But when states carry chronic deficits and high levels of debt, financial sustainability inevitably comes into conflict with environmental sustainability. The margin to finance everything is not infinite.
In this context, capital begins to sharpen its focus. Investors are no longer satisfied with labels or well-intentioned narratives. Gradually, a line is drawn between projects with real impact and models that depend exclusively on public aid to survive. 2026 will thus mark a turning point: fewer green slogans and more scrutiny. Fewer generic promises and more uncomfortable questions. Capital will begin to separate real green from subsidized green.
The return of the physical world
After years of almost unlimited financing and believing that the economy could grow detached from the material world, 2026 confirms an often-forgotten obvious truth: the digital economy needs a physical base. Algorithms, platforms, and virtual services ultimately depend on energy, materials, and tangible resources.
Energy, precious metals, food, and natural resources return to the center of the economic stage. Not only because demand is growing, but because expanding supply is increasingly complex. New extractive projects require time, high investment, and must overcome growing regulatory and social obstacles.
This reality is compounded by a more tense environment: more environmental regulation, more geopolitical conflicts, and greater strategic dependencies between countries. Control of certain raw materials becomes a matter of national security, not just economic competitiveness.
The result is a market marked by volatility, but also by a structural value that gains weight in the medium and long term. Essential resources may experience price fluctuations, but they are unlikely to lose their relevance. The world can print money easily. What it cannot do is print energy, precious metals, or food.
Monetary policy: managing the limit, not controlling it
Central banks will continue trying to convey calm in 2026. They will do so with measured speeches, messages of control, and promises of stability. But reality is more uncomfortable: the room for manoeuvre is today much more limited than official rhetoric suggests.
After years of cheap money and massive monetary expansion, public debts have reached extremely high levels. In this context, raising interest rates has immediate fiscal costs and politically difficult consequences. But not doing so also has a price: it erodes purchasing power, fuels inflation, and undermines confidence in the currency.
Central banks thus operate in a narrow and contradiction-filled space. Any decision implies trade-offs. There are no clean solutions or painless exits. The result is a fragile balance, sustained more by narrative management than by real control of economic variables.
The idea of a “monetary normality” like that which existed before 2008 is no longer realistic. 2026 will not be a year of returning to the previous order, but of managing accumulated damage. Of containing tensions, postponing adjustments, and avoiding abrupt system ruptures. Confidence in fiat money does not vanish overnight. But it is not immutable either. It wears down slowly, decision by decision, year after year. And this silent erosion is one of the subterranean forces that will shape the economic landscape of the coming years.
The saver, facing a new mental scenario
Perhaps the major trend of 2026 is not strictly macroeconomic, but cultural. Beyond data, indices, and forecasts, more and more people are accepting an uncomfortable reality: stability is no longer guaranteed. Not for states, not for markets, not for families.
Saving is harder than ever. Inflation erodes the value of money, incomes do not always grow at the same pace, and the margin for error narrows. At the same time, delegating financial decisions carries risks that previously seemed invisible. And blindly trusting—in institutions, in products, or in reassuring narratives—no longer seems like a prudent option.
This change in context also brings about a change in mindset. The classic question of “how much can I earn?” loses centrality, and another, more fundamental one emerges: “what can I preserve?” It is not just about returns, but about resilience. About the ability to protect accumulated value in an environment full of noise, volatility, and uncertainty.
In this new scenario, preserving value ceases to be a conservative attitude and becomes an intelligent strategy. 2026 does not reward uncritical audacity so much as judgment, information, and risk awareness. The saver no longer seeks easy promises, but tools to navigate a world that has ceased to be predictable.
Perhaps 2026 will not be a spectacular year, but it will be a revealing one. It will reveal who has understood the paradigm shift and who still expects everything to return to how it was before. The economy enters a more mature, harsher, and less friendly phase. But also a more honest one. With fewer promises… and more individual responsibility.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
Val més que ens preparem per no caure en l’anomenada oniomania.
Quantes vegades has marxat d’una botiga amb un carro ple de coses que no necessites? Segons l’Associació Centre Català per les Addiccions Socials (ACENCAS), les compres per impuls han augmentat un 20% durant la pandèmia. Les compres per impuls són aquelles que es realitzen de forma espontània i són l’antitesi de les compres rutinàries. El disseny dels supermercats i els grans magatzems, les estratègies de màrqueting i la publicitat han excel·lit en l’art de parar-nos trampes perquè comprem, però els experts alerten que aquestes compres impulsives poden ocasionar problemes greus a l’economia domèstica.
Quan aquest impuls es converteix en obsessió, aleshores parlem d’oniomania o compra compulsiva, un terme que va ser emprat per primera vegada pel psiquiatre alemany Emil Kraepelin, i que descriu el desig irrefrenable de comprar. La compra compulsiva genera, tal com assenyalen els psiquiatres, una satisfacció immediata que ens omple de sentit i amb la qual aconseguim esborrar els problemes temporalment. Per això, les persones que compren de forma compulsiva fins al punt de considerar que tenen un trastorn, sovint amaguen els objectes que han comprat avergonyits i es mostren irascibles o deprimits. Aquest sentiment de culpa el compensen amb una nova compra. És un peix que es mossega la cua.
- No aneu mai a comprar amb la panxa buida. Ja ho hem apuntat unes línies més amunt: els supermercats i els grans magatzems estan organitzats amb una cura mil·limètrica per despertar tots els instints més baixos. Classifiquen els productes, estableixen relacions entre les marques, deixen l’espai necessari perquè observis les prestatgeries, il·luminen l’espai perquè centris la mirada en una direcció concreta, col·loquen els productes poc buscats prop de les caixes o deixen ben exposades les ofertes, entre molts altres trucs. Per això, un bon consell quan anem a comprar és fer-ho amb la panxa buida. Quan un té gana, és més fàcil que caigui en la temptació de comprar un desig.
- Porta la llista de la compra de casa. Una altra manera d’evitar les temptacions d’última hora és fer una llista a casa d’allò que necessites. Amb la llista a la mà, pots estar segur que no compres de més i, si ho fas, en seràs ben conscient.
- Evita les ofertes 2×1. Cal evitar tant com sigui possible totes aquelles ofertes que només ens fan anar a casa amb productes de més. Per què necessites tres raspalls de dents si vius sol? Si necessites una camisa, per què n’has de comprar dues? És important no deixar-se endur per la sensació que comprant ofertes estem estalviant, perquè no és veritat.
- Si les compres impulsives es tornen compulsives, consulta el metge. Si les compres et produeixen malestar, baixa autoestima, buit emocional o por, però no les pots evitar, potser és hora que parlis amb un metge. La psicoteràpia és necessària per superar aquest trastorn, sense la qual la compra compulsiva pot persistir tota una vida i, fins i tot, provocar la ruïna financera de la persona afectada i el seu entorn més pròxim.
11Onze és la fintech comunitària de Catalunya. Obre un compte descarregant la super app El Canut per Android o iOS. Uneix-te a la revolució!
Ice packs have been a luxury item this summer because many manufacturers could not make ends meet due to the price of the energy needed to make and preserve the ice cubes. Likewise, many SMEs are rethinking their production due to the rising cost of raw materials and energy.
A report by the employers’ organisation Cepyme in the first months of the year already highlighted the major impact that inflation was having on SMEs. Rising prices had considerably reduced the margins of almost half of SMEs, 15 % saw their viability compromised in the short term and another 15 % were forced to seek alternative financing.
Since then, the increase in the CPI has only worsened. Most SMEs have had to pass on to their prices the increase in production costs caused by higher raw material and energy prices. The problem is that turnover is not growing at the same rate as costs, and cash flow is increasingly strained. For example, in the first quarter of 2022, total costs rose by 23 %, while sales increased by only 19.8 %. As a result, it is becoming increasingly difficult to invest in innovation and human capital.
Over time, inflation is having an increasingly negative impact on consumption. As their purchasing power is eroded, consumers prioritise purchasing necessities and postpone other purchasing decisions.
Desperate measures
Adequate planning, crisis plans that include alternative suppliers and flexible organisation help to cope with this situation, but these elements are not always enough to stay afloat, especially if the feared stagflation scenario, which combines economic stagnation with high inflation, is confirmed in the coming months.
Moreover, SMEs may face a double threat in the coming months if business margins continue to shrink and pressure from trade unions to raise wages to compensate for the rise in CPI increases. As a result, some of them may find it more profitable to reduce activity to ensure their survival.
Cepyme has warned that “the rise in energy prices, coupled with the sharp increase in raw material prices, is undermining the production and operating capacity” of SMEs. For this reason, some are already restructuring their production plans or even considering partial or total temporary closures.
Industries most affected
In general, the sectors most affected are those that make intensive use of gas and electricity, such as metallurgy, iron and steel and paper. But others such as the agri-food and manufacturing industries are also implementing contingency plans to cope with rising costs. As it is the case with the hotel and catering industry, which is also suffering from staff shortages, with 16,000 fewer people affiliated to the Social Security than before the pandemic.
Most commonly, shifts or services are reduced in these industries to better adjust revenues and costs. In any case, this is bread for today and hunger for tomorrow if inflation does not abate.
11Onze is the community fintech of Catalonia. Open an account by downloading the super app El Canut for Android or iOS and join the revolution!
The final days of the year are unforgiving. For thousands of freelancers and small businesses, the year-end closing is a race against the clock in which any oversight can turn into an unexpected penalty, a costly tax adjustment, or a suffocating January.
Balancing the accounts, reviewing invoices, adjusting inventories, and anticipating expenses is not merely an administrative task: it is a protective operation, almost an act of self-defence in a tax environment that, all too often, works against small business owners.
Closing a financial year properly is a way to anticipate problems and reduce risks. In a system that frequently rewards bureaucracy more than productivity, control and foresight are the only real refuge. Careful planning strengthens the health of the business, minimizes the burden of administrative obligations, and avoids rushed decisions that only create more tension. Ultimately, it is about creating a roadmap that allows 2025 to be left behind calmly and 2026 to be approached from a far more prepared position.
One of the elements that sets the pace of this closing process is document management. Every December, many freelancers discover that the real issue is not the tax authority, but the disorder that has been accumulating for months.
A unissued invoice, a payment forgotten in an email thread, or an incorrectly recorded date can completely alter the taxable base for personal income tax or corporate tax, distort VAT, or artificially inflate cash flow. Reviewing all documentation is, admittedly, a thankless and tedious task; but it is also the only way to ensure that the accounting snapshot presented at year-end faithfully reflects the reality of the business.
Deductions and prepaid expenses
In this review process, there are tools that often go unnoticed. One of them is the possibility of deducting VAT on unpaid invoices once six months have passed since the invoice was issued, or only three months in the case of SMEs. This is a legal and protective measure that many businesses overlook and that can represent significant savings at a time of year when every euro counts. Knowing one’s tax rights is just as important as meeting one’s obligations.
Another smart year-end move is the prepayment of expenses. If 2025 is expected to be weaker, or if this year’s turnover has been higher than usual, advancing recurring expenses can be a very effective tax strategy. This includes domains, hosting, software, professional services, or office supplies that would have to be contracted anyway during the first months of the new financial year. It is not about spending for the sake of spending, but about optimizing the tax result and preventing the state from taking a share of income that will not be repeated. The calendar itself can be a tool for savings when used wisely.
The same reasoning applies to investments and depreciation. If you operate under the direct assessment regime and plan to renew IT equipment, machinery, furniture, or carry out improvements to your premises, waiting until March, may make little sense. Anything with a useful life of more than one year is depreciable, and any acquisition made before December 31 will begin generating depreciation in the current financial year. This is an intelligent way to smooth profits and avoid tax spikes that later become difficult to manage.
Moreover, investing in operational improvements has effects that do not appear in any tax report but are felt in everyday operations: higher productivity, less wasted time, and greater responsiveness. For many businesses, efficiency is not a luxury; it is a necessity to remain competitive.
The weak point of many inspections
One of the most sensitive, yet most frequently overlooked, areas is inventory. Tax authorities pay particular attention to stock valuation because this is where the most common accounting inconsistencies tend to be hidden. Inflated stock creates profits that do not exist; undervalued stock generates distrust and may be interpreted as an irregularity. This is why, at year-end, it is advisable to carry out a realistic valuation, remove defective materials, and ensure that physical inventory matches accounting records. It is a laborious task, but it is what separates peace of mind from a potential inspection.
Reviewing freelancers’ social security contributions is another essential exercise. Under the new contribution system based on real income, many professionals are paying either too much or too little. Underpaying leads to an upward adjustment; overpaying means having advanced money to Social Security unnecessarily. Spending a few minutes reviewing 2024 income, the applied bracket, and whether it is worth requesting a change — which will take effect in March — can result in annual savings of between €300 and €800. Few one-minute actions offer such a high return.
The same logic applies to withholdings and advance tax payments. Many professionals face an uncomfortable paradox: they either reach their income tax return with an unexpected tax hit, or they discover that they have been financing the state because the applied withholding rate was too high. Reviewing whether it makes sense to increase the rate from 7% to 15%, comparing income with withheld amounts, or making an additional advance payment if a significant adjustment is expected is a smart way to avoid surprises. Adjusting now is always better than regretting it in the spring.
There are also particularly sensitive areas, such as vehicle deductions. This is a field full of confusion, where many businesses make deductions that cannot be justified and are therefore prone to penalties. The tax authority is clear: only expenses that can be documented as having a 100% professional use are deductible. This requires usage logs, documentation consistent with the business activity, and maintenance and fuel invoices clearly linked to the business. Without this evidence, the deduction does not stand.
The art of avoiding unpleasant surprises
Grants and subsidies also require attention. They can be a relief for many businesses, but they can also become a trap if their conditions are not met. Most penalties do not arise from bad practice, but from oversights: incomplete justifications, unnoticed deadlines, or unmet requirements. Reviewing every detail, every condition, and every document is essential. There is no such thing as a cheap subsidy if it later has to be repaid with interest.
And after all this, the most important element still remains: cash flow. It is the lifeblood of the business and what allows it to survive the toughest months of the tax calendar. Year-end is the time to analyze the cash cycle, calculate whether there is enough buffer to face the first-quarter tax wall — combining VAT, income tax, and contributions — and identify clients who consistently pay late. Without liquidity, no tax strategy can compensate for a suffocating January.
Finally, no business should enter 2025 without a compass. Defining revenue targets, adjusting pricing strategy, planning investments, and establishing a minimum cash reserve is the way to face the year with control rather than improvisation. Without a map, 2025 will run you over; with a map, you set the pace.
A system that forces constant balancing
All of this takes place in a context that offers little support. Freelancers and SMEs sustain a large part of the country’s economic fabric, yet they continue to bear a disproportionate fiscal and administrative burden. The state keeps breaking tax collection records, while middle incomes suffer the most. The system is not designed to make life easier for small business owners, but to collect revenue.
For this reason, carrying out an impeccable year-end closing is not an option but a survival strategy. Preparing, anticipating, and acting is the best way to protect the business in an environment that does not forgive mistakes.
11Onze is the community fintech of Catalonia. Open an account by downloading the app El Canut for Android or iOS and join the revolution!

Christmas, sales, the beginning of January… saving during these holidays marked by consumerism seems impossible, but at 11Onze we give you a few tips to make the impossible possible. Start the year with good economic planning!
Between the gifts we give to those closest to us, those we give out of commitment, meals out and everything we buy to make them at home, all add up to a figure that is often higher than we would like. Has it ever happened to you that you start the month with a very clear amount to save and, at the end, you see that the expenses have eaten up all the savings? It has happened to all of us at some time or another, and even though we know that the evil of many is no consolation, what we will do is remedy the situation and give you tips so that you can control your expenses during the festive season.
A precariously balanced scales
Balance the scales between what you want to spend and what you can spend. It sounds so basic, but when it comes down to it, how many of us budget our personal finances? As you know, the number one rule of saving is to define income and expenses. In the income section we will write down the money that comes into the account, and in the expenses section we will write down everything that, whether we have to pay every month or not, the fixed costs, such as rent, insurance or school.
The remaining amount is what you can spend and save. We recommend you to define first of all the amount to save, and leave the rest for expenses. If you know that, due to holidays, summer holidays or birthday celebrations, your budget is inevitably going out of control, a tip could be to set aside a certain amount each month to cover these extraordinary expenses. Like a piggy bank, designed so that you can use it when you need it.
What do we spend the most money on?
For the holidays, there are two cracks through which our savings slip: meals and gifts. In the first case, this year’s Covid restrictions prevent us from having face-to-face meetings, so financially it can benefit us. In the case of going out, it is advisable to compare several restaurants and prices, as on special days the price tends to shoot up. A trick to control spending is to previously define the maximum amount we want to spend. This way, we won’t blow the budget.
As for meals at home, one solution for not taking on the whole cost can be to share it out. We all like to be the hosts and to be able to invite our colleagues, but we must bear in mind that, depending on the meal, the cost may be higher than expected. Splitting the menu or costs at the end of the meal can be a way to enjoy our family and friends without affecting our finances. On the other hand, we know that gifts are the main expense during the Christmas and Epiphany festivities, and that is why we have compiled a list of ten tips for organising your shopping.
The bargain trap
How many times have we bought products that we hadn’t even planned to buy simply because the offer was unrepeatable? An offer alerts us that the product is within our reach: it’s now or never. And, obviously, we end up buying it thinking about the money we save compared to the original price.
But the main question to ask ourselves is whether we were willing to buy it for the original price. Do we really need it? Will we use it? Letting ourselves be carried away by this false sense of savings only generates an additional expense that we were not counting on. When faced with offers, let’s not let our guard down and let’s reflect both on the use we will make of the product and on the price we are paying. And everything that is secondary and does not fall within the monthly budget, can wait until next month, so get ahead of your expenses and take control of your economy!
11Onze is becoming a phenomenon as the first Fintech community in Catalonia. Now, it releases the first version of El Canut, the super app of 11Onze, for Android and Apple. El Canut, the first universal account can be opened in Catalan territory.
A 11Onze volem que la gent es formi per empoderar-se econòmicament. Pots començar-ho a fer amb la sèrie El Diner.
El diner és una sèrie d’animació que podeu trobar a la Plaça, amb l’objectiu d’explicar de manera amena i molt senzilla el món de l’economia. La sèrie consta de nou capítols amb lliçons com “Història de la moneda”, “La creació monetària” o “La concentració de la riquesa”. En finalitzar cada capítol trobem un qüestionari per saber si n’hem entès els conceptes. Però, quina és la definició del diner? I de l’economia?
El diner és el cor de la nostra economia: és l’eina que ens facilita l’intercanvi de béns (el menjar que comprem, una casa, un ordinador o una bicicleta) i serveis (el temps que paguem pel temps que algú ha dedicat a fer alguna una cosa: un metge, una advocada, una mestra d’escola, un mecànic…) a través d’una moneda.
Aquesta moneda acostuma a tenir forma de moneda central material (en forma de bitllet i de monedes, els diners que podem tocar i portar a la cartera), anomenada també moneda manual, líquida o efectiu. Aquestes monedes són fabricades al Banc Central Europeu (BCE), a banda d’afavorir que l’economia funcioni.
L’altra moneda amb la qual podem pagar els béns i serveis és la moneda escriptural o secundària, és a dir, els números del nostre compte corrent, que no existeixen físicament i que tan sols existeixen dintre del sistema informàtic de la comptabilitat del banc. Aquests diners són gestionats pels bancs comercials privats, els que treballen directament amb la ciutadania i que trobem a la nostra ciutat o al nostre barri. Són els que distribueixen les monedes i els bitllets que crea el BCE.
Satisfer l’oferta i la demanda
Si mirem la lliçó “Aprèn a avaluar l’economia”, de l’apartat Aprendre de la Plaça, també entendrem per què l’economia és un sistema de distribució i de gestió dels recursos limitats per satisfer la demanda de les persones.
Però el terme economia va més enllà, ja que tots contribuïm a fer-la possible. Els nostres actes s’hi reflecteixen: en allò que consumim, les hores que treballem, els béns que posseïm, els diners que podem arribar a estalviar. La suma dels actes que prenem individualment tota la ciutadania és el destí de l’economia global. Dit d’una altra manera: l’economia és el resultat del que nosaltres decidim.
Esperem que amb aquesta petita introducció de la sèrie El Diner, i del resum dels seus conceptes, us hagin vingut ganes d’aprendre sobre economia i sobre el món de les finances. Ja ho diuen: “A la vida, unes vegades es guanya, i d’altres s’aprèn”.
11Onze és la fintech comunitària de Catalunya. Obre un compte descarregant l’app El Canut per Android o iOS. Uneix-te a la revolució!

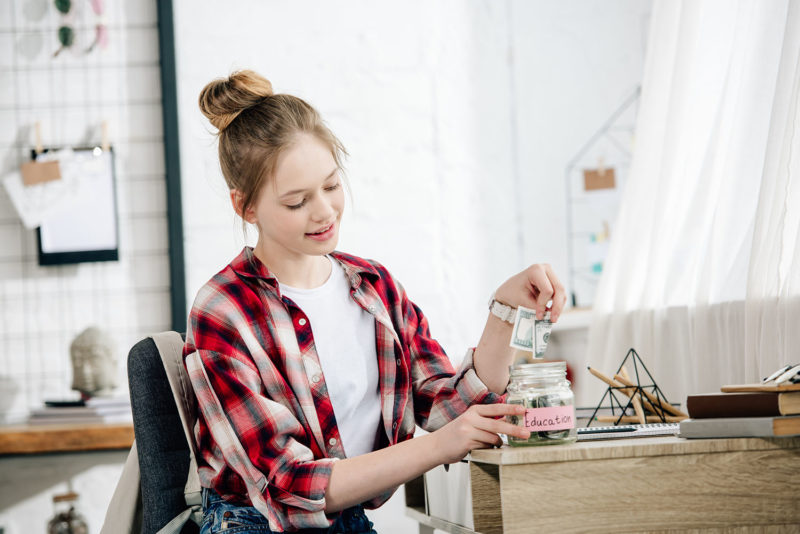
Learning the value of money can be so much more than a game for children. Passing on the values of economy to them can bring them values such as responsibility, collaboration, saving, learning to negotiate, or even entrepreneurship.
Experts recommend starting to talk about private and family financial management from the age of seven, when children can become aware that the ATM does not give money because it is magical, but because adults, with their work, earn it and keep it in the bank.
It is within the family that the first values about money are learned. Today, most children in our society have grown up in a consumerist system that has made them used to having it all, and having it all now. In this sense, the first lesson to be learned is that access to money is limited to one’s own productive capacity. They need to be taught to see the value of living within their limitations, and to be aware from a very young age that knowing how to spend is as important as knowing how to save.
Children and teenagers, the great consumers
Montse Junyent, educated in business management and administration, advises passing on to children “the value of money, which is hard to earn and must be used ethically“. Show them, from an early age, that all the decisions we make have an economic impact, from buying and accumulating toys, to the practice of buying and throwing, food waste, or even the use of plastic bags. Children can understand that one of these bags can end up in the sea and take four hundred and fifty years to disintegrate. Make them aware that the Earth is finite, and we must take responsibility and take care of it through sustainable consumption actions. Adults and children must be consistent with this idea and act responsibly in all areas, in our relationship with people, with the environment, with the world, or with our way of consuming.
Junyent also defends the economy of the common good, with the aim of “contributing to the construction of a more sustainable and fair life system”. She is committed to “transmitting and publicizing sustainable alternative economic models and helping children to grow as committed people, with criteria, information, and a desire to change what they do not like.” That is, to give children all the tools that allow them to be independent and make their own decisions, based on values such as commitment, sustainability, honesty, innovation, and creativity.
Values that can be passed on in many ways, including through games or stories, and that begin in school. Sustainability, for example, is one of the issues of most concern today, and therefore much talked about within the education system. On the other hand, according to Junyent, children are not taught to talk about economics from an ethical and responsible point of view as much as they should.
The value of money through pay
Many parents have doubts about whether to give money to their children. They often wonder when they should start giving their children allowance, and what the ideal amount is.
Allowance can be an important way of teaching children how to manage and value money, a learning that will serve them well in the future. There is no set age to start using money, but it is essential that when they do, they understand its value and the importance of saving.
Some parents associate pay with doing household chores, a view that many questions, arguing that all members of the family should collaborate in this type of activity. Whatever the mentality, the point is that the model of education that the child receives must be coherent. Therefore, it is not a question of whether to pay or not, but to find the perfect formula for learning through values.
Suggesting to children what they should spend their allowance on
As the child gets older, the allowance can be increased, always depending on the use that is made of it. It is important to suggest to children what they should spend it on, taking into account their wishes and the need they have for the product in question. Beyond avoiding the purchase of products that may not benefit them, it is important to establish a fluid conversation, without imposing anything, where we make them see the consequences of each of their purchases. It will also be a good time to show them new forms of consumption, always opting for a sustainable consumption model, which can provide a real benefit and for as long as possible over time, and for them to understand, in short, that money is there to make their lives easier and that using it unconsciously can lead to negative situations.
We usually start this teaching at around five or six years of age, although it can also be beneficial to do so at preschool age. For example, you can show them how picking up their toys can have a reward, whether in the form of a treat or something else, the point is to learn that if our actions have a positive impact, we will be rewarded. And maybe at first it will be through material things, or when we start working it will be through money, but over the years this teaching will mean that the best reward is the one we make for ourselves, based on our own values.
Teaching to save and share
A good way to show the importance of saving can be to divide the money that the child receives, from an early age, into two parts. The first is in the form of a piggy bank that they can keep at home, where they can keep all the money that can be spent, which would be the daily economy. On the other hand, you can have a bank account where you can put money for future savings. In this way, he will create a relationship with money from both perspectives and understand its importance.
Another important learning will be about sharing. Money does not have to be an individual possession, it can also be shared. An idea that may seem controversial socially, as we relate to money from the point of view of possession and, therefore, it individualises it. Educating children in this issue will allow them to experience this relationship from another point of view, with a more collective vision and social responsibility. It is important to show, by example, that money can be a tool to help others, from making donations to the most disadvantaged to shopping in a specific shop where the profits are used for social projects. There are many ways to help, and it is worth instilling this habit in children and young people.
In conclusion, children need to be taught clear lessons about money, and the best way will always be through practice, copying the behaviours they see at home. Therefore, parents should be the example of this learning, teaching them not to buy on impulse, but to plan their goals, both in the short and long term. When the time is right, they can be encouraged to do small paid chores, and if approached from an educational point of view, giving them pay can become a decisive way of teaching children to manage and value money, a lesson that can mark their lives. Finally, and taking into account the weight that the new generations carry for the future, focus on teaching based on the construction of a more sustainable and fairer system of life for all.
Do you want to be the first to receive the latest news about 11Once? Click here to subscribe to our Telegram channel.
Food has become a hidden luxury. Catalan families are allocating more budget than ever to eating, and in recent months the accumulated inflation in fresh products, especially fish and seafood, has pushed many households to the limit. The fishing ban, which reduces supply, drives prices even higher.
Faced with this outlook, it is time to stop theorising and move to action, combining every day, courageous and realistic strategies to contain expenses without giving up dignified and healthy eating.
Skyrocketing fish and prawns: what brought us here?
The fishing ban is necessary: it regenerates ecosystems and prevents collapses that would jeopardise the future of fishing. But its immediate impact is clear: less supply and higher prices. At the fish market it becomes more expensive, and even more so at retail. Added to this are other factors:
- Fishing fuel remains expensive, and part of the extra cost falls directly on consumers.
- Wholesalers compete for the limited product available, and auctions drive prices up.
- The restaurant industry absorbs the highest-quality fish, leaving less margin and less variety for household buyers.
- Imports do not compensate for the local decline, either due to quality, logistical costs or availability.
We see the result every week, with prawns, monkfish, hake, or tuna at prices that hurt to look at. The question, however, is not why it happens, but: what can we do while it happens?
Changing shopping habits: less romanticism and more numbers
We cannot control the fishing ban or fuel prices, but we can control how we buy. And this is where the real room for action lies.
- Buying local fish… but at the right time. Local sourcing is valuable, but so is timing. Before the ban, prices are more stable. Right after, when the fleet goes back out and the market fills up, opportunities appear that last only a few days but are very worthwhile. Buying without paying attention to the sea’s natural rhythm means paying twice as much.
- Alternating fresh and frozen. The myth that frozen is second-rate no longer holds. Properly frozen fish maintains nutritional properties and, above all, keeps its price stable. Hake, mackerel, salmon, swordfish, or tuna are excellent options to combine with fresh purchases. A silent but very effective strategy.
- Choosing undervalued species. The market is emotional: if everyone buys the same, the price goes up. But there are treasures outside the radar: bonito, mackerel, horse mackerel, small sole or mussels, nutritious and economical. When you step off the beaten path, your wallet breathes.
The trick that really works: intelligent substitution
Cooking is more flexible than it seems. When a product becomes too expensive, you don’t need to give it up: you need to replace it.
- Prawn too expensive? Frozen langoustine or fresh mussel.
- Sole unaffordable? Quality pangasius or small sole.
- Tuna prohibitive? Bonito, just as tasty and more affordable.
The recipes don’t change; what changes is the price. Good substitutions can mean savings of 20% to 60%. It’s not eating worse; it’s eating wisely.
Shopping with your brain: less improvisation, more planning
In an inflationary context, improvisation is extremely expensive. Planning becomes a vaccine against inflation. That means:
- Weekly shopping with a predefined menu: less waste and better control.
- Avoid buying day by day: that’s when prices are highest.
- Review promotions: some are traps disguised as discounts.
- Don’t go to the supermarket hungry: hunger is the enemy of your budget and the friend of impulsive buying.
The double-yield method
Cooking can be a source of expense… or of savings. When you realise that almost everything can be reused, your end-of-month numbers change, as long as you follow:
- Total utilisation. Fish heads and bones become broth that enhances other dishes. Tails and trimmings are ideal for croquettes, and dinner leftovers can become salads or omelettes.
The same happens with prawns: heads and shells enrich sauces, rice dishes and fideuàs, and the bodies, frozen in small portions, allow you to improvise a meal without buying anything. One prawn can have three lives. And each life is savings. - Cooking with strategy. Batch cooking, preparing food for two or three days in a single session, reduces energy consumption, avoids the daily decision-making fatigue and eliminates impulsive purchases. A small weekly effort with a huge return.
Reorganising the family budget
Food is a rigid budget category, but not an immovable one. Small adjustments make big differences:
- Replace spontaneous indulgences with planned purchases.
- Reduce soft drinks, alcohol and ultra-processed foods.
- Prioritise basic produce and avoid expensive prepared foods.
- Keep an eye on snacks and premium dairy.
- Reduce expensive weekend meals without giving up the pleasure of cooking well.
Prices won’t go down on their own
Prices have not returned to pre-inflation levels, and they will not. Distribution chains have consolidated margins, European policies do not curb intermediaries, small producers still lack bargaining power, and consumers pay the final stretch.
This is not catastrophism; it is a diagnosis of a food system that operates in an extractive logic. That is why the best strategy is to focus on what we can control from home.
Rising prices are a stubborn reality, but not an unbeatable one. With planning, intelligent substitutions, strategic shopping and efficient cooking, a family can reduce between 10% and 25% of its monthly bill. Is it work? Yes. Is it fair to have to juggle to eat well? No. But it is the tool we have while the system continues to operate under its own rules.
11Onze is the community fintech of Catalonia. Open an account by downloading the app El Canut for Android or iOS and join the revolution!

The Council of Ministers has approved an additional aid package for citizens affected by the DANA. As part of the new measures, the period when mortgage payments can be frozen is extended. Even so, who is responsible for the mortgage if our home is destroyed, and are we entitled to any help if we do not have home insurance?
The Official State Gazette (BOE) published today, Tuesday, the second package of urgent measures approved by the Council of Ministers to help citizens affected by the DANA in the municipalities of the Valencian Community, Castilla-La Mancha, and Andalusia and alleviate the disastrous economic situation that many families, the self-employed, and businesses find themselves in as a result of the floods.
The new aid package includes 110 additional measures worth 3.765 billion euros, in addition to the 10.6 billion announced on 5 November, for a total of 14.365 billion. This aid is to be allocated to the first phase of immediate response and the second phase of reconstruction, as part of the Immediate Response, Reconstruction and Relaunching Plan to deal with the damage caused by the DANA.
Among the new measures, Pedro Sánchez points out that this aid can be extended to owners who did not live in their properties, but who had rented them, as well as compensation for material losses to tenants and for goods that are not basic necessities. Furthermore, ‘in order for this aid to arrive more quickly, we have decided in this Council of Ministers to make an immediate advance payment of 50% to all citizens who apply for this aid’.
Who is responsible for the mortgages of those affected?
The Ministry of Finance and the banking sector have mobilised to implement a moratorium of at least three months on mortgage payments for citizens affected by the DANA. This is similar to the measures implemented by Spanish banks after the volcanic eruption of La Palma, when 3,227 moratoriums were granted for a total of 133.8 million euros.
In this context, and according to the decree approved last week, families could take advantage of a new extension of an extra nine months, during which the capital of the loan does not have to be paid, but the interest generated will continue to be charged. With the new measures approved on Monday, affected households at risk of vulnerability can extend this period for an additional 12 months.
Even so, many of these buildings have been totally or partially destroyed. It is estimated that, in the municipalities of Valencia alone, more than 75,000 homes have been affected by the floods. In these cases, home insurance, except for specific agreed coverage, does not cover the destruction of a home due to a natural catastrophe, thus, it will be the Insurance Compensation Consortium that will be responsible for taking care of the damage.
However, only homeowners who have taken out home insurance will be covered by the Consortium. In cases where there is no insurance, the Government has the power to classify an area as catastrophic, so that it can have access to a series of aid from the public administration.
As for those affected by this hurricane, people who have been affected can apply for up to 60,480 euros for the destruction of their usual residence; 41,280 euros if the damage affects the structure; 20,640 euros if it does not affect the structure; 10,320 euros for essential household goods; and 36,896 euros for common elements of a community of owners. In addition, it is possible, at no cost to the consumer, to modify and temporarily suspend supply contracts, as well as to defer bills.
For more information on the aid available and how to apply for it, you can consult the websites of the Administration and the consumer association FACUA.
If you want to discover fair insurance for your home and for society, check 11Onze Segurs.