Market capitalisation: the map of power
Nvidia is worth more than five trillion dollars on the stock market. Apple is approaching five. Alphabet exceeds four. But what does it really mean for a company to be “worth” this amount?
The answer takes us to one of the most widely used concepts in financial markets: market capitalisation. Understanding it allows us to compare companies, interpret indices and discover where a large part of the world’s capital is concentrated today.
A share price does not tell us how large a company is
Imagine two companies. The shares of the first are trading at 500 dollars and those of the second at 50. We might think that the first is ten times more valuable. That would be a mistake.
To know what value the market assigns to a company, we also need to know how many shares it has in circulation. The formula is simple:
Market capitalisation = price of one share × number of shares outstanding
This is also the definition used by the United States Securities and Exchange Commission.
If a company has 1 billion shares and each one trades at 100 dollars, its market capitalisation is 100 billion dollars. This does not mean that the company has this money in the bank. Nor is it its turnover, profits or the value of its assets. It is the value that the market assigns to all of its shares at a given moment.
This value also incorporates the future anticipated by investors. Growth, profits, technology, brand or competition can change it. This helps to explain Nvidia’s rise: the market does not only value the chips it sells today, but also the role it could play if demand for artificial intelligence infrastructure continues to increase.
Why is it so important?
Market capitalisation makes it possible to compare the stock market size of companies and commonly classify them as small-, mid- and large-cap companies.
It also determines the weight of many companies within indices. The calculation is often adjusted for free float, that is, the shares actually available on the market. S&P Dow Jones Indices uses this methodology in several of its indices.
This has an important consequence: a few giant companies can influence the performance of an entire index. Therefore, the fact that “the stock market is rising” does not necessarily mean that most of the companies that make it up are doing so.
It can also create a false sense of diversification. A fund may invest in dozens or hundreds of companies, but if the largest ones account for a large share of the index, much of the result will continue to depend on a small group.
When market capitalisation becomes power
A high stock market valuation can also provide competitive advantages. The shares of a large company can function as a powerful currency. They can be used to buy other companies, compensate employees or raise new capital. These corporations also tend to have more resources to invest in research, infrastructure and international expansion.
Being large can make it easier to keep growing. This is especially relevant when capital is concentrated in the same sector. Large technology companies have enormous resources to hire talent, acquire competitors and accelerate the development of new technologies.
But being large does not mean being invulnerable. Market capitalisation depends directly on the share price. It can take decades to build a company and only a few trading sessions to lose a considerable part of its value.
The stock market also tells us which sectors dominate
Thirty or forty years ago, among the world’s most valuable companies we found oil companies, banks, industrial conglomerates, telecommunications companies and major manufacturers. Today, semiconductors, artificial intelligence, software, cloud computing, digital platforms and electronics dominate.
However, an important distinction must be made. The market capitalisation of a sector is not equivalent to its weight in the real economy. To measure that weight, we must also look at employment, turnover, investment, exports or added value.
Agriculture, construction or industry may be essential to the functioning of a country without having a comparable presence in financial markets. Market capitalisation therefore gives us a different picture: it shows us where the value of listed companies is concentrated.
The 11 most valuable listed companies in the world
As of 2 October 2026, the global ranking allows us to see this transformation at a glance. Since share prices change every day, the figures are a snapshot of the market on that date.
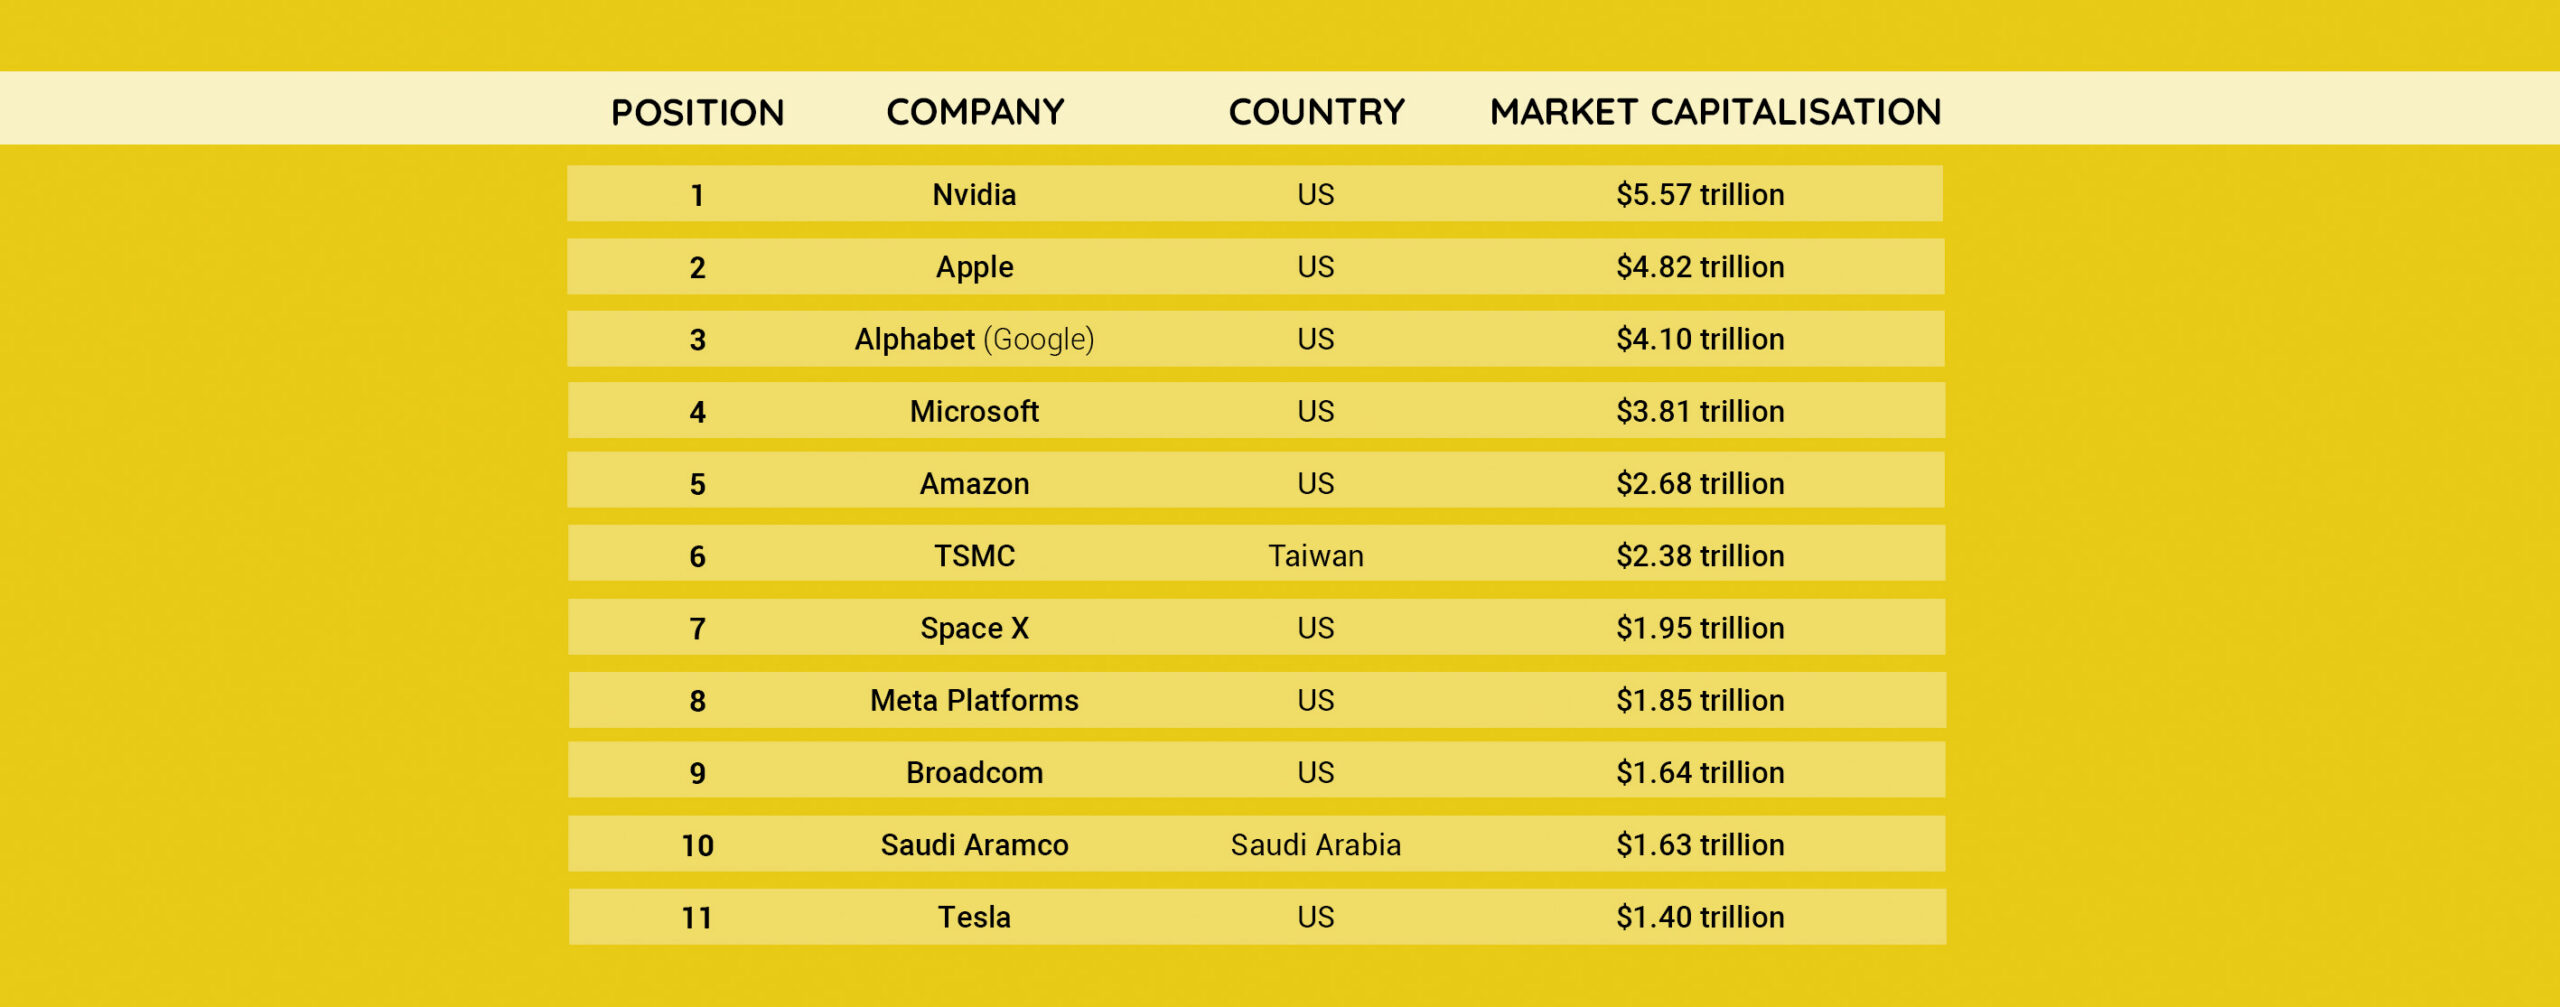
Source: CompaniesMarketCap. Data consulted on 2 October 2026.
The picture is revealing. Nine of the eleven companies are American and none are from the European Union. Technology clearly dominates the ranking, while Saudi Aramco is the most visible exception among the major traditional sectors.
The list also shows the extent to which semiconductors have become a strategic industry. Nvidia, TSMC and Broadcom occupy three of the top eleven positions.
It is not just a ranking of large companies. It is a map of where global capital is concentrated today.
A figure that explains a lot, but not everything
Market capitalisation makes it possible to compare companies, better understand indices and observe how value is distributed across markets. But it is not an absolute measure of a company’s value. A company may have an enormous market capitalisation and be overvalued. Another may be highly profitable and have a much lower valuation. And sectors that are essential to the economy may have little presence on the stock market.
That is why, when we see that a company is “worth” one trillion, two trillion or five trillion dollars, the interesting question is not only how it got there. It is also what this scale allows it to do and what it tells us about the way global capital is being distributed.
At La Plaça by 11Onze, we continue to explain the concepts that move the markets in order to understand what lies behind the big financial figures. Because understanding how a company is valued also helps us understand where capital is heading.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.
We have carried out a study of the costs of home insurance through a survey on the members of our community who are homeowners, with the aim of analysing the competitiveness of the product that we offer through 11Onze Segurs.
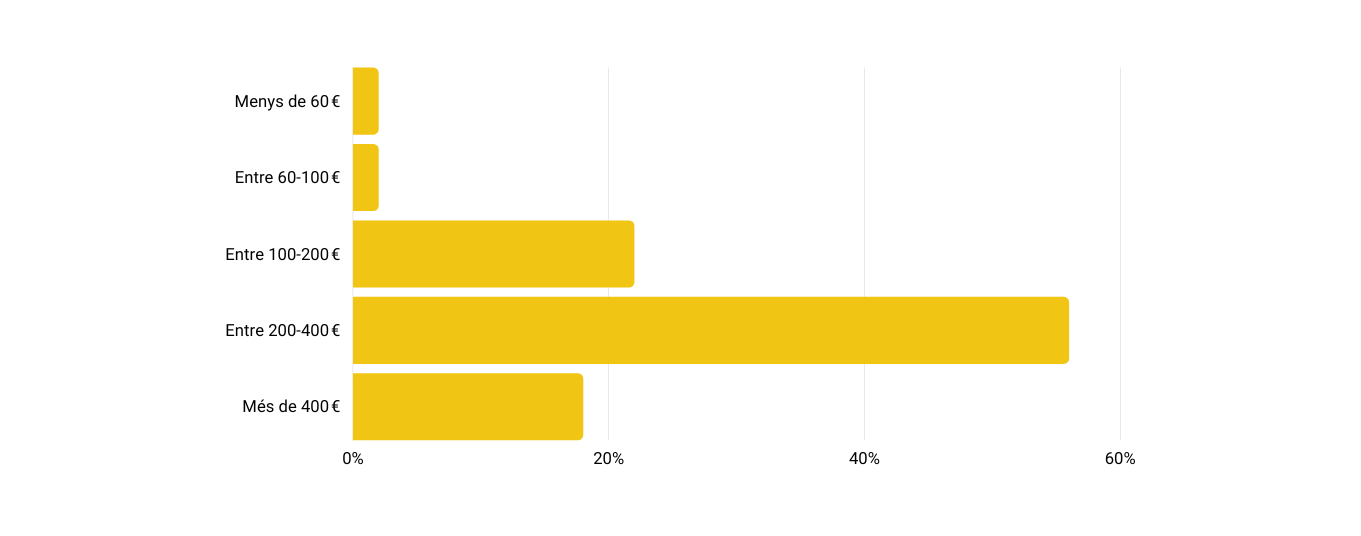
The survey was conducted by 11Onze through our Telegram channel with the participation of 279 users who responded to the question: “How much do you pay for your home insurance each year? They were given the option to choose from a range of prices ranging from €60 per year to more than €400.
The final data shows that 56% of users pay between €200 and €400 per year for their home insurance, while 22% spend between €100 and €200 per year. In addition, 18% pay more than €400 per year. These results are in line with the average annual price of home insurance in Spain, which is around €301 per year.
How much do you pay for your home insurance?
A more competitive alternative
At 11Onze Segurs we believe that you can reduce the cost of home insurance by optimising processes and personalising coverage. That’s why we have a completely digitalised platform, where we do away with paper contracts, physical agencies, management fees, cancellation and contract change fees, which is already a considerable saving, but we also let you modify and adapt the coverages to your needs at any time, before and after signing the contract.
In this way, we can offer you home insurance from €5 per month. Our policy is designed so that you do not pay more for your insurance, offering a monthly or annual fee, without permanence, between 15%-20% cheaper than with traditional insurers. What is the monthly cost of your current home insurance? Do you want to know how much you could save? Try our price simulator by entering some basic data, and you’ll get your no-obligation quote instantly.
If you want to discover fair insurance for your home and for society, check 11Onze Segurs.
When a major sports star changes sponsors, the move goes far beyond a new logo on their boots or shirt. The abandoned brand can lose years of association with an idol, while the new one can suddenly buy notoriety, credibility and access to millions of consumers.
Nike experienced it with Messi and Stephen Curry. Now it is experiencing it again with Kylian Mbappé. But there is an even more interesting question: can a brand really recover the millions it pays for an athlete?
Michael Jordan: when the sponsored athlete became a brand
To understand today’s business, we have to go back to 1984. Nike did not yet dominate basketball and Michael Jordan had just arrived in the NBA. Adidas was his preferred brand, but Nike offered him a deal that would end up transforming the industry.
The initial contract guaranteed Jordan $500,000 a year for five years, in addition to royalties and other compensation. But the great revolution was something else: Nike did not limit itself to using his image to sell a pair of shoes. It built a product and, later, a brand around him.
The first Air Jordans went on sale in 1985. Nike expected to generate around $3 million in revenue during the first three years; according to Sports Illustrated, the product generated around $130 million in the first year alone. What had begun as a sponsorship ended up becoming Jordan Brand, a division of Nike in its own right.
Four decades later, the scale of the business explains better than any advertising campaign what had changed. Nike reported that Jordan Brand had exceeded $7 billion in annual revenue during fiscal year 2024.
Jordan demonstrated that an athlete could stop being simply someone who advertised a product and become a business asset capable of generating value for decades. A large part of today’s major contracts are based on that idea.
Messi and Cristiano: losing a star or locking one in
Before becoming a global Adidas icon, Lionel Messi had worn Nike. In 2006, when he was only 18 years old, the Argentine switched the American company’s boots for Adidas’s three stripes. Nike considered that it had contractual rights over the player and the dispute ended up in court. The company even claimed €5.5 million in compensation, but in 2007 a commercial court in Barcelona concluded that the document signed with Nike did not constitute a definitive contract and ruled in Messi’s favour.
Adidas had bet on him before he became the best player in the world. According to the court ruling reported at the time by EFE, the new agreement more than tripled the income Nike had offered him.
Seen in perspective, Adidas was not buying an established superstar. It was buying the possibility that he would become one.
The bet paid off extraordinarily well. In 2017, Messi extended his relationship with Adidas through a long-term agreement that various sources described as a lifetime deal. Forbes estimated that the previous contract generated around $12 million a year for him.
Nike, however, made a very different decision with the other great footballer of his generation. Cristiano Ronaldo has maintained a relationship with the American company since the beginning of his professional career. At the end of 2016, Nike announced a new long-term agreement with the Portuguese player. Various reports described it as a lifetime contract and compared it with LeBron James’s deal, potentially valued at $1 billion. The exact figure of Ronaldo’s contract, however, has not been made public.
What has been estimated is its commercial impact. In 2016, Hookit data reported by Forbes calculated that Ronaldo’s sponsored content had generated around $176 million in media value for all of his sponsors. Compared with sponsorship income of around $32 million, that was equivalent to an estimated media return of 449%, without counting other commercial channels.
Here a first lesson appears. Nike let Messi slip away when he was still a prospect. With Cristiano, it chose to secure a long-term relationship with a star who had already demonstrated an extraordinary ability to generate value. Just as important as identifying the next star is knowing when you cannot afford to lose one.
Curry: the cost of letting a prospect slip away
Nike would experience a similar situation again with Stephen Curry. The point guard had been a Nike athlete, but in 2013 the company did not match Under Armour’s offer. Curry was not yet the global star he would become.
Under Armour took the risk. Two years later, Curry was NBA MVP and a champion with the Golden State Warriors. The company’s footwear sales grew by 40% in one quarter and reached a record $153 million, driven in part by the Curry One.
The initial growth was spectacular. But the story also demonstrated that signing a star does not automatically turn every product into a success. In 2017, Under Armour acknowledged that the Curry 3 was selling below expectations. The athlete can bring millions of consumers to the shop window. After that, the product also has to work.
Mbappé: buying a star to enter a market
This very September 2026, Kylian Mbappé starred in a move that takes this strategy one step further. After almost twenty years linked to Nike, he signed with On, the Swiss company that had established itself in running and tennis but was not yet a relevant player in football.
For On, Mbappé is not simply a footballer who has to sell boots. He is a way of entering a market dominated by Nike, Adidas and Puma without having to spend decades building the same level of notoriety. The deal also includes an equity stake and the player’s involvement in product development. Following the announcement, On shares rose by 3.8%.
The brand is not merely hiring an endorser. It is bringing in a partner who has incentives for the company’s value to increase. And Nike is not only losing Mbappé. It is watching a star it had helped build over the years become the spearhead of a new competitor in football.
How much is a star really worth?
At this point, the question that explains the entire business appears: how can a company know whether paying millions to an athlete pays off? The answer does not simply consist of comparing the contract with the sales of a pair of shoes. A star can sell more units, make it possible to charge a higher price, steal customers from the competition, open new markets or multiply brand awareness. And there is an even more difficult element to value: they can prevent all that value from ending up in the hands of a rival.
The case of Tiger Woods allows us to put numbers on it. An academic study published in Marketing Science analysed the golfer’s impact on Nike golf ball sales between 2000 and 2010. The researchers estimated that the sponsorship had generated $103 million in additional profit for Nike thanks to an extra 9.9 million dozen balls sold.
In addition, Woods’s presence allowed Nike to charge approximately 2.5% more for its products. According to the study, golf ball sales in the United States alone made it possible to recover approximately 57% of the $181 million invested in the contract. And this did not include clothing, footwear or international sales.
This is probably the best answer to the question of whether these contracts can be recouped: yes, but the real return is much broader than the direct sales of the advertised product.
The cost that does not appear in the accounts
When Nike lost Curry, it did not record a bill for having let him go. When Messi signed with Adidas, there was no accounting entry entitled “lost future profits” either. But there is an opportunity cost.
If a star ends up generating a multibillion-dollar line for a competitor, the brand that let them slip away does not only lose potential sales. It loses notoriety, cultural association and years of relationship with a new generation of consumers.
That is why the price of a star is not only what it costs to sign them. It is also what it can cost to watch them succeed with your competitor.
And, naturally, there is the opposite risk. The athlete can get injured, lose performance, suffer a reputational crisis or simply stop connecting with consumers. The more a company identifies its brand with one person, the more exposed it becomes to what happens to that person. A star can multiply a good strategy. They can hardly save a bad one.
From Jordan to Mbappé: from sponsored athletes to partners
This is where the circle that Michael Jordan began to draw four decades ago closes. The traditional model was simple: the company paid and the athlete lent their image. Jordan demonstrated that the athlete could become the centre of a brand. Then came increasingly longer contracts, royalties, signature lines and lifetime agreements. Now another step is being taken.
Roger Federer invested in On and went from ambassador to shareholder. Mbappé has incorporated an equity stake into his new agreement with the same company. The relationship is increasingly becoming a partnership between two brands: the corporate brand and the personal brand.
The difference is considerable. In traditional sponsorship, the athlete is paid for the brand to grow. When they receive shares, they profit if the brand grows. Jordan, Messi, Cristiano Ronaldo, Curry and Mbappé thus explain the evolution of a business that has changed radically.
Creating a brand around a star. Betting on a prospect. Locking in an icon. Stealing talent from the leader. Or turning the athlete into a partner to enter a new market.
That is why, when a star changes logos, what is at stake is not only the value of the contract. There are future sales, market share, reputation and the possibility that millions of consumers will end up associating their idol with a brand for an entire generation.
Because in the sports sponsorship business, knowing how much it costs to sign a star is just as important as calculating how much it can cost to let them slip away.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.
If you would like to learn more about this topic, we recommend:
 Finances
Sports sponsorship by banking institutions: A win-win relationship
9 min readThere are two realities that give meaning to this title. On the...
American magnates —Bezos, Dimon, Buffett, Ellison— are selling stocks in a moment of market euphoria. What do they know that the rest of us ignore? When those with privileged information flee the very markets they built, we may not be talking about conspiracies, but about a clear signal: the system is creaking from within.
At first glance, everything looks fine. The S&P 500 is hitting record highs, the Nasdaq has recovered from the 2022 crash, and the big tech companies are leading the party. The media speaks of a “new innovation cycle.” But beneath this radiant surface, something is stirring.
According to public data, Bezos sold about $737 million worth of Amazon shares at the end of June 2025. Jamie Dimon sold roughly $31.5 million in JPMorgan shares this year —the first sale since he became CEO—; Brian Chesky (CEO of Airbnb Inc.) sold 190,301 shares on February 12, 2025, worth approximately $26.7 million.
The University of Melbourne sums it up: “While institutional investors sell, retail investors buy.” Small investors, encouraged by media optimism, enter the market just as those who know it best are heading out the back door.
Those who see before we do
This is not about conspiracy, but information asymmetry. The big players have analytical systems and access to data that allow them to detect, months in advance, the symptoms of a brewing crisis. The indicators they track —tensions in the debt market, drops in real productivity, or signs of exhaustion in the Federal Reserve’s expansionary policy— are invisible to ordinary citizens.
When these warnings pile up, smart money moves. The rich don’t sell because they need liquidity; they sell because they want to leave before collective confidence breaks. It’s the same instinct that makes central banks hoard gold while assuring us that inflation is “transitory.”
Turkish economist Nouriel Roubini is known for his ability to foresee major financial crises. A professor at NYU’s Stern School of Business, he rose to global fame after accurately predicting the 2008 financial crisis, earning the nickname “Dr. Doom.” In his words: “Confidence in the financial system doesn’t collapse overnight; it unravels like a threadbare stocking.” The tycoons’ moves are precisely those first threads snapping.
Fear of the new financial order
Another factor haunting the ultra-rich is the structural shift in the global monetary system. The Bank for International Settlements (BIS) confirms that over 130 countries are now working on central bank digital currency (CBDC) projects. At first glance, they appear to be a natural technological evolution of money. But in practice, they enable total control over transactions and individual wealth.
Bloomberg recently warned that CBDCs could pose serious privacy and control challenges, as governments would gain direct access to transaction data and could impose restrictions on how money is used.
Meanwhile, dedollarization is advancing. Russia, China, India, and Brazil are promoting bilateral trade deals without the dollar, while central banks are hoarding gold at record levels. According to the World Gold Council, more than 1,000 net tons of gold were purchased in 2024 —the highest volume in half a century. Private capital is following the same path. They no longer trust the system they designed themselves.
The divorce between the market and the real world
Meanwhile, the gap between market valuations and the real economy widens. Corporate profits are not growing at the same pace as stock prices, and U.S. public debt already exceeds 125% of GDP.
Stock prices now reflect a fiction of prosperity, sustained by massive buybacks and money printing. The Federal Reserve has injected more liquidity in the last decade than in the entire 20th century. But cheap money has created an artificial economy where wealth isn’t produced —it’s mirrored.
This model increasingly resembles a pyramid: as long as new investors are willing to buy, the system stands. Once those at the top start selling, the countdown begins.
The return to real assets
When the air of the system becomes too toxic, the rich return to where there’s always oxygen: tangible assets. Gold, silver, farmland, energy, and even physical art become safe havens against monetary instability.
Gold keeps breaking records daily, the clearest example of all. While markets celebrate new technologies and digital ETFs, financial elites are buying physical metal. The Wall Street Journal notes that while gold-related companies grow, physical gold remains the only true safe haven —proof that trust has gone digital, but fear remains solid gold.
The logic is simple: an asset that depends neither on a government’s promise nor a company’s performance is the only one capable of weathering a systemic storm.
When flight becomes a warning for all
The rich fleeing is not an anecdote —it’s a metaphor for the end of a cycle. Financial capitalism, as we know it, is reaching saturation, driven by unlimited debt, wealth concentration, markets detached from reality, and confidence that is no longer blind but forced.
However, this flight could also be an opportunity. If those who control the system are stepping aside, it’s time for citizens to regain real financial power: to learn how money works, protect their savings, diversify, and invest with common sense.
As Raymond Thomas Dalio, one of the world’s most influential investors and founder of Bridgewater Associates, reminds us: “When things that seem permanent stop being so, those who understand change survive; the rest suffer.”
We need not see conspiracies where there is prudence —but we cannot ignore that when those who know the most about money leave the table, the game is about to change. The rich are fleeing their own system because they know trust is finite —and the next crisis won’t just be financial, but one of legitimacy.
In that scenario, the ordinary citizen has only one choice: understand the system to stop being its victim. Start thinking like those who are leaving —not to imitate them, but to anticipate. Because true economic freedom is born from knowledge, not faith in a system already taking on water.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
After a few months in which inflation seemed to be starting to stabilise, prices have accelerated again in Europe in 2026. This time, the main trigger is not excessive consumption, but the rising cost of energy as a result of tensions in the Middle East.
When oil prices rise, it does not only become more expensive to fill up the tank: transport, industrial production and, in general, a large part of economic activity also become more costly. Sooner or later, part of these costs ends up reaching consumers.
Against this backdrop, the European Central Bank has once again turned to one of its main tools: interest rates. But to understand why it does this, we need to start at the beginning. What exactly is inflation? Why can raising rates help control it? And why, when money loses purchasing power, does gold regain prominence?
When money buys less
Inflation is the general increase in prices over a period of time. Put much more simply, it means that the same amount of money buys fewer things.
If today we have €100 and can buy ten products costing €10 each, but a year later those same products cost €11, our €100 is still the same amount. The problem is that it no longer has the same real value.
In August 2026, annual inflation in the euro area reached 3.3%, after 2.9% in July, and energy was the component that rose the most, with a year-on-year increase of 14.3%. By contrast, if energy is excluded, inflation remained much more contained, which clearly shows where much of the current pressure on prices is coming from.
This difference is important because the European Central Bank aims to keep inflation at around 2% over the medium term, a level it considers compatible with price stability. When inflation moves too far away from this objective, the ECB intervenes to prevent the increase from becoming a persistent problem.
The problem starts with energy
Not all inflationary crises have the same origin. The one we experienced in 2021 and 2022 combined supply chain problems after the pandemic, a very rapid recovery in consumption, expansionary monetary and fiscal policies and, finally, the energy impact of Russia’s invasion of Ukraine.
The current rebound has a different composition. This time, the main factor is an energy supply shock related to the conflict in the Middle East, which has pushed up the price of oil and other energy sources.
The effect spreads quickly. If fuel becomes more expensive, transporting food and goods costs more. The costs of many factories and services that depend on energy also increase. Companies may absorb part of this extra cost for a while, but when the situation lasts, they usually pass part of it on to consumers.
This is how an energy crisis turns into inflation. A problem that initially affects oil ends up influencing the price of food, clothing, services or practically any product that needs energy or transport to reach us.
The united kingdom shows the domino effect
The United Kingdom provides a good example of this transmission. Annual inflation rose from 2.9% in July to 3.1% in August 2026, with transport being one of the main drivers of the increase. Vehicle fuels became 23% more expensive in one year.
But the effect could already be seen before products reached consumers. The cost of materials and fuels used by British manufacturers was rising by 6.1% year on year, while factory gate prices were increasing by 3.7%.
This process sums up the current inflationary mechanism well: first, raw materials become more expensive, then business costs rise and, finally, part of that increase is incorporated into selling prices.
What can the ECB do?
This is where interest rates come into play, which are simply the price of borrowing money. When a family takes out a mortgage or a company seeks financing, it does not only repay the money it has received, but also pays interest. The higher the rate, the more expensive it becomes to borrow.
The European Central Bank does not directly set the rate on each mortgage, but it does establish the official rates that influence the cost of money within the banking system. When it raises them, credit tends to become more expensive and this reduces consumption and investment.
A family may postpone buying a car or a home, while a company may decide that a new investment is no longer profitable enough. If the economy spends less, pressure on prices decreases and inflation tends to moderate.
But this tool has an obvious limitation: higher interest rates cannot produce more oil or resolve a geopolitical conflict.
When inflation originates from an energy supply problem, the ECB cannot act directly on the cause. What it tries to do is prevent the initial rise in energy prices from spreading throughout the economy and ending up generating a permanent cycle of price and wage increases.
This forces the central bank to seek a difficult balance. If it does too little, inflation may become entrenched; if it raises rates too much, it may cool the economy excessively.
The cost of slowing prices
For households, this situation creates pressure from two sides. Inflation reduces the purchasing power of income and savings, while higher interest rates make loans, mortgages and business financing more expensive.
This is one of the reasons why central banks try to act gradually. ECB projections suggest that inflation will continue to moderate over the coming years, but they also show that returning sustainably to 2% is not necessarily an immediate process.
And it is precisely when this combination of inflation, high interest rates and geopolitical uncertainty appears that many savers begin to wonder whether keeping all their wealth in cash is enough.
Why is gold gaining prominence again?
When inflation, high interest rates and geopolitical uncertainty coincide, many savers begin to wonder whether keeping all their money in cash is enough. The problem is simple: the euros we have in our account do not disappear, but if prices continue to rise, they buy less and less.
It is in this context that gold regains prominence. Unlike the euro, the dollar or the pound, it cannot be created by decision of a central bank. It is a physical, scarce asset that is costly to extract, and this gives it characteristics that differ from those of traditional financial assets. This does not mean that its price always rises or that it automatically protects against every inflationary episode, but it can help diversify wealth and reduce dependence on a single currency or a single type of asset.
This role helps explain why central banks themselves continue to accumulate it. During the second quarter of 2026, they bought 289 net tonnes of gold, and a large majority of reserve managers surveyed by the World Gold Council expect global gold reserves to continue increasing. Among the main reasons are diversification, long-term value preservation and the need to reduce exposure to monetary and geopolitical risks.
For savers, the key idea is that keeping money and preserving its purchasing power are not exactly the same thing. If all wealth is concentrated in cash, any loss in the value of the currency affects all savings. Including assets that behave differently can help spread that risk.
Gold does not eliminate inflation or guarantee returns, but its scarcity, its physical nature and its independence from any issuer explain why it continues to form part of central bank reserves and many wealth management strategies.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.
Tariffs are often presented as a tax on foreign products, an apparently simple tool to protect domestic industry and penalise competitors from abroad. But reality is far more complex. The case of the nearly $100 billion that the Trump Administration has already had to refund following a ruling by the United States Supreme Court is a masterclass in how international trade really works. Who pays a tariff? Who bears its cost? And what happens when the courts conclude that the tax had no legal basis?
It is rare for a judicial decision to force a government to refund tens of billions of dollars in taxes already collected. This is exactly what is happening in the United States after, on 20 February 2026, the Supreme Court ruled by six votes to three that the International Emergency Economic Powers Act (IEEPA) does not authorise the president to impose tariffs.
The White House had used this 1977 law, designed to grant extraordinary powers to the president in the face of international emergencies, to justify broad taxes on imports from much of the world. Trump had described the persistent US trade deficit as a national emergency and had relied on this law to impose the so-called reciprocal tariffs.
The Supreme Court, however, concluded that Congress had not delegated through the IEEPA a tariff power of virtually unlimited scope. The ruling points out that when Congress grants the president the power to impose tariffs, it does so explicitly and with specific limitations, which is not the case with this law.
The consequence has been enormous. By the end of July, the Administration had already processed approximately $100 billion in refunds, around 60% of the nearly $165 billion collected through the tariffs that were struck down.
When revenue turns into expenditure
This is one of the less visible aspects of the case. During 2025, tariffs provided the federal government with extraordinary revenue. Monthly customs-duty receipts exceeded $31 billion in October, strengthening the Administration’s argument that these taxes could also become an important source of funds for the Treasury.
The ruling reversed the flow. In June 2026, the government collected $23.6 billion in customs duties, but refunded $49.2 billion, resulting in a net outflow of $25.6 billion in that month alone. The refunds contributed to pushing the monthly federal deficit up to $120 billion.
An instrument presented as a source of revenue had temporarily become a multibillion-dollar expense.
Washington, however, has not abandoned its strategy. Following the legal defeat, the Administration has sought other mechanisms explicitly provided for in trade legislation. Among the most important is Section 301 of the Trade Act of 1974, which allows action against trade practices considered unfair, but requires prior investigations, hearings and administrative procedures.
By July 2026, the Administration had already used this route to impose new tariffs on dozens of economies, as well as a 25% levy on certain imports from Brazil.
Who reallypays a tariff?
This is where one of the great confusions in the political debate appears. When Washington imposes a 20% tariff on a product made in China, it is easy to think that the Chinese company pays that tax. Legally, however, that is not how it works.
The company that pays the tariff at customs is the US company importing the goods. From that point on, an economic negotiation begins that varies depending on the product, the sector and each player’s ability to protect its margin.
The importer may absorb part of the cost, pressure the manufacturer to lower the price, seek an alternative supplier or pass the additional cost on to its customers. Very often, a combination of all these options occurs.
Therefore, saying that a tariff is “paid by China” is a simplification. The tax is formally paid by the US importer, while its economic cost is ultimately distributed among companies, suppliers and consumers.
This difference between who pays the tax to the authorities and who ultimately bears the burden is essential to understanding the paradox of the current refunds.
Tariffs also transform supply chains
The impact of a tariff policy does not end with higher prices. When importing from a particular country becomes more expensive, companies react. They look for new suppliers, move part of their production, replace components or bring purchases forward before the new taxes come into force.
This process can profoundly alter global supply chains. A company that imported components from China for decades may start buying them from Vietnam, Mexico or India, not necessarily because those countries are more efficient, but because the tariff changes the cost equation.
This is precisely one of Trump’s political objectives: to reduce external dependence and encourage production in the United States. But the transformation comes at a price. Changing suppliers, restructuring contracts or modifying industrial processes requires time, investment and new logistics.
Uncertainty must also be added to this. A company can adapt to a high tariff if it knows it will remain stable. Planning becomes much more difficult when rates change depending on presidential decrees, diplomatic negotiations or court rulings.
When the trade war reaches household budgets
The effects are not distributed equally among all families either. A high-income household can absorb the increase in the price of an appliance, a phone or a vehicle relatively easily. For a family with fewer resources, any increase in the cost of everyday goods weighs proportionally much more heavily on the budget.
Another paradox appears here. A policy designed to protect US workers and strengthen domestic industry can also end up increasing the cost of the goods consumed by those same workers.
Assessing the success of a tariff therefore requires looking beyond revenue or the reduction in imports. It is necessary to determine whether it has generated enough new industrial activity and employment to offset higher prices and the costs borne by companies and consumers.
An economic and geopolitical weapon
Moreover, it would be a mistake to understand tariffs solely as a fiscal or industrial policy. For Trump, they are also a tool of geopolitical pressure. Washington can use access to the world’s largest consumer market as a negotiating instrument. Threatening new tariffs makes it possible to pressure other governments on trade, industrial and even political issues.
The new levies adopted in July under Section 301 illustrate precisely this dimension. The Administration has justified them, among other reasons, by citing other countries’ responses to forced labour, trade practices considered unfair or policies that harm US companies.
Tariffs thus become something more than taxes. They form part of the competition between powers to control markets, production, technology and supply chains.
And now, who gets the money back?
The Supreme Court ruling introduces a new paradox. If much of the cost of the tariffs was ultimately passed on to companies and consumers, it would be easy to think that the refunds should also be distributed among all those who bore them. Legally, however, this is almost impossible.
The money is returned to importers because they are the ones who made the payment at customs. But this does not mean that these companies bore the entire cost. A company may have paid $10 million in tariffs and recovered part of that amount by increasing the price of its products.
If the State now refunds the full $10 million, the question is inevitable: what happens to the consumers who paid more?
Reconstructing the exact path of the tax is extraordinarily difficult. It would be necessary to determine what share was absorbed by the importer, what share was passed on to the distributor, what share ended up incorporated into the final price and what share was absorbed by the foreign manufacturer. The issue has already reached US courts, while some companies are considering whether to pass part of the refunds on to their customers.
Each product, each company and each market reacts differently. For this reason, a court-ordered refund can restore the money to the party that legally paid the tax, but it can hardly reconstruct who actually bore the economic cost.
The battle over tariffs continues
The legal defeat does not mean that Trump has abandoned his trade policy either. What has disappeared is a particular legal route for implementing it.
In July, the Administration replaced much of the previous architecture with new tariffs under Section 301, including levies of between 10% and 12.5% on imports from numerous trading partners. Tariff policy therefore remains a central element of the White House’s economic strategy.
Trump regards tariffs as a tool to reduce the trade deficit, protect US industry, bring production back and increase Washington’s bargaining power. His critics point out that they can also raise prices, harm companies that depend on imported components, trigger trade retaliation and reduce purchasing power.
This is not merely a legal battle over presidential powers. It is a much deeper debate about what trade model the world’s largest economy wants to pursue and how much it is willing to pay to protect its domestic market.
The great $100 billion paradox
The story of these refunds leaves an economic lesson far more valuable than the figure itself. A tariff is not simply a tax on imports. It is a chain of costs that moves through the entire economy. The State collects it, the importer formally pays it, companies and consumers partially bear it and, when the courts order it to be refunded, the money goes back to the party that legally paid it, not necessarily to the party that bore its impact. Perhaps this is the best demonstration that, in economics, the most important question is almost never who pays, but who ultimately bears the real cost.
11Onze is Catalonia’s fintech community. Open an account by downloading the El Canut app for Android or iOS. Join the revolution.
Que sí, que la joventut és per gaudir-la i cal aprofitar cada moment, encara que això impliqui gastar més del compte en viatges, roba i oci. Però a partir dels 30 anys, hauries d’haver après a dominar alguns hàbits financers per aconseguir estalviar pel futur.
Si ets jove, atent, perquè a 11Onze recollim cinc consells que et poden ser útils per començar a organitzar les teves finances: aprendre a fer un pressupost, estalviar, no fer-se il·lusions espúries, no endeutar-se massa i guardar sempre una mica més. Aquestes són les claus per assolir la desitjada independència econòmica. I, si no en tens prou, la cap d’agents Mireia Cano t’aconsella com crear el teu primer pla d’estalvi al vídeo de sota!
- Aprèn a fer un pressupost. Això ho hem explicat a La Plaça alguna altra vegada, però la independència econòmica només s’aconsegueix si aprenem a complir amb un pressupost. Per això, cal saber quants diners guanyem i, sobre aquests ingressos, haurem de calcular el que volem gastar per assolir l’objectiu d’estalvi que ens hàgim posat.
- Estalvia entre un 10% i un 20% del que guanyes. I quina és la meta d’estalvi que ens hem de posar? Els experts recomanen, com a mínim, estalviar entre el 10% i el 20% del que ingressem, sobretot si el teu sou és molt baix.
- No t’expliquis el conte de la lletera. Amb les teves finances has de ser realista. Si tens una feina corrent amb un sou comú, no pots somiar a fer-te ric. Quina edat tens i què t’agradaria aconseguir a la vida? Quant de temps creus que hauràs d’invertir amb els diners que guanyes ara? Així sabràs quants diners has d’estalviar.
- Si t’endeutes, tu controles. Si a partir dels 30 anys, necessites endeutar-te per pagar el cotxe, la hipoteca o els estudis, controla que no tinguis cap deute acumulat i, si necessites demanar un préstec, avalua que això no sigui una llosa que arrosseguis massa anys. En aquest sentit, un bon mètode és llistar els teus deutes del més gran al més petit, i invertir els teus ingressos a pagar-los en aquest ordre.
- Guarda sempre una mica més, per si de cas. No saps mai quan tindràs una despesa inesperada i urgent. Per això, està bé sempre tenir un fons d’emergència pel que pugui passar. Per això, està bé esbossar un pla per guardar un percentatge del teu estalvi a aquest fons de contingència.
Com crear el teu primer pla d’estalvi
Compartir compte corrent amb altres persones, ja siguin familiars, companys de pis o socis, té implicacions tant per a l’organització de les nostres finances com per a la nostra fiscalitat. Mireia Cano, cap d’agents d’11Onze, explica les diferents fòrmules per constar en un compte i les responsabilitats fiscals que comporten.
Un primer element que s’ha de considerar quan volem compartir un compte corrent és el rol de cada persona, ja que es pot constar com a titular, persona autoritzada o representant legal.
Els titulars d’un compte són responsables dels diners a parts iguals a no ser que algun document oficial acrediti el contrari. A més, els titulars “poden tenir firma indistinta, és a dir, que qualsevol pot fer operacions, o bé firma mancomundada, és a dir, que cal la firma de tots ells per operar”, com explica Mireia Cano.
Una altra opció és que algú consti en un compte com a autoritzat o firma reconeguda. En aquest cas el titular és qui té el poder sobre els diners i qui en respondrà a nivell fiscal, però autoritza una altra persona per fer determinades accions, com fer transferències o treure diners. Això sí, una persona autoritzada mai podrà crear o cancel·lar contractes de comptes corrents o de targetes vinculades.
Un tercer rol és el de representant legal, que s’utilitza, per exemple, en els comptes de menors i de persones dependents. Els representants legals tenen la potestat sobre els diners del compte, tot i que no siguin titulars.
Ser titular d’un compte té implicacions legals.
Quan compartim un compte corrent, s’ha de tenir molt en compte com ens pot afectar cadascuna de les nostres accions i de les altres persones que hi participen. Per tant, és molt recomanable que, abans d’obrir el compte, definim per a què l’utilitzarem i tinguem clar què implicarà per a cada persona i quines responsabilitats estem assumint en termes legals i tributaris.
11Onze és la fintech comunitària de Catalunya. Obre un compte descarregant la super app El Canut per Android o iOS. Uneix-te a la revolució!

Decentralized Finance, or DeFi (Decentralized Finance), is redefining the way we send money, invest, borrow, and manage our assets. Imagine being able to send money to anyone in the world in less than a minute, apply for a loan without visiting a bank branch, or invest your savings at any time, on any day of the year. Just a decade ago, this would have sounded like science fiction. Today, thanks to DeFi, many of these possibilities have already become a reality.
DeFi is not a new currency, nor is it designed to replace banks. Instead, it represents a new way of delivering financial services by leveraging blockchain technology. Just as the Internet revolutionized the way we share information, decentralized finance aims to do something similar with money: allowing individuals and businesses to interact directly, without every transaction necessarily having to pass through a single intermediary.
When financial services become software
In the traditional financial system, banks safeguard money, validate transfers, grant loans, and record every transaction. In the world of DeFi, many of these functions are performed by smart contracts—computer programs that automatically execute predefined instructions when specific conditions are met.
These contracts run on a blockchain, a shared digital ledger that enables transactions to be verified transparently and securely. The result is a financial infrastructure that operates continuously, without relying on office hours or manual processes. In this model, trust is no longer placed exclusively in a financial institution but increasingly in the rules embedded within the software itself.
The wallet: Your gateway to DeFi
Using these services does not require opening a bank account. Instead, users need a wallet, or digital wallet. More than simply a place to store cryptocurrencies, a wallet serves as a user’s digital identity on the blockchain. It allows users to hold assets, authorize transactions, and connect to different decentralized protocols.
The key difference compared with a traditional bank account is that, in a non-custodial wallet, only the owner holds the private keys. This means users retain direct control over their assets without relying on a financial institution to manage them.
This model strengthens individuals’ financial sovereignty, but it also comes with greater responsibility. If the wallet’s private keys are lost, there is generally no authority capable of restoring access.
What can you do with DeFi?
Decentralized finance goes far beyond buying and selling cryptocurrencies. Today, it enables users to exchange digital assets, obtain loans by providing collateral, earn returns by supplying liquidity to other users, or send money anywhere in the world within minutes.
One of the most common questions is where the money being lent comes from if there is no bank behind the system. In many protocols, liquidity is provided by the users themselves. In exchange for making their assets temporarily available to the protocol, they can earn a financial return, while other participants use those funds to obtain financing. The entire process is managed automatically through smart contracts.
A particularly important role is played by stablecoins, cryptocurrencies whose value is pegged to a traditional currency such as the US dollar or the euro. Assets such as USDC or EURC allow users to operate on blockchain networks without being exposed to the price volatility of Bitcoin or Ethereum, making them the primary tool for managing liquidity within the DeFi ecosystem.
Their usefulness extends well beyond investing. An increasing number of payment cards are now linked to wallets, allowing users to pay at any merchant that accepts Visa or Mastercard. For the merchant, the payment is still received in euros or the local currency, while for the user, the funds can come directly from their wallet.
Beyond cryptocurrencies
If stablecoins represent the present of DeFi, asset tokenization may define its future. Tokenization consists of digitally representing real-world assets on a blockchain, including stocks, bonds, real estate, or shares in investment funds.
This process has the potential to simplify many financial operations, reduce administrative costs, and make certain investments more accessible. As a result, rather than viewing DeFi as a threat, many financial institutions are already developing projects based on this technology. Some of the world’s leading banks and asset managers are experimenting with tokenized assets and blockchain-based payment systems, convinced that they can improve the efficiency of a wide range of financial services.
A transformation that has already begun
Decentralized finance still faces significant challenges, including regulation, protocol security, and user protection. Even so, its rapid evolution over recent years demonstrates that blockchain is no longer simply a technology associated with cryptocurrencies. It is increasingly becoming a financial infrastructure with a growing range of real-world applications.
In a few years’ time, many people may use blockchain-based financial services without even realizing it. Just as we send emails today without thinking about the Internet protocols that make them possible, DeFi is likely to become an invisible layer of technology supporting an ever-growing part of the global financial system.
11Onze is Catalonia’s fintech community. Open an account by downloading the El Canut app for Android or iOS. Join the revolution.
If you would like to learn more about this topic, we recommend:
 Finances
DeFi: “No central authority controls them”
5 min readNew technologies have entered the financial sector with...

You get home, look up at the ceiling and see a large damp patch that wasn’t there yesterday. This scene, as common as it is unpleasant, is usually the first sign of a water leak from the flat above. In fact, according to insurance companies, water damage is one of the most common types of damage in homes, and it often originates from a fault outside the home itself.
In many cases, the problem is caused by a burst pipe, a damaged drain or a tap that has not been turned off properly. All in the neighbour’s home. And then the headache begins: finding the source, contacting the other party, assessing the damage and, above all, figuring out who should pay for what.
The first thing to do when faced with a leak is to locate the neighbour above as soon as possible and notify them of the issue. In cases like this, acting quickly can prevent further damage. If the leak is active, it is essential to immediately turn off the water supply to your home until a technician can repair the fault.
It is important to keep a record of everything: photographs, videos, conversations. Any evidence may be useful if the situation becomes complicated and a formal complaint needs to be made. It is also a good idea to check whether your home insurance includes legal defence cover, which can make the process much easier.
Am I entitled to compensation?
The answer is yes. Even if the issue comes from the flat above, you are entitled to compensation for the damage caused to your home. However, how this compensation is paid will depend, to a large extent, on whether your neighbour has insurance and on the terms of their policy.
In most cases, if your neighbour has home insurance, their company will be responsible for repairing the damage to your property. However, there are essential exceptions to bear in mind.
When insurance does not cover the damage
There are situations in which your neighbour’s insurance may refuse to accept liability. For example, if the leak was caused by a tap being left open, and you have been away from home for more than 72 hours, the company may consider this a case of negligence and reject the claim.
The same applies if there is evidence of obvious lack of maintenance in your neighbour’s home, such as a badly deteriorated installation that has never been checked. In these cases, the responsibility falls personally on the owner of the affected property.
Another common scenario is that of building works. If the leak is a direct consequence of renovation work in your neighbour’s home, the responsibility falls on the company or professional who carried out the work, and it is that person who must have civil liability insurance to cover the damage caused.
What if no one wants to pay?
Even if the person responsible for the leak does not have insurance, they are still legally obliged to cover the damage they have caused. They can do this by paying for the repair directly or by paying the bill if you have had to advance the cost.
But what if they refuse to do so? In this case, it is essential to have photographic evidence of the damage (photos, videos) and to request an expert report through your own insurance company, if you have one. This document will be key if it is necessary to take legal action.
If you have legal defence cover, you can ask the company to provide you with a solicitor to handle the formal claim. The usual procedure is to send a letter setting out the facts and requesting compensation or payment.
If there is no response or a refusal, the next step is to file a lawsuit. Legal proceedings in these cases are usually quick and straightforward, and often end with a ruling in favour of the injured party. If, however, the person responsible continues to refuse to pay, you can request enforcement of the ruling and proceed with seizure to recover the money.
A common but avoidable situation
Water damage is common, but that doesn’t mean it has to be a nightmare. Good communication with your neighbour, adequate insurance and a quick response can make the difference between an anecdote and a legal battle.
That is why it is essential to know your rights, review the terms of your policy and act decisively from the outset. When faced with a leak, there is no need to lose your cool… but there is also no need to sit idly by.
If you want to discover fair insurance for your home and for society, check 11Onze Segurs.