The scourge of crony capitalism
For many years, the Western economic model has been characterised by a system of crony capitalism based on the promiscuous relationship between politics and business. An endemic evil that affects, to a greater or lesser extent, the vast majority of countries.
Xavi Viñolas, 11Onze editor
Crony capitalism is a term used to describe a capitalist system in which business success depends on mutual favours between businessmen and politicians. These relationships often lead to government policies that benefit a few companies or individuals to the detriment of the interests of the public, which end up instrumentalised by the powers that be.
The use of political connections to secure preferential treatment or unfair advantage can take the form of public contracts, subsidies, or regulations and laws that favour a select group of companies or individuals. Commissions, bribes, and revolving doors from politicians to big business are part of the lexicon that accompanies this practice of nepotism and corruption, which, unfortunately, no longer surprises anyone.
In this context, economic activity does not follow the principles of a free market economy designed to serve the consumer with the best products, but to maintain the favour of political power through businesses or lobbies that corrupt public officials, generating inefficiencies, fostering oligopolies, slowing economic growth and eroding trust in the political class.
The 2008 global financial crisis is an excellent example of how collusion between financial institutions and governments can lead to risky and irresponsible practices by monopolies that control the market, causing economic devastation that taxpayers end up paying for by rescuing banks from bankruptcy with public money.
Political disaffection
One of the most serious consequences of widespread government corruption and abuse of power is that citizens become disengaged from the political process. The apathy and cynicism of a population, which sees public officials using their positions for their own benefit, manifests itself in low voter turnout and the destruction of the moral fibre of society.
If the lack of transparency and oversight weakens trust in government institutions and makes politicians unaccountable for their actions, it is difficult to convince citizens that social and economic improvements are achieved by putting into practice ethical values such as effort, hard work and honesty.
The lack of credibility associated with governments is compounded by a two-party political system, de jure or de facto, established throughout the Western world, which in many cases does not even favour two parties or political coalitions antagonistic to each other. On the contrary, it is often a matter of two political actors sharing power in a cyclical fashion, but with little difference in the implementation of policies that benefit the establishment that acts outside the institutions.
No information, no accountability
A free press is the cornerstone of democratic societies. It serves as a check on government power and promotes transparency and accountability. Without a free press, citizens would not have access to the information they need to make informed decisions and hold their leaders accountable.
Unfortunately, much of the media has become a mouthpiece for economic and political elites. Far from reporting on government actions or corporate malpractices, the journalistic narrative often contributes to their propaganda while whitewashing corruption, ensuring the impunity of elected officials.
This reveals an unwillingness to serve the public interest, preventing citizens from being aware of government actions that may involve conflicts of interest. This is a bleak picture that is unlikely to change unless civil society organises to empower citizens through information and education, enabling them to make decisions that guarantee their fundamental rights.
11Onze is the community fintech of Catalonia. Open an account by downloading the super app El Canut for Android or iOS and join the revolution!
The minerals that almost nobody knows… but everyone needs. In the spring of 2025, several European car manufacturers began to worry. Essential components needed to keep producing vehicles were at risk of no longer arriving. It was not a new oil crisis. Nor was it a semiconductor shortage. The source of the problem was a group of minerals that are virtually unknown to the general public but have quietly become one of the most powerful geopolitical weapons of the 21st century.
A few days later, China announced new export restrictions on certain rare earths and permanent magnets. The news made headlines in specialist media, but for many people it went largely unnoticed. Yet the move exposed an uncomfortable reality: much of the technology we use every day depends on materials that are, to a great extent, controlled by a single country.
A hundred years ago, global power was measured in barrels of oil. Today, it is increasingly measured in kilograms of minerals.
They are not rare. What is truly exceptional is knowing how to process them
The name is probably the first great misconception. Rare earths are not particularly scarce. Some of their seventeen chemical elements are actually more abundant in the Earth’s crust than copper. The problem is that they are rarely found concentrated in one place. Instead, they are scattered among other minerals, and separating them requires highly complex, expensive chemical processes with a significant environmental impact.
For years, Europe and the United States reached what seemed like a logical conclusion: importing these materials was cheaper than producing them. Mines gradually closed, many refining plants disappeared, and the industry steadily moved to Asia. Meanwhile, China was doing exactly the opposite.
Without attracting much attention, it invested in mines, refining technologies, chemical processing plants and the manufacture of the components that major Western companies would later buy. While others focused on cutting costs in the short term, Beijing was building an industrial strategy that now gives it an advantage that is extremely difficult to replicate. And this is where the great paradox that explains this entire story emerges. The most valuable resource is not the mineral itself. It is the knowledge required to transform it.
The mine is only the beginning of the story
When we think of a raw material, we usually picture an excavator digging rocks out of a mountainside. But in the case of rare earths, that is only the opening scene of a much longer story.
Next comes refining, where the seventeen chemical elements are separated one by one. They are then transformed into specialised alloys and, later, into extraordinary permanent magnets capable of generating enormous power while taking up very little space. Only then do they reach the factories that manufacture electric motors, industrial robots, wind turbines, satellites and mobile phones.
When you unlock your smartphone with facial recognition, listen to music through wireless earbuds or use an artificial intelligence tool, you probably never think about it. Yet behind these everyday actions lies an industrial supply chain that begins in a mine located thousands of kilometres away. It is an invisible reality. And that is precisely why it is so easy to forget.
The tiny elements powering the world’s biggest technologies
Very few raw materials are as discreet and yet as indispensable as rare earths.
Neodymium makes it possible to manufacture the magnets used in electric vehicle motors. Dysprosium ensures those magnets retain their performance at extremely high temperatures. Europium is used in displays and lighting systems, while lanthanum is found in batteries, cameras and optical components.
Without these materials, many modern wind turbines, advanced medical equipment, satellites, lasers, radar systems and defence technologies simply would not exist.
The figures help put their importance into perspective. An electric vehicle requires several times more rare earths than a conventional car, while a single offshore wind turbine can contain hundreds of kilograms of magnets made from these materials. Even the world’s most advanced fighter aircraft depend on them.
Artificial intelligence, which we often think of as being purely about software, also begins here. The data centres that train models such as ChatGPT require thousands of processors, electronic components and cooling systems built through an industrial supply chain in which rare earths play an essential role.
Algorithms do not emerge out of nowhere. Before algorithms comes industry. And before industry come the minerals.
China understood the game before anyone else
For decades, the Western world looked the other way. Producing rare earths was expensive, environmentally damaging and attracted little political interest. China, however, saw them as a strategic opportunity.
Today, it is not only one of the world’s leading producers. Its greatest advantage is that it controls much of the global refining capacity and the manufacturing of the permanent magnets used by companies around the world. This dominance allows China to influence industries as diverse as automotive manufacturing, renewable energy, defence and consumer electronics.
When Beijing announces export restrictions, markets react because they know replacing this industrial capacity is not a matter of months, but most likely years. The West has discovered that outsourcing an industry for thirty years is far easier than rebuilding it.
The new war is no longer fought only over oil
This is why the United States, Canada, Australia, the European Union and other countries are accelerating mining projects, investing in new refining facilities and seeking agreements with strategic partners. Investment in recycling is also increasing, as the electronic devices we discard today could become an important source of critical materials tomorrow.
The challenge is no longer simply about manufacturing more electric cars or more wind turbines. It is about deciding who will control the industries of the future. That is why rare earths are no longer merely a geological issue, they have become a matter of national security.
Why does all this affect your savings?
Major geopolitical shifts eventually reach the everyday economy. When tensions arise in the supply of critical minerals, manufacturers face higher costs, industrial projects are delayed and companies are forced to revise their forecasts. Ultimately, these disruptions can be reflected in financial markets, inflation and the prices of the products we buy.
Understanding this dependence does not mean you should invest in rare earths. It means gaining a better understanding of why technology companies, car manufacturers and industrial groups react so strongly to political decisions that, at first glance, seem to take place on the other side of the world. Natural resources continue to shape the global economy. The only thing that has changed is which resources have become the most valuable.
The future is also mined from the earth
During the 20th century, oil largely determined the fate of economies and international conflicts. In the 21st century, that influence is increasingly shared by far less familiar, yet equally indispensable, resources. Without rare earths there would be no electric vehicles, no wind turbines, no industrial robots, no satellites and no artificial intelligence.
The next time you unlock your smartphone, listen to music through wireless earbuds or ask an AI for an answer, remember that behind that technology lies a supply chain that begins in a mine, continues in a refining plant thousands of kilometres away and ultimately helps shape the global economy.
Algorithms may seem to be the engine of the future. But without these seventeen chemical elements, the future simply would not start.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.
Una dècada després que la República Popular de la Xina posés en marxa la Iniciativa del Cinturó i Ruta de la Seda amb l’objectiu de desenvolupar una infraestructura global de comerç i cooperació internacional, el projecte s’enfronta a nous reptes geopolítics que marcaran el seu futur.
La Iniciativa del Cinturó i la Ruta de la Seda o Belt and Road Initiative (BRI, per les seves sigles en anglès), també coneguda com la Nova Ruta de la Seda, es va posar en marxa el 2013 pel president Xi Jinping. Es tracta d’un dels projectes d’infraestructures més ambiciosos mai concebuts, i, originalment, estava pensat per a incrementar el comerç i cooperació econòmica entre l’Àsia Oriental i Europa. Durant els últims deu anys el projecte s’ha ampliat a Àfrica, Oceania i Amèrica Llatina, incrementant exponencialment la inversió en infraestructures.
A més, en aquesta estructura logística s’hi suma la ruta de la seda marítima que inclou ports i infraestructura costanera des del litoral occidental de la Xina a Europa, l’Índia, Àfrica, el Pacífic i Llatinoamèrica. La qual cosa és d’una importància cabdal tenint en compte que la Xina té actualment 95 ports i sis d’ells figuren en el rànquing dels 10 més importants del món.
Amb l’objectiu de connectar al 65% de la població i a un terç del PIB mundial amb la Xina mitjançant la creació d’una xarxa de rutes marítimes i enllaços terrestres, ha captat l’atenció del món pel seu abast global i les seves implicacions econòmiques, polítiques i socials. El govern xinès va anunciar que la iniciativa significa “il·luminar una nova era de globalització”, i facilitarà una “època d’or del comerç que beneficiarà a tots”.
Al juliol d’aquest any, les inversions totals en el marc del projecte van superar el bilió de dòlars, fins al punt de competir directament amb el Fons Monetari Internacional (FMI). Aquests diners provenen principalment del Nou Banc de Desenvolupament, del Fons de la Ruta de la Seda i del Banc Asiàtic d’Inversió en Infraestructures (BAII).
Un imparable món multipolar
Tot i que la iniciativa ha estat elogiada per a fomentar el desenvolupament econòmic i la cooperació entre països, oferint unes condicions beneficioses per totes les parts que no es donaven amb el monopoli dels poders occidentals, també han sorgit algunes veus crítiques. Alguns països participants han expressat preocupació sobre la transparència dels projectes, dubtes per si podran fer front a la càrrega de deute o de quina serà la dependència amb la Xina en cas que no puguin tornar els préstecs.
Una gran part d’aquestes crítiques i pressió perquè certs països es neguin a col·laborar amb el gegant asiàtic venen per part dels Estats Units, que veu com s’esvaeix cada cop més la seva hegemonia com a poder econòmic i geopolític global en favor d’altres actors emergents, com Rússia i la Xina, que volen mantenir la seva sobirania lliure dels tentacles d’Occident.
L’èxit del projecte el converteix en una eina perfecta per expandir, encara més, la influència política i econòmica de la Xina, tenint accés preferent a nous mercats i recursos naturals fins ara dominats quasi exclusivament pels poders occidentals, que veuen amb desesperació com els cicles econòmics i els mercats financers se centren cada vegada menys amb ells.
En aquest context, l’última cimera dels BRICS, on s’ha anunciat que sis països més s’uniran al bloc econòmic, ha creat una gran expectació. Tanmateix, ha posat de manifest la dificultat d’unificar interessos tenint en compte les sensibilitats de tots els estats membres. L’expansió del BRI pot ser el punt d’unió que tapi les esquerdes, especialment entre els països africans que han demanat que la Xina passi de la construcció d’infraestructures a la industrialització local i d’una Índia també interessada a finançar projectes emblemàtics a països en vies de desenvolupament del sud global, com a contrapartida a Occident.
11Onze és la fintech comunitària de Catalunya. Obre un compte descarregant la super app El Canut per Android o iOS. Uneix-te a la revolució!
Our relationship with financial institutions has changed a lot in recent years. Have you had a trusted manager for years and in the same branch? A person who accompanied you from the moment you opened your first account to the moment you took out your mortgage? The time when a customer could go to a branch and feel involved is long gone.
The current situation is that the customer, in general, is deeply dissatisfied with the financial system. The system has evolved a lot in recent years and has not known how to (or wanted to) explain this change to the customer. Thus, year after year, the customer has only seen how the institution of which he or she was a part changed shape, colours and staff without really understanding what was going on. The new fintechs are picking up on this unease and are born precisely from the perspective of giving customers back what they lost years ago: a relationship of trust with the financial institution.
Digitalisation fosters a new interaction
We come from a society marked by social interaction, and the irruption of new technologies has revolutionised everything: another form of communication is possible, including with financial institutions. This change in mentality can be interpreted in many ways, but, if used correctly, the benefits can be manifold for customers and institutions.
To speak of financial digitalisation is to speak of fintech. In terms of communication, they have a lot to say. They are the first financial institutions to change the way they communicate with customers. They have brought about an entirely digital system of interaction, which has left traditional banking lagging behind.
At first glance, it may seem that many customers, especially those who were not born in the digital era, will not embrace this change, no matter how many advantages it brings them, and that they will therefore maintain face-to-face and direct service as their main means of contact. But to what extent can this be an advantage for them?
A digital experience with human quality
The first thing a user looks for when accessing a financial institution is instant attention. No one wants to spend the morning standing in endless queues only to be dealt with in a matter of minutes. Every problem requires an investment of time on both sides. A fintech like 11Onze, which has already been born with digitalisation, will maintain this principle in all interactions with the user, who will have the tools to ask and get an answer to any query. Automatic chats have made it possible to improve the experience in this aspect, providing the user with information based on keywords. Some even go further and offer personal and human attention from these chats. Email or telephone support are the other two ways.
Another requirement is quick understanding, and this is where machines still have room for improvement. For most customers, receiving human telephone support will be more satisfactory than a call with a robot, where a lot of time can be wasted without getting any concrete answer. Although digital entities are working to improve in this aspect, it will be the fintechs with personalised customer service that will gain ground.
Along the same lines, branch service also allows users to have the certainty that they will be able to clear up any doubts they may have. This is a point that is not always satisfactorily resolved, as it requires an investment of time for the customer that not all institutions are currently willing to offer. If they do, it is not always with clarity and transparency.
In this sense, fintechs are still committed to personal and personalised attention, placing special emphasis on this second point. Being aware that each person has different needs and concerns and requires more or less time to acquire information. Respecting each person’s time is a key value that differentiates a good experience from a bad one, both in the digital environment and in person.
Finally, the last and most decisive factor that a customer looks for in an office is trust; knowing that there is a person who will inform us properly and will work for us with honesty and professionalism. But what if all the employees in the branch or in the entire institution were like your favourite manager, and what if they all looked after the customer’s needs and informed him or her honestly and professionally? Then a personal assignment would no longer be necessary, because the trust would not be with a single person but with an entity. This is the real change in the mindset of fintech.
Customer experience marks the future
In fintech, customer service time does not prevail, nor does customer allocation, sales pressure or the number of customers served. In fintech, attention is constant and permanent, from any channel or device. People prevail over products; their needs prevail over those of the entity; and work is done every day to evolve and improve this experience. To bring the financial world closer to users and offer them, for the first time, everything they may need at a single click.
In short, a fintech means going back to the origins of financial institutions and offering the customer a relationship of trust based on respect and mutual benefit. A relationship to which all the technological advances and facilities that this can offer are added, and those face-to-face practices that, instead of making life easier for the customer, complicate it, are subtracted. Convenience is just a click away. Welcome to the new financial era.
11Onze is the community fintech of Catalonia. Open an account by downloading the app El Canut for Android or iOS and join the revolution!
The International Monetary Fund was founded to promote international monetary cooperation, facilitate global trade and contribute to financial stability. Over time, however, its mandate was expanded to provide “support” to economies experiencing financial difficulties, and it has evolved into a tool at the service of neoliberal interests.
On 15-20 April, the annual spring meetings of the International Monetary Fund (IMF) and the World Bank are being held in Washington. The official purpose of these meetings is to bring together efforts to end extreme poverty and promote shared prosperity.
This international body was established in 1944 to promote monetary cooperation, facilitating international trade and contributing to financial stability. Since its founding, it has sought to eliminate restrictions that hinder the expansion of world trade and exchange rate stability and avoid competitive currency devaluations between countries.
With the end of fixed exchange rate systems after the gold standard was abolished during the 1970s, its role changed. The advent of neoliberalism in the US and Western European economic policies meant a new role for the IMF, which began to finance nations with trouble paying their debts and balancing their payments.
A lifeline that brings civil unrest and social misery
IMF financial assistance is not free, as is well known, loans are accompanied by strong austerity which disproportionately affects the poorest sectors of the population and often ends up benefiting the elites.
The IMF’s usual mechanism for this is the imposition of conditionalities, such as loan forgiveness for countries needing balance of payments support, or, as in the case of Pakistan, weapons transfers into Ukraine. In other words, the IMF is often used as yet another foreign policy tool of Western corporatocracies.
The conditions imposed on debtor countries open their economies to the introduction of foreign capital, corporations, and investors. This is done by privatising public services and selling off the crown jewels of the countries receiving this “aid”, especially their natural resources and land.
As a general rule, the IMF demands that governments reduce public spending, raise taxes and implement reforms to reduce their debt-to-GDP ratio. Cutting social subsidies on fuel and food or reducing public investment in hospitals, schools, and roads becomes the “new normal”.
These draconian austerity measures provoke demonstrations and revolts among the affected populations, known as “IMF riots”. A term coined to describe the waves of protests that took place in developing countries during the 1980s and 1990s, and which perfectly defines the consequences of the actions of a financial firefighter who starts fires.
The economic crises in Mexico and Greece and subsequent IMF bailouts highlighted the negative role the IMF has played in recent years, nonetheless, the widely documented record of its interventions over the last 50 years has been more than dismal. Although humanitarian organisations such as Oxfam and CAFOD never stop denouncing that the IMF’s “austerity campaigns” severely harm poor countries and that it has played a “devastating” role in the global debt crisis, the international lending agency shows little sign of changing its course.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
Despite having the highest average salary in history, the average Spanish wage is almost 450 euros lower than the EU average and continues to have one of the highest rates of job insecurity in Europe.
Inflation has eaten into wage increases and reduced citizens’ purchasing power to an extent not seen for thirteen years. This economic mess is not unique to Spain, but it is exacerbated by Spain’s low wage levels, an endemic problem that has been dragging on for decades.
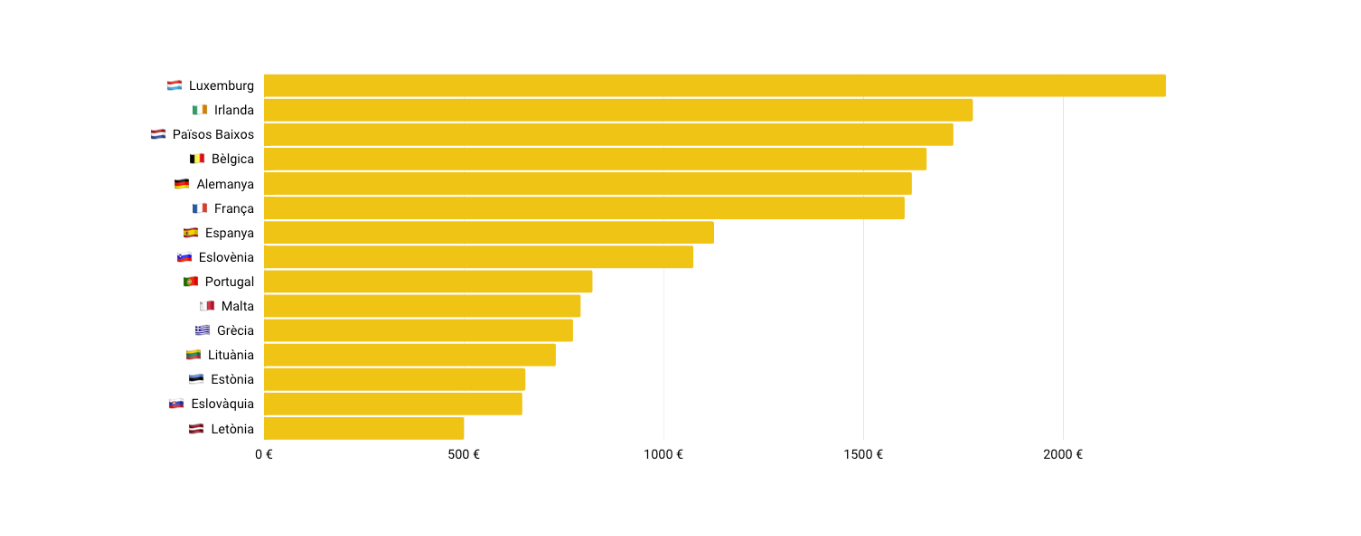
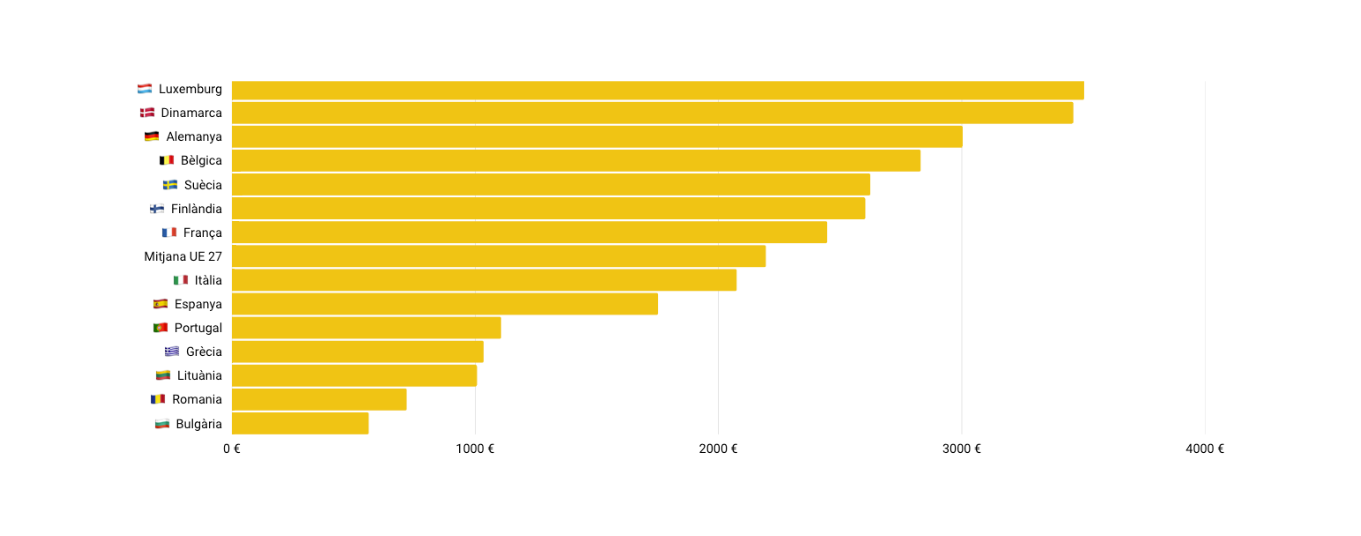
Although the latest unprecedented rise in the minimum wage has reduced the gap, both the average gross wage (1,126 euros) and the Spanish minimum wage (1,751 euros) are among the lowest in the European Union, 20.2% lower than its European partners.
Within the Western bloc, with average wages above 2,500 euros per month, Spain is at the bottom, followed by Portugal (1,106 euros) and Greece (1,034 euros). There are wide differences with countries such as France (2,446 euros), Belgium (2,830 euros), the Netherlands (2,883 euros) and Germany (3,303 euros). Spain only does well when compared with the less developed countries of Eastern Europe.
Minimum Wage EU
Source: Addeco (INE and Eurostat)
Average Salary EU
Source: Addeco (INE and Eurostat)
Low productivity and high unemployment
The precariousness of employment for a large part of the population in the face of the business world is an endemic historical evil in Spain. The insecurity created by the fear of unemployment makes workers accept low wages and working conditions that would be unthinkable in other developed countries.
When, after the sanitary crisis, the media spoke of “The Great Resignation“, referring to the fact that in many Western countries many employees were rethinking their priorities, giving up their usual jobs to get better ones, from here, with more than three million unemployed and salaries equivalent to a Western European China, we looked at it as if they were talking about another planet.
The high number of part-time and temporary full-time workers means that many employees do not receive proper training and do not maintain a professional career, which negatively affects productivity. This is exacerbated by the heavy weight of the service sector in the Spanish economy, which has little added value, low wages and is prone to outsourcing labour activity. The composition of our productive fabric has suffered a gradual deterioration in sectors that historically had better salaries.
Added to this is another trend that is prevalent in Catalonia and in Spain, but which is not observed in the developed European bloc: the enormous wage gap between younger and older employees. The low salaries received by the youngest employees, who will have to sustain the economy in the future, jeopardise the economic support of the country and a solidarity-based pension system.
If you want to discover the best option to protect your savings, enter Preciosos 11Onze. We will help you buy at the best price the safe-haven asset par excellence: physical gold.
For more than a century, capitalism followed an apparently simple logic: those who provided the capital were usually the same people who made the decisions. Today, that relationship has been turned upside down. Millions of people still own their savings, but their management has become concentrated in very few hands. How did this transformation take place? And what does it tell us about twenty-first-century capitalism?
At the end of every month, Marc receives his salary. Like millions of workers around the world, a small portion of his income is automatically transferred into his pension plan. It is an almost mechanical gesture. The money disappears from his current account and becomes part of a savings fund that, in theory, will support him when he retires.
Marc does not think much more about it. He trusts that someone will invest that money wisely so that, over the years, it will grow in value. What he probably does not realise is that part of his savings will eventually be invested in companies such as Apple, Microsoft, Amazon, Nvidia or Coca-Cola. And there is another detail that he would hardly imagine: those shares will be managed alongside the savings of millions of people living on the other side of the world.
Without even knowing it, Marc takes part every month in one of the most profound transformations capitalism has undergone over the past half century. For decades, economic power had a very clear face. When people spoke about the automobile industry, it was impossible not to think of Henry Ford. Oil immediately brought John D. Rockefeller to mind. The Agnelli family represented Fiat, and even today Amancio Ortega remains closely associated with Inditex. The great entrepreneurs not only owned a significant share of their companies; they also ran them, assumed the risks and decided the direction in which they would move.
That model has not disappeared entirely. There are still major corporations controlled by their founders or by entrepreneurial families. But, without dramatic headlines or apparent revolutions, the centre of gravity of capitalism has gradually shifted. If today we look at the largest shareholders of Apple, Microsoft, Amazon, Alphabet, Coca-Cola or JPMorgan, we will discover that the same three names appear over and over again: BlackRock, Vanguard and State Street.
It is far too frequent a coincidence to be accidental. Yet its explanation has nothing to do with the conspiracy theories that often circulate on the internet. On the contrary, it is the result of a financial revolution that began with a surprisingly simple idea.
The man who challenged wall street
Our story takes us back to 1975. John Clifton Bogle had just founded a small asset management company called The Vanguard Group after being dismissed from Wellington Management. Rather than trying to prove he was better than the rest of Wall Street’s professionals, Bogle had reached a far more radical conclusion: perhaps the real problem was trying to prove it in the first place.
For years, he had watched leading fund managers devote enormous resources to identifying the companies that would deliver the highest returns. They hired analysts, examined balance sheets, visited businesses and developed sophisticated financial models in an attempt to outperform the major stock market indices. Yet, year after year, reality proved stubborn. Once fees had been deducted, most of them achieved results that were equal to—or even worse than—the market they were trying to beat.
Bogle decided to turn that logic upside down. Instead of trying to identify the best company of the future, he proposed buying them all.
The idea, which many analysts ridiculed at the time, would eventually become one of the most influential innovations in the history of finance. Today, almost fifty years later, Vanguard manages close to 10 trillion dollars in assets, an amount equivalent to several times Germany’s gross domestic product. It was not merely the success of one company.
It marked the beginning of a completely new way of understanding investment.
When investing stopped being a game for experts
Bogle’s idea was revolutionary because it dramatically simplified an activity that had previously seemed reserved for professionals. Imagine someone walking into a fruit shop determined to buy the very best fruit available. They can spend a long time selecting each individual piece they believe to be the finest, or they can choose a basket that already contains a balanced selection of seasonal fruit. Not every piece will necessarily be outstanding, but neither will the result depend on having made the perfect choice every single time.
Index funds work according to exactly the same philosophy. Instead of trying to predict which companies will grow the most, they buy every company that forms part of a particular stock market index. If the index is the S&P 500, the fund purchases shares in the five hundred largest companies in the United States. If it tracks the MSCI World Index, it invests simultaneously in thousands of companies spread across dozens of countries.
The result is a highly diversified portfolio, with costs far lower than those of traditional active management and which, according to numerous studies, tends to outperform a large proportion of actively managed funds over the long term.
This philosophy eventually spread far beyond Vanguard. Over time, virtually the entire financial industry began developing similar investment products.
The arrival of ETFs accelerated the revolution
The second major transformation arrived in the 1990s with the popularisation of ETFs, short for Exchange Traded Funds. Despite their technical name, the way they work is remarkably simple. An ETF is a fund that is traded on the stock exchange just like a share. When an investor buys a unit of one of these funds, they are not purchasing a single company, but rather a small share of a basket that may contain hundreds or even thousands of companies.
This small change had enormous consequences. For the first time, anyone could invest in a highly diversified portfolio, at very low cost and without having to follow the markets on a daily basis. What had once been reserved for wealthy investors became accessible to virtually any saver.
The figures illustrate the scale of the phenomenon. While ETFs represented an almost insignificant market at the end of the 1990s, they now manage more than 15 trillion dollars worldwide and continue to grow at a faster pace than many other financial products.
Three asset managers that grew alongside the world’s savings
While Vanguard was consolidating its commitment to index investing, another company was embarking on a very different path. In 1988, Larry Fink founded BlackRock after losing almost one hundred million dollars on a mortgage bond transaction while working at First Boston. That episode left him with a conviction that would define his entire career: before seeking returns, you must first understand risk.
That philosophy would eventually turn BlackRock into the largest asset manager on the planet. Today it manages approximately 11.6 trillion dollars, a figure so vast that only the United States and China generate a larger annual GDP.
State Street, for its part, had a much longer history. Founded in 1792, it played a decisive role in this revolution when, in 1993, it launched the first major modern ETF linked to the S&P 500. That product definitively demonstrated that investing in an index could be as simple as buying any other publicly traded share.
None of these companies set out to become the owners of global capitalism. Their objective was far more modest: to manage as efficiently as possible the money entrusted to them by millions of people. Yet precisely because millions of people began making the same decision, the outcome became extraordinary. Today, whenever we examine the shareholder registers of the world’s largest multinational corporations, their names appear over and over again. And this is where the most surprising part of the story begins.
The money is still yours. The influence, not so much.
When readers discover that BlackRock, Vanguard and State Street are among the largest shareholders of virtually every major Western corporation, it is easy to reach the wrong conclusion: that these three firms are the true owners of global capitalism. The reality is far more nuanced.
The owners are still millions of anonymous individuals. They are workers like Marc, who contribute part of their salary every month to a pension plan; families who save through an investment fund; universities, insurance companies, public institutions or small investors who purchase an ETF through their bank. All of them remain the ultimate owners of their savings.
What these firms do is something different. They manage those savings. The distinction may seem subtle, but it is essential to understanding how today’s financial system works. When a property owner hires a manager to administer a building, they do not cease to own it. Exactly the same applies to savings. The money still belongs to the investors, but its management is delegated to specialised institutions that decide how to allocate it across thousands of different assets.
This explanation dismantles many of the simplistic narratives that often circulate on social media. BlackRock, Vanguard and State Street have not purchased all the world’s major companies with their own money. They have grown because hundreds of millions of people around the world have independently reached the same conclusion: it is more efficient to delegate the management of their savings to large, diversified asset managers than to try to pick the winning companies themselves.
But that answer immediately raises another question. If the money still belongs to the investors, who exercises the rights attached to those shares?
The separation between ownership and power
This is, perhaps, the most profound transformation capitalism has undergone over the past few decades.
Throughout much of the nineteenth and twentieth centuries, ownership and power generally went hand in hand. Major shareholders were also the people who ran companies, appointed boards of directors and determined their major corporate strategies. Capitalism maintained an almost direct relationship between those who provided the capital and those who made the decisions. Today, that relationship is far more complex.
When an asset manager purchases shares on behalf of its clients, it also assumes, in most cases, the exercise of the voting rights associated with those holdings. This means voting at shareholders’ meetings, expressing positions on executive remuneration policies, approving the appointment of new board members and taking a stance on major strategic decisions.
This does not mean that BlackRock decides what the next iPhone will look like, or that Vanguard chooses which company Microsoft should acquire. Those responsibilities still belong to each company’s executive management and board of directors.
Their influence is much less visible, but also far more far-reaching. It can be seen in the way corporate governance is understood, in transparency standards, in sustainability policies and in the rules that simultaneously affect hundreds of major corporations.
It is a discreet form of power, exercised almost entirely away from the public spotlight, yet one that acquires an extraordinary dimension when the same asset manager holds stakes in thousands of companies across the world. Managing the savings of millions of people inevitably also means managing a significant portion of the voting rights attached to those savings. And doing so requires a technological capability that, only a few decades ago, would have seemed like science fiction.
Aladdin: The technology behind the management of trillions of dollars
Few tools have sparked as much curiosity as: Aladdin.
The name may evoke the character from the Arabian tales, but in reality it refers to one of the most sophisticated risk management platforms in the financial world. Larry Fink developed it with a very clear idea after losing almost one hundred million dollars in a single transaction during the early years of his career: before taking any risk, you must first understand it. That philosophy continues to define BlackRock today.
Aladdin does not buy shares or make decisions on its own. Its role is far less spectacular, yet infinitely more useful. It analyses millions of data points, simulates economic scenarios, calculates risks, identifies vulnerabilities and helps portfolio managers understand how an investment portfolio might react to rising interest rates, a trade war, an energy crisis or a global recession.
According to BlackRock itself, the platform supports the management of more than 21 trillion dollars in assets, used not only by BlackRock but also by banks, insurance companies, sovereign wealth funds and financial institutions around the world.
It is understandable that an infrastructure of this scale has fuelled all kinds of myths. Yet the reality is far less sensational than is often claimed. Aladdin does not control the financial markets. What it actually does is something much more pragmatic: it helps professionals make decisions in a financial system that moves amounts of money almost impossible to comprehend.
The debate that concerns universities and regulators
This phenomenon has not gone unnoticed. For years, economists, legal scholars and competition authorities have been analysing the consequences of this concentration in the management of global savings. The concept at the centre of much of the debate is common ownership—the presence of the same large institutional shareholders in companies that compete with one another.
The question is a legitimate one. If the same asset managers simultaneously hold significant stakes in the world’s leading airlines, banks or technology companies, could this reduce the incentives for those companies to compete more aggressively?
In 2018, economists José Azar, Martin Schmalz and Isabel Tecu brought international attention to this debate through a study of the U.S. airline industry. Their conclusions triggered an intense academic controversy that remains unresolved today.
Since then, institutions such as Harvard University, the National Bureau of Economic Research (NBER), the U.S. Securities and Exchange Commission (SEC) and the Federal Trade Commission (FTC) have examined the issue from different perspectives. Some studies suggest that common ownership could affect competition in certain sectors, while others argue that the available evidence is still not robust enough to support such a conclusion.
This lack of consensus does not diminish the importance of the debate. Quite the opposite.
It demonstrates that we are facing a new, complex and still evolving phenomenon that forces us to rethink traditional concepts such as ownership, corporate control and even competition itself.
A revolution that almost nobody saw coming
When John Bogle created Vanguard in 1975, he could hardly have imagined that his idea would end up transforming global capitalism. His objective was far more modest: to offer small investors a more efficient, less expensive and more transparent way to invest their savings. In that respect, his revolution has been an extraordinary success.
Never before had it been so easy to invest in the world’s leading companies.
Never before had investment costs been so low. And never before had so many small savers been able to participate in the growth of the global economy without needing substantial wealth.
Yet every revolution produces unexpected consequences. As millions of people delegated the management of their savings, that management gradually became concentrated in the hands of a very small number of institutions. Not because there was a preconceived plan, but because the very mechanisms that made investing more efficient also favoured economies of scale.
It is this paradox that defines much of contemporary capitalism. Ownership has become more democratic than ever before. Management has become more concentrated than ever before. This is neither good news nor bad news in itself. Above all, it is a reality that must be understood before it can be judged. Perhaps, a few decades from now, historians will explain this transformation with the same naturalness with which they now explain the Industrial Revolution or the birth of the modern corporation.
Because, almost silently and with hardly any headlines, capitalism has changed one of its most fundamental rules.
The owners are still millions of ordinary people like Marc. But the hands managing an ever-growing share of their capital are becoming fewer and fewer.And this is where the great question that is likely to define the coming years begins. The question is no longer who owns the world’s largest companies. The question is far more profound.
Who makes decisions on behalf of the owners?
11Onze is Catalonia’s fintech community. Open an account by downloading the El Canut app for Android or iOS. Join the revolution.
The stock market performance of large US technology companies has been stellar in recent years. These stocks, driven by the new AI paradigm, have posted record profits, yet their end markets are consolidating, calling into question the sustainability of their long-term growth profile.
In the stock market world, Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla are known as the “Magnificent Seven” of technology. These companies account for more than 25% of the S&P 500 and more than half of the Nasdaq 100. In addition, five of the seven are part of the exclusive “billion dollar club”, companies with a market capitalisation above $1 trillion, with Nvidia being the most recent entry.
- Alphabet: Google’s parent company’s profits increased by 23% in 2023, with a capitalisation of $1.6 trillion and a cumulative increase of 141% over the past five years.
- Amazon: The e-commerce platform founded in 1994 by Jeff Bezos has a market capitalisation of almost $1.8 trillion and its shares have appreciated by more than 2000% in the last ten years, 200% per year on average.
- Apple: Last year, Apple surpassed $3 trillion in market capitalisation for only the second time in its history and has seen a 250% increase in its stock market performance over the past five years.
- Meta: The company that owns Facebook, Instagram and WhatsApp started 2024 by setting a record, increasing its value by $204.5 billion in one day. It closed 2023 with revenues of $134.902 billion and currently has a capitalisation of $1.3 trillion.
- Microsoft: Last Wednesday, the capitalisation of the corporation founded by Bill Gates and Paul Allen reached the $3 trillion mark for the first time. Microsoft shares have appreciated by 66% in the last twelve months.
- Nvidia: As the leading supplier of chips specifically designed to train and run AI applications, this company’s stock market performance has been spectacular. Nvidia shares are up 243% in the last 12 months and 60% since the beginning of the year.
- Tesla: Elon Musk’s company revolutionised the electric vehicle industry and has significant competitive advantages thanks to its manufacturing processes and software development using artificial intelligence. Although it has started 2024 by losing about a quarter of its market capitalisation, it has seen an 829% increase in market performance over the past five years.
These tech giants not only stand out in terms of market capitalisation, but are leaders in new technologies such as artificial intelligence, cloud computing, and next-generation software development. A common differentiator among these companies is their ability to collect vast amounts of customer data and harness the power of AI.
Will the returns continue to be magnificent?
When analysing the future of the magnificent seven it should be noted that while there are certain similarities in the services provided between Alphabet, Amazon and Microsoft – whether we are talking about AI chatbots, software-to-cloud services or advertising – there are also huge differences between them. These differences are even more evident if we refer to Meta, focused on social networks, Tesla, in electric vehicles, or Apple, regarding smartphones.
It is therefore a heterogeneous group that is united by the common denominator of a solid business approach and growing areas. That said, some market analysts believe that the spectacular stock market performances of the Magnificent Seven are numbered. In a note entitled “R.I.P. the era of the Magnificent Seven”, Mike O’Rourke, senior market strategist at Jones Trading, argues that the group’s dominance of the stock market is coming to an end.
Whether we look at the stagnating demand for smartphones and slowing sales of electric cars, or the diversification of AI technologies, their markets are maturing and consolidating. Add in the problems of the Chinese economy, economic sanctions due to geopolitical interests and increased competition, and O’Rourke notes that the Magnificent Seven will continue to be very influential in the market, but that “they will start to cancel each other out in terms of performance, rather than all moving in the same direction”.
11Onze Recommends Bitvavo, cryptocurrency trading made easy, safe and at a good value.
Spain is not the country that collects the most taxes, yet millions of taxpayers perceive its tax authority as one of the toughest in Europe. Why? The answer depends not only on taxes, but also on wages, self-employed workers, bureaucracy and the level of trust citizens place in the public administration.
When taxes are discussed, the debate is often oversimplified. Some argue that Spain is a tax hell, while others point out that France, Denmark or Belgium collect even more through taxes and social security contributions. Both statements are true. Yet both are incomplete. A tax authority cannot be judged solely by the amount it collects, but also by the effort it demands from taxpayers and the way it treats them.
Spain collects less than many of its neighbours
If we look only at the tax burden—that is, the total of taxes and social security contributions as a percentage of GDP—Spain does not rank among Europe’s highest-tax countries. According to Eurostat, France, Denmark, Belgium, Austria and Finland all have a higher tax burden than Spain. Spain generally stands several percentage points below the countries that top this ranking.
These figures should settle the debate. But they do not. Despite having a lower tax burden than many other European economies, the widespread perception is that Spain’s Tax Agency is particularly tough. If objective data do not explain this feeling, then the answer must lie elsewhere.
The problem is not how much we pay, but the effort it requires
Comparing taxes without comparing wages is one of the most common mistakes in the fiscal debate. Paying a given percentage in taxes does not have the same impact when the average salary exceeds €55,000 a year as it does when it barely reaches €30,000.
This is what economists refer to as the tax effort. It measures not only the tax burden itself, but also the economic sacrifice it represents for the taxpayer. And this is precisely where Spain begins to differ from much of Northern Europe.
OECD data show that average Spanish wages remain well below those of Germany, the Netherlands, Denmark or France. This means that a similar tax burden can be far more difficult for a Spanish household to bear than for a German or Danish one.
In other words, the issue is not simply how much taxpayers pay. It is also how much they have left once they have paid.
The tax wedge: the great invisible tax
There is one figure that often goes unnoticed, yet explains better than any other the difference between the real cost of employing a worker and the salary that ultimately reaches that worker’s bank account. The OECD calls it the tax wedge.
The tax wedge is the difference between the total labour cost paid by the employer and the employee’s net salary after taxes and social security contributions have been deducted. The larger this gap, the higher the tax burden on labour.
Spain does not top the European ranking, but neither does it occupy the lower positions. What is particularly significant is that this burden falls on wages that remain lower than those of many Central and Northern European economies. This reinforces the perception that a substantial share of the value created through work is absorbed by the tax system before workers even receive their income.
This phenomenon also affects business competitiveness. A Spanish company may bear a labour cost that is considerably higher than the salary ultimately received by the employee, making both new hiring and wage increases more difficult.
The spanish self-employed worker: the best example for understanding the difference
If there is one group that perfectly illustrates the perception of the tax system’s toughness, it is the self-employed. Spain has reformed its Special Regime for Self-Employed Workers (RETA) in recent years to align social security contributions more closely with actual earnings. Even so, the system continues to require many professionals to pay a monthly contribution regardless of how their business performs.
This detail is important. A professional may go through several months with very little turnover and still be required to pay mandatory social security contributions. The issue is not only the amount itself, but also the rigidity of the system. When this model is compared with those of other European countries, significant differences emerge.
In France, the micro-entrepreneur regime calculates social security contributions on actual turnover. If business activity declines, contributions fall accordingly. If there is no income, the financial burden decreases proportionally. Portugal follows a similar philosophy. Contributions for self-employed workers are calculated on the basis of declared income and are updated periodically according to actual business activity. In the Netherlands, many self-employed professionals enjoy greater freedom to decide which insurance cover they wish to purchase, while in Germany not all social insurance schemes are compulsory for the self-employed. Spain, by contrast, still conveys a sense of lower flexibility. For many self-employed workers, the tax calendar does not adapt to the business; rather, the business has to adapt to the tax calendar.
Bureaucracy: the tax no one counts
When people talk about taxation, they almost always think about money. Yet there is another cost that often goes unnoticed: time. Quarterly tax returns, reporting forms, withholding tax filings, regulatory changes, appeals, electronic notifications and tax inspections are all part of the daily routine of thousands of self-employed professionals and small businesses.
This administrative burden is also a form of taxation. It is not paid in money, but in working hours, accounting fees and resources that could otherwise be devoted to generating economic activity.
It is no coincidence that many small businesses end up outsourcing almost all of their tax management. The system has become so complex that complying correctly with the Tax Agency has turned into a specialisation in its own right.
Not all tax authorities treat taxpayers the same way
There is a significant difference in the way European countries understand the relationship between the tax administration and the taxpayer.
In the Nordic countries, digitalisation is not only intended to improve tax fraud control, but also to reduce citizens’ administrative burdens. Denmark, Finland and Sweden have been offering pre-filled tax returns for years, along with highly simplified procedures and a high level of interoperability between public administrations.
Spain has also made considerable progress in digitalisation, particularly through tools such as Renta WEB and the Spanish Tax Agency’s Electronic Office. Nevertheless, many self-employed professionals and small businesses still face a significant administrative burden resulting from recurring tax filings, regulatory changes and reporting obligations that often require professional advice. The difference does not always lie in the taxes themselves. Sometimes it lies in how easy—or difficult—it is for taxpayers to comply with them.
Trust is also part of the tax system
Economists often focus on the tax burden, but there is another indicator that is just as important: institutional trust.
For years, the OECD has studied the relationship between citizens’ trust in public institutions and their voluntary compliance with tax obligations. Its conclusion is clear: taxpayers are more willing to accept a high tax burden when they believe that public resources are managed efficiently, transparently and consistently.
This is one of the major differences between the Nordic and Mediterranean countries. Denmark, Sweden and Finland consistently enjoy very high levels of public trust in their institutions, while Spain generally records significantly lower levels in a range of international indicators.
When citizens believe that public services work well, that regulations are stable and that everyone contributes fairly, paying taxes becomes much easier to accept as part of the social contract. When that trust weakens, any tax increase is more likely to be perceived as an imposition.
The shadow economy also explains many differences
There is one factor that rarely appears in discussions about taxation, yet it profoundly shapes every tax system: the shadow economy.
Countries with higher levels of tax compliance can sustain substantial tax revenues with similar tax rates because they have a broader tax base and lower levels of tax evasion. By contrast, when a significant share of economic activity remains outside the formal system, the tax burden falls more heavily on those who do comply with their obligations.
This vicious circle fuels a sense of unfairness. Honest taxpayers may feel that they bear a disproportionate share of the burden, while tax authorities strengthen enforcement measures to combat fraud, further increasing the perception of surveillance and administrative complexity.
The toughest tax authority is not always the one that collects the most
At this point, the answer is less intuitive than it might seem.
No, Spain is not the European country with the highest tax burden. Nor does it apply the highest tax rates across most major taxes. France, Belgium and Denmark continue to rank higher in many tax revenue indicators. But those figures do not tell the whole story.
A tax authority is not perceived as tough simply because it collects a great deal of revenue. Available income, social security contributions, the flexibility of the system for self-employed workers, administrative complexity, legal certainty and the level of trust citizens place in public institutions all play a role. Together, these factors shape the taxpayer’s everyday experience.
More than a debate about taxes
Perhaps the real debate is not about determining which country collects the most taxes, but rather which tax system achieves the best balance between revenue collection, competitiveness and public trust.
A modern tax authority should not be judged solely by the amount of revenue it raises. It should also be assessed by its ability to encourage voluntary compliance, reduce bureaucracy, provide regulatory stability and adapt to the economic reality faced by taxpayers.
Spain has taken important steps towards modernising its tax administration. Even so, it continues to carry a reputation for being particularly demanding—a perception that cannot be explained solely by the taxes people pay, but also by the way those taxes are administered. And that distinction is fundamental.
Because, ultimately, a good tax authority is not simply the one that collects the most. It is the one that ensures citizens understand why they pay, trust the system and feel that the effort required of them is proportionate to the benefits they receive.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.
The world is changing, and so is the way we pay. While in the past it was common to carry cash or go to the cashpoint, for young people these payment systems have become obsolete. 11Onze agent Mònica Cornudella explains how young people pay for their purchases.
The indispensable tool for all these payments, it is clear, is the mobile phone, and there are at least three methods that are quite common. All are characterised by being quicker, faster and commission-free, but they have the disadvantage of limiting the amount that can be paid, which ranges from 500 to 1,000 euros per transaction. Let’s see what they are!
- Mobile payments linked to a current account or card. In this case, young people only have to link their debit or credit card details to the bank’s application on their mobile phone or take a photograph of the card so that the system can scan the numbers and detect it. At 11Onze you can now order your virtual card through El Canut.
- Payment with a ‘contactless’ card. In this particular method, all you have to do is activate the corresponding application and bring your mobile phone close to a dataphone capable of reading the phone’s NFC chip. This system allows young people to make purchases using radio frequency identification technologies, which are embedded in smart cards in mobile phones or other devices. Moreover, if the purchase does not exceed 20 euros, it is not even necessary to enter the PIN.
- Transfer by mobile phone. Finally, we must talk about what is the most popular way of paying among young people. Surely you have heard of Bizum or PayPal. These are platforms or applications that allow small transfers to be made between individuals using the same mobile phones. Simple and uncomplicated. And you, how do you pay for your purchases?
How do young people pay?