
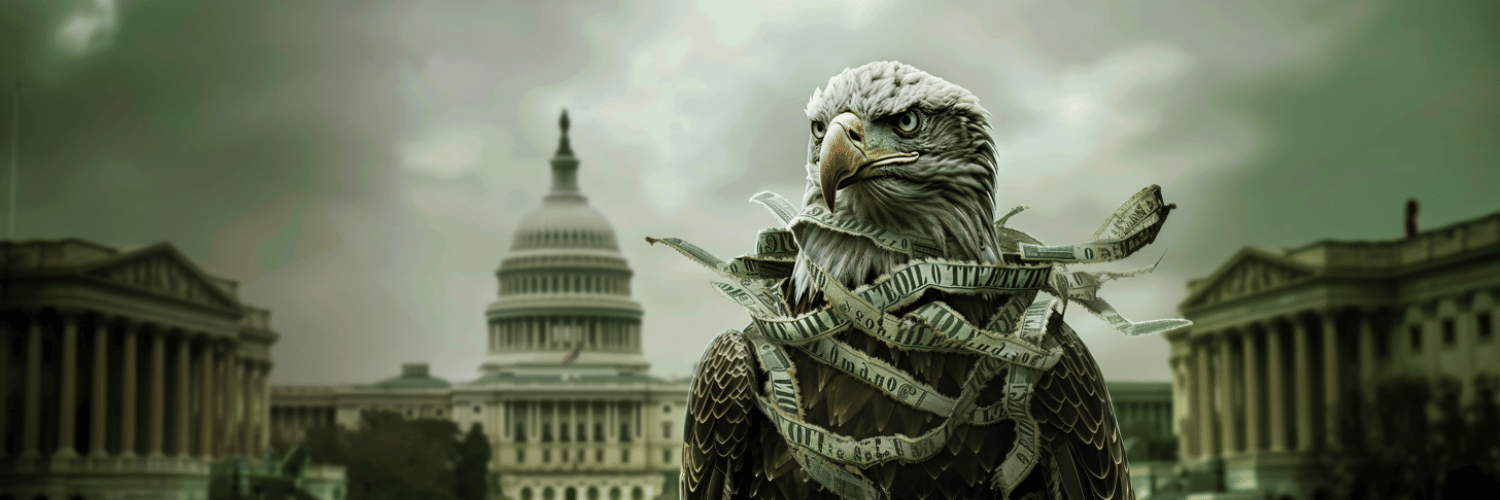
The United States has accumulated one of the largest mountains of debt in the world, but this is not, in itself, the figure that worries economists the most. The real problem is that it increasingly has to allocate more money to paying the interest on that debt, which reduces the room available to finance other public policies. When a growing share of the budget is used simply to keep accumulated debt alive, the risk no longer depends only on how much is owed, but on the cost of continuing to finance it. And this is where a debt crisis stops being an abstract hypothesis and becomes a risk that affects the entire global economy.
Spending more than is earned
To understand the problem, there is no need to master complex economic concepts. Imagine a family that spends more than it earns every year and covers the difference by borrowing money. For a while, the situation may be manageable, especially if interest rates are low. But each new loan is added to the previous ones and, over the years, the family not only has to keep financing its deficit, but also has to pay the interest on the accumulated debt.
Allowing for all the differences, this is the dynamic putting pressure on US public finances. According to projections by the Congressional Budget Office, the United States government will spend around $7.4 trillion in 2026, while revenues will stand at around $5.6 trillion. This leaves a deficit of close to $1.9 trillion.
It is important to distinguish the deficit from the debt. The deficit is the gap generated during a specific year. Debt is the accumulation of previous deficits. Put graphically, the deficit is the water that keeps flowing into the bathtub; the debt is all the water that has already accumulated in it.
A debt larger than the economy
The scale of this accumulation is already considerable. The CBO estimates that federal debt held by the public will reach approximately 101% of US GDP in 2026 and could rise to 120% in 2036 if there are no significant changes in fiscal policy.
This percentage is important because it allows debt to be compared with the country’s economic capacity to sustain it. Owing a lot is not necessarily a problem if the economy grows enough and creditors continue to trust the country’s ability to repay. That is why exceeding 100% of GDP does not automatically mean being on the verge of bankruptcy.
What it does mean is greater vulnerability to interest rates. The larger the debt, the greater the impact of any increase in the cost of financing it. And this is precisely where the US situation has become more complicated in recent years.
When interest payments start to weigh
For much of the past few decades, the United States was able to live with rising debt because borrowing was relatively cheap. Interest rates were low, and this made it possible to refinance large volumes of debt without the bill soaring.
The situation is now different. The CBO expects the federal government to allocate more than $1 trillion to net interest payments in 2026, a figure that could exceed $2.1 trillion a year by 2036.
This spending has an important characteristic: it does not finance hospitals, roads, education or research. It simply remunerates the creditors who lent money to the government. The greater the weight of interest payments within the budget, the less room there is to allocate resources to other priorities.
In addition, a large share of the debt periodically reaches maturity and has to be refinanced. If those bonds were issued at a time of very low interest rates and now have to be replaced by new securities offering a higher return, the financial cost increases automatically.
When debt feeds more debt
From this point onward, a dynamic that is difficult to break can emerge. If the government maintains high deficits, it needs to issue more debt. This new debt generates new interest payments, which increase spending and can widen the deficit even further.
Therefore, the problem is not only that the United States owes a lot of money, but that the very cost of the debt can contribute to making it grow.
The CBO estimates that net interest payments will rise from 3.3% of GDP in 2026 to 4.6% in 2036. In this scenario, a growing share of public revenues will simply be used to pay the cost of previous budgetary decisions.
This is where the difference lies between having a lot of debt and starting to have a debt problem. A powerful economy can sustain high levels of indebtedness for a long time, but if debt persistently grows faster than the economy, the situation becomes increasingly demanding.
A crisis does not need to begin with a default
When we think of a debt crisis, we often imagine a government announcing that it cannot pay. But in the case of the United States, a crisis could begin much earlier.
The first sign could simply be investors demanding higher returns in order to keep buying Treasury bonds. If they perceive that the fiscal path is becoming increasingly unsustainable, they may demand higher interest rates in exchange for continuing to lend money.
An apparently small difference in interest rates can have a huge impact when applied to tens of trillions of dollars. And this effect would not be limited to US public finances.
Treasury Bonds are a central benchmark for the international financial system. If their yields rise, mortgages, business loans and the debt of other governments can also become more expensive. That is why a crisis of confidence in US debt would have global repercussions.
The extraordinary privilege of the dollar
The United States, however, has an advantage that almost no other country has: it borrows in its own currency, and that currency is also the world’s main reserve currency.
This greatly reduces the risk of a conventional bankruptcy. The Treasury issues debt in dollars and the Federal Reserve has the capacity to provide liquidity to the system. It is an extraordinary privilege that gives Washington far more room for manoeuvre than almost any other economy would have.
But that room is not unlimited. If monetary creation were used excessively to facilitate debt financing, the consequences could emerge through another channel: higher inflation, a depreciation of the dollar or a gradual loss of investor confidence.
Put another way, being able to create the currency in which the debt is paid reduces the risk of default, but it does not eliminate the economic cost of excessive indebtedness.
Everything depends on confidence
In the end, the key word is this: confidence. There is no exact figure beyond which a state automatically enters a crisis. What determines debt sustainability is investors’ confidence in the government’s ability to keep paying without having to resort to extreme measures.
For decades, the United States has enjoyed a privileged position thanks to the size of its economy, the depth of its financial markets and the international role of the dollar. This combination explains why the world remains willing to finance Washington despite its recurring deficits.
But that confidence is not infinite. The important question, therefore, is not whether the United States will go bankrupt tomorrow. The question is how long it can maintain a trajectory in which debt grows faster than the economy and interest payments absorb an increasingly large share of the budget.
A US problem with global consequences
As long as investors remain willing to buy US debt at an affordable cost, the system can continue to function. But if that cost rises on a sustained basis, the problem stops being a simple accounting figure and becomes a real constraint on the economy.
A US debt crisis, therefore, would not necessarily begin on the day Washington stopped paying. It could begin much earlier, at the moment when the world demanded an increasingly high price to continue lending it money.
And when the borrower is the country that issues the world’s main reserve currency and sits at the centre of the international financial system, the bill is unlikely to remain only at home.
Protecting savings with physical gold has been one of 11Onze’s greatest contributions to its community, and its range of products continues to expand. In today’s environment of market volatility, persistently high inflation and growing distrust in the banking system, gold is once again strengthening its role as a safe-haven asset. Discover Or Llavor at Preciosos 11Onze.

 Equip Editorial

